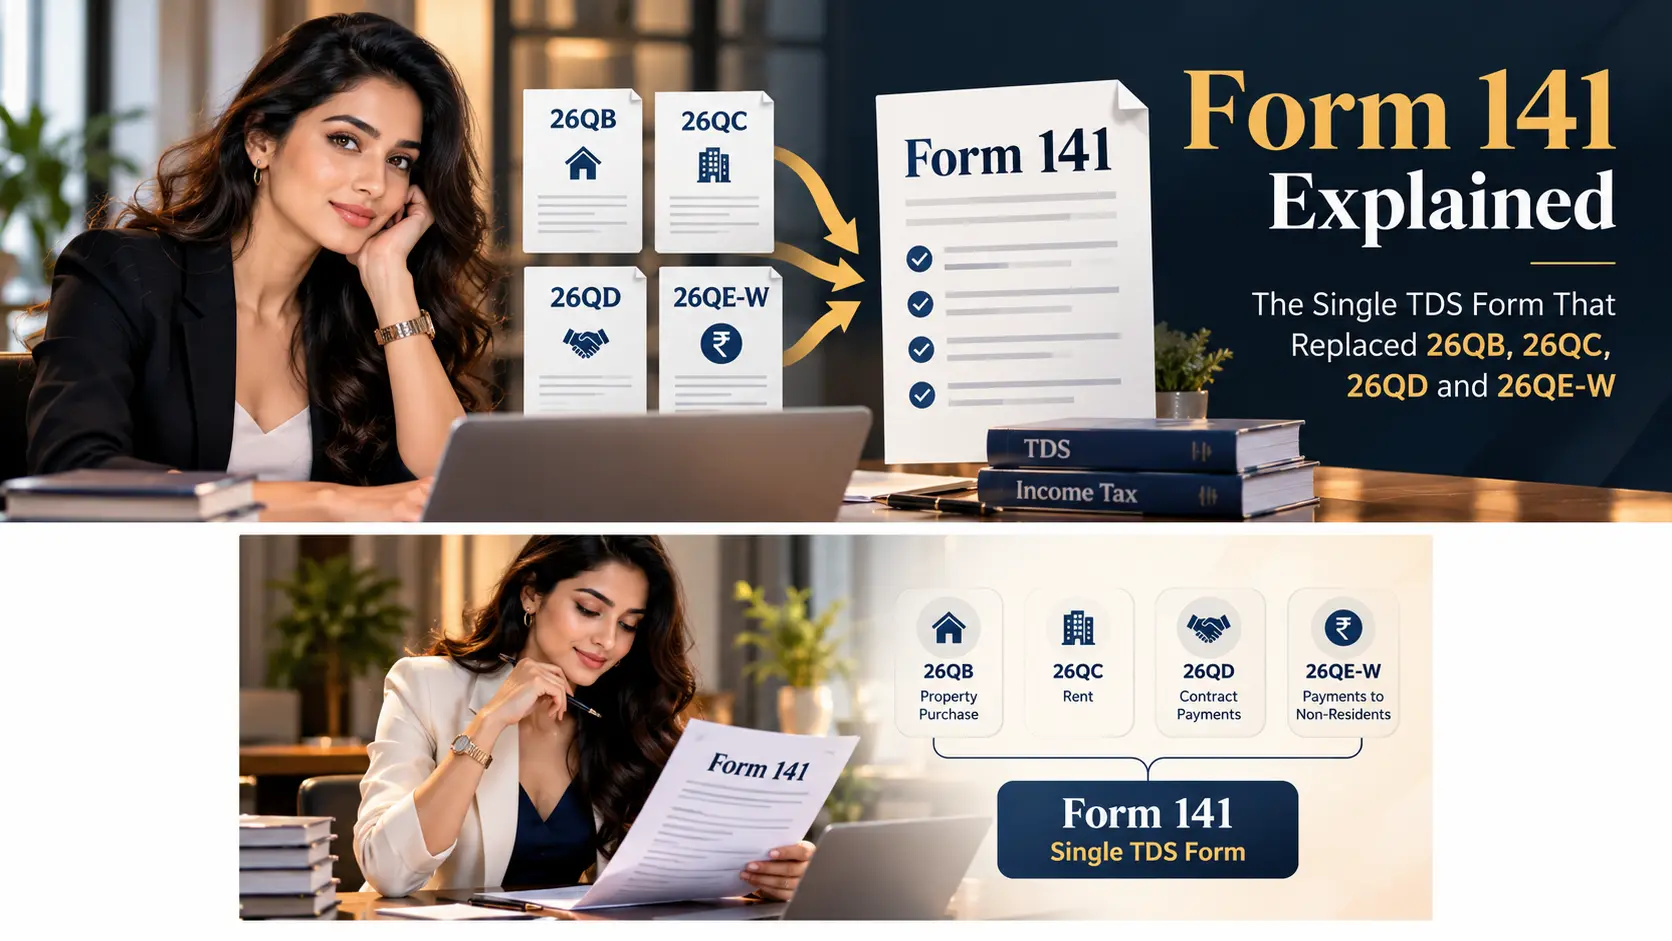
Four challan-cum-statements have been consolidated into one. From Tax Year 2026-27, TDS on property, rent, contract payments and virtual digital assets is reported in a single form.
Form 141 is the challan-cum-statement through which TDS is now paid and reported on a small group of transactions where the law casts the obligation to deduct on individuals who are not otherwise deductors: the purchase of immovable property, rent above the prescribed limit, large payments to contractors and professionals, and the purchase of virtual digital assets. Under the 1961 Act and the 1962 Rules, each had its own form: 26QB, 26QC, 26QD and 26QE. Under the Income-tax Act, 2025, they are four schedules of a single form, and since 1 October 2026 a fifth schedule covers property purchased from a non-resident.
In substance, little has changed. No TAN is required, the 30-day window from the month-end continues, and the rates and thresholds for property and rent are unchanged. What has changed is the statutory reference, the filing path on the portal and the certificate number. This guide examines each of these, together with the interest and late-fee computation referred to in our two template posts.
- Form 141 replaced Forms 26QB, 26QC, 26QD and 26QE. One schedule per form.
- No TAN. Filed and paid on the e-filing portal using the deductor’s PAN.
- Due: within 30 days from the end of the month in which tax is deducted.
- Delay: interest at 1% or 1.5% per month, plus a late fee of ₹200 per day, capped at the TDS.
- Certificate: Form 132 (earlier Form 16B for property and 16C for rent), downloaded from TRACES.
- Corrections: on TRACES, within two years from the end of the relevant tax year.
Compute the TDS before filing. Free Excel calculators for property and rent ↓
What Is Form 141 Under the Income-tax Act, 2025?
Form 141 is titled a “challan-cum-statement of deduction of tax”. Both elements of the title are significant. It is a challan because the tax is paid through it, and a statement because the same submission reports the deductor, the deductee, the amount and the date. On submission the portal generates an Acknowledgement Receipt Number (ARN); once payment goes through, a Challan Identification Number (CIN) is generated against it. No separate quarterly TDS return is required.
The PAN-based design reflects the nature of these deductors. A tenant or a home buyer typically deducts tax once in a year, and often only once, so obtaining a TAN and filing periodic returns would be disproportionate. The official FAQs make Form 141 applicable to transactions pertaining to Tax Year 2026-27 onwards.
One form, one schedule
The schedule is determined by the nature of the transaction. A form cannot carry two schedules.
PAN, not TAN
Filed from the deductor’s own e-filing login. The deductee’s PAN must be valid and correctly quoted.
Pay and report together
ARN on submission, CIN on payment. A late payment is therefore also a late statement.
Form 141 Schedules A to E: Which One Is Yours?
The schedule follows the transaction. The mapping to the earlier provisions and forms, drawn from the official Form 141 FAQs and the e-filing help page, is set out below.
| Schedule | Covers · who can use it | 2025 Act · earlier |
|---|---|---|
| A | Rent paid Individual and HUF deductors only | 393(1), Sl. No. 2(i) Earlier 194-IB · Form 26QC |
| B | Purchase of immovable property from a resident All categories of deductor | 393(1), Sl. No. 3(i) Earlier 194-IA · Form 26QB |
| C | Payments to resident contractors and professionals Individual and HUF deductors only | 393(1), Sl. No. 6(ii) Earlier 194M · Form 26QD |
| D | Transfer of virtual digital assets Individual and HUF deductors only | 393(1), Sl. No. 8(vi) Earlier 194S · Form 26QE |
| E | Immovable property bought from a non-resident (from 1 October 2026) Resident individual and HUF buyers only | 393(2), Sl. No. 17 Earlier 195 · TAN-based return |
The FAQs also restate the thresholds: rent of ₹50,000 for a month or part of a month, property of ₹50 lakh or more, contractor and professional payments of ₹50 lakh, and no monetary limit for virtual digital assets.
Two points merit attention. First, Schedules A, C and D are available only to individuals and HUFs; a company or firm paying rent or a contractor continues to report through the regular TAN-based TDS returns. Second, Schedule B is open to all categories of deductor, so a company purchasing an office from a resident also reports the deduction in Form 141.
The FAQs’ summary table lists the old sections (194-IA, 194-IB, 194M, 194S) and the new serials (2(i), 3(i), 6(ii), 8(vi)) in different orders, so the pairing is not spelt out in one line. It follows from the schedule answers: Schedule A is rent under Sl. No. 2(i) and replaced Form 26QC, and Schedule B is property under Sl. No. 3(i) and replaced Form 26QB. Our Section Mapping tool and Forms Mapping tool carry the full old-to-new tables.
Paying rent or purchasing property? Compute the TDS with our free templates ↓
Form 141 Due Date: The 30-Day Rule
The tax has to be deposited, and Form 141 furnished, within 30 days from the end of the month in which tax is deducted. As the form is itself the challan, both are completed in a single submission. The period runs from the month of deduction rather than the date, so a deduction on the 1st or the 31st of a month carries the same due date.
| Tax deducted in | Form 141 due by | Typical case |
|---|---|---|
| June 2026 | 30 July 2026 | Property payment on 30 June 2026 |
| September 2026 | 30 October 2026 | Tenancy ending in September |
| January 2027 | 2 March 2027 (but see below) | Property instalment in January |
| March 2027 | 30 April 2027 | Annual rent TDS for Tax Year 2026-27 |
A point of caution. The FAQs specify 30 days, whereas the e-filing help page states that the statement is due “within one month from the end of the month”. The two diverge only for a January deduction: 30 days runs to 2 March, while one month ends on 28 February. Pending clarification, January deductions should be reported by 28 February.
One month, one form
A single Form 141 can carry several transactions of the same nature, provided the tax was deducted in the same month. Transactions from different months cannot be clubbed. Payments to a builder in July and again in September therefore require two forms, each with its own due date.
Due date from the date of deduction: Both templates compute it automatically ↓
How to File Form 141 on the e-Filing Portal
Form 141 is submitted only through the income tax e-filing portal, using the deductor’s PAN login. The sequence below follows the portal’s help page.
- Assemble the details. The deductee’s PAN, the date of payment or credit, the amount and the TDS figure. Check the fourth character of the deductee’s PAN: if it is “C”, the deductee is corporate; otherwise non-corporate. An incorrect selection results in validation errors.
- Open the form. Log in, go to e-File → E-Pay Tax, select Income Tax Act, 2025, click New Payment and choose Form 141.
- Choose one schedule and fill it in. Joint deductors each file their own form for their own share. Several deductees can share a form if they are the same deductee type and the deduction month is the same.
- Submit and pay. An ARN is generated on submission and a CIN once payment goes through. Confirmation is also sent by SMS and email.
- Verify the record. The filed form appears under e-File → E-Pay Tax → Income Tax Act, 2025 → Payment history. If it does not, a grievance may be raised on the portal.
- Issue the certificate. After processing, log in to TDS-TRACES, download the certificate in Form 132 and furnish it to the deductee. For rent, it is due within 15 days of the Form 141 due date.
Form 141 Late Fee and Interest: How the Cost Builds Up
Our template posts refer to this section for the detailed computation. Three distinct charges may arise, and they are cumulative.
| Charge | Provision | Rate | Runs |
|---|---|---|---|
| Interest for late deduction | Section 398(3)(a) | 1% a month | From the date tax was deductible to the date it was actually deducted |
| Interest for late deposit | Section 398(3)(a) | 1.5% a month | From the date of deduction to the date of deposit |
| Late fee | Section 427 | ₹200 a day | From the due date until Form 141 is filed, capped at the TDS amount |
For interest, a part of a month is treated as a full month. Our templates count calendar months, so a deduction in June and a deposit in September represent four months. Further, since Form 141 is a challan and a statement in one, a late deposit is necessarily a late filing: the 1.5% interest and the daily late fee arise together.
Three worked examples
| Case | Interest | Late fee | Total |
|---|---|---|---|
| Property. TDS ₹80,000 deducted 30 June 2026 (due 30 July); deposited and filed 10 September 2026 | 4 months × 1.5% = ₹4,800 | 42 days × ₹200 = ₹8,400 | ₹13,200 |
| Rent, late deposit. TDS ₹14,400 deducted 31 March 2027 (due 30 April); deposited and filed 15 June 2027 | 4 months × 1.5% = ₹864 | 46 days × ₹200 = ₹9,200 | ₹10,060 |
| Rent, late deduction. TDS ₹14,400 should have been deducted in March 2027; actually deducted, deposited and filed on 20 May 2027 | 3 months × 1% = ₹432 | Nil (filed well before the 30 June due date for a May deduction) | ₹430 |
All three are computed with the late-compliance section of our templates; totals are rounded to the nearest ₹10.
In most cases of delay, it is the late fee, not the interest, that dominates. In the second example, a delay of 46 days produced a fee of ₹9,200, nearly two-thirds of the tax deducted. Where a due date has been missed, the statement should be filed at the earliest, since the fee accrues daily.
The third row reflects how the templates read the law: the due date runs from the month tax is actually deducted, so a late deduction that is deposited promptly attracts the 1% interest but no late fee. That reading is consistent with the FAQs’ wording; nonetheless, timely deduction remains the only course that carries no cost.
Quantify the exposure on actual figures. Late-compliance section in our free templates ↓
Correcting Form 141 and the Mistakes That Cause Trouble
Mistakes in a filed Form 141 are fixed through a correction statement on TDS-TRACES, not on the e-filing portal; the deductor must first register on TRACES as a taxpayer. The window is two years from the end of the tax year in which the statement was due. A Form 141 due on 30 July 2026 falls in Tax Year 2026-27, which ends on 31 March 2027, so it can be corrected until 31 March 2029.
The error that matters most is a wrong or invalid deductee PAN. The FAQs are explicit about the consequence: the credit will not appear in the deductee’s Annual Tax Statement or Form 26AS, and a higher rate of deduction may apply. Such an error typically leads to a query from the deductee and should be corrected promptly.
- One joint buyer files for everyone. Each deductor files a separate Form 141 for his own share.
- Two months in one form. Only same-nature transactions deducted in the same month can be clubbed.
- Wrong deductee type. Corporate if the fourth character of the PAN is “C”; otherwise non-corporate.
- Company tenant using Schedule A. Schedule A is only for individuals and HUFs. Others use the TAN-based returns.
- Deducting on the excess. Property TDS is on the whole value once the ₹50 lakh test is met, not on the part above it.
- Forgetting the certificate. The deductee needs Form 132 to match the credit. Download it from TRACES once the form is processed.
Free Form 141 Templates: Compute the TDS Before Filing
Form 141 records the amount of TDS; it does not compute it. Our two free Excel calculators, built for the Income-tax Act, 2025, determine the TDS, the due date and the cost of any delay for the two most commonly used schedules.
TDS on Property Purchase Calculator (Schedule B)
1% on the higher of price and stamp duty value, the ₹50 lakh test, up to four joint buyers, the no-PAN rate, and the interest and late fee for any delay.
TDS on Rent Calculator (Schedule A)
2% on rent above ₹50,000 a month, deducted once a year, the no-PAN cap, rent that changes mid-year, and the interest and late fee for any delay.
Templates for Schedules C, D and E are not yet available. Schedule E, in particular, involves the non-resident rate and computation, which our property template deliberately excludes.
Form 141: Frequently Asked Questions
What is Form 141 and which forms did it replace?
Form 141 is the challan-cum-statement through which tax deducted under Section 393 of the Income-tax Act, 2025 on certain specified transactions is both paid and reported. It replaces four earlier forms: 26QB (purchase of immovable property), 26QC (rent), 26QD (payments to contractors and professionals) and 26QE (transfer of virtual digital assets). Each now forms a separate schedule. With effect from 1 October 2026, a fifth schedule, Schedule E, covers immovable property purchased from a non-resident by a resident individual or HUF.
Do I need a TAN to file Form 141, and what do I give the deductee afterwards?
No. Form 141 is filed on the e-filing portal using the deductor’s PAN. Once the statement is processed, the deductor downloads the TDS certificate in Form 132 from TRACES and furnishes it to the deductee, whether landlord, seller or payee. In the case of rent, the certificate is due within 15 days of the Form 141 due date.
What is the due date for Form 141?
Within 30 days from the end of the month in which tax is deducted. Tax deducted in June 2026 is therefore due by 30 July 2026, and tax deducted in March 2027 by 30 April 2027. The e-filing help page describes the statement deadline as one month from the end of the month. The two formulations differ only for deductions made in January; as a matter of prudence, those should be reported by 28 February.
Can I report two transactions in one Form 141?
Only where the transactions are of the same nature and tax was deducted in the same month. Two property instalments paid in July and September require two separate Form 141s. Further, a form can carry only one schedule, so rent and a property payment cannot be reported together.
We are joint buyers, or there are two sellers. How many Form 141s are needed?
One for each deductor. Each joint buyer files a separate Form 141 for his proportionate share. Conversely, several deductees, such as two co-owner sellers, may be reported in the same form, provided they are of the same deductee type and tax was deducted in the same month.
Can I correct a mistake in Form 141?
Yes, by filing a correction statement. Corrections are made on TDS-TRACES, where the deductor registers as a taxpayer, and not on the e-filing portal. The time limit is two years from the end of the tax year in which the statement was due; a Form 141 due on 30 July 2026 may therefore be corrected until 31 March 2029. An incorrect deductee PAN is the most consequential error, as the credit will not appear in the deductee’s Annual Tax Statement or Form 26AS.
What is the late fee and interest for Form 141?
Three charges may arise. Interest under Section 398(3)(a) is payable at 1% per month for late deduction and 1.5% per month for late deposit, a part of a month being treated as a full month. In addition, a late fee under Section 427 of ₹200 per day applies from the due date until the statement is filed, subject to a ceiling equal to the TDS amount. Since Form 141 is a challan and a statement in one, a late deposit is also a late filing, and the late-deposit interest and the late fee ordinarily arise together.
I am buying property from an NRI. Can I use Form 141?
Yes, where the buyer is a resident individual or HUF and the transaction falls on or after 1 October 2026. Schedule E of Form 141 covers tax deducted under Section 393(2) on immovable property purchased from a non-resident. The rate and computation differ from the 1% rule applicable to resident sellers and should be determined first. Other categories of buyer continue to use the TAN-based route.
Before filing: Download the property and rent TDS calculators ↓
Templates and tools that work with Form 141
TDS on Property Purchase Calculator Excel
Section 194-IA, now Section 393. Buyers, joint buyers and the late-fee working.
Free Template · Schedule ATDS on Rent Calculator Excel
Section 194-IB, now Section 393. One deduction a year, and rent that changes mid-year.
ToolIncome Tax Forms 2026 Mapping Tool
Find the new form number for any old form, 26QB to 16C and beyond.
ToolIncome Tax Act 2025 Section Mapping
Old 1961 Act sections matched to their 2025 Act equivalents.
Free TemplateTDS Working Template — Excel
A working sheet for TDS across payment types.
Free TemplateTDS on Salary Calculator — Income-tax Act, 2025
Monthly TDS on salary under Section 392.
Form 141 is a genuine simplification: one filing path, one form, five schedules, and no TAN. It does not, however, alter the three factors that determine whether a deductor incurs cost: deduction on the correct base, deposit within 30 days of the month-end, and an accurate deductee PAN. The TDS should be computed before the payment date, the statement filed in the same sitting as the payment, and Form 132 issued as soon as it becomes available.
Sources & References
- Form No. 141 — Frequently Asked QuestionsIncome Tax Department. Schedules A to D, Rules 218 and 219, thresholds, due date, Form 132, corrections, applicability from Tax Year 2026-27.
- Form 141 — Challan-cum-Statement, e-Filing help pageIncome Tax e-Filing Portal. Schedule E from 1 October 2026, who can use each schedule, filing path, TRACES for certificates and corrections.
- Income-tax Act, 2025 (as amended by the Finance Act, 2026)Sections 393, 398(3)(a) and 427.
- Income Tax Law Mapping: Old Act vs New Acttaxbizmantra.com. Old-to-new section and form mapping hub.
Disclaimer: This article is for general information and education only. It is not legal or tax advice. It reflects the Income-tax Act, 2025, the Income-tax Rules, 2026 and the official Form 141 guidance as we read them in October 2026; portal screens and procedures change, and the difference between the “30 days” and “one month” wording for January deductions has not been officially clarified. Verify against the Act and the latest Form 141 instructions before depositing or filing, and consult a Chartered Accountant on the specific facts.