Section 80GG Rent Deduction Calculator Excel 2026–27
Calculate your Section 80GG rent deduction for 2026–27 with a free Excel calculator. Check eligibility, ₹60,000 annual limit, 25% income test, rent-minus-10% test and Form 10BA requirement.
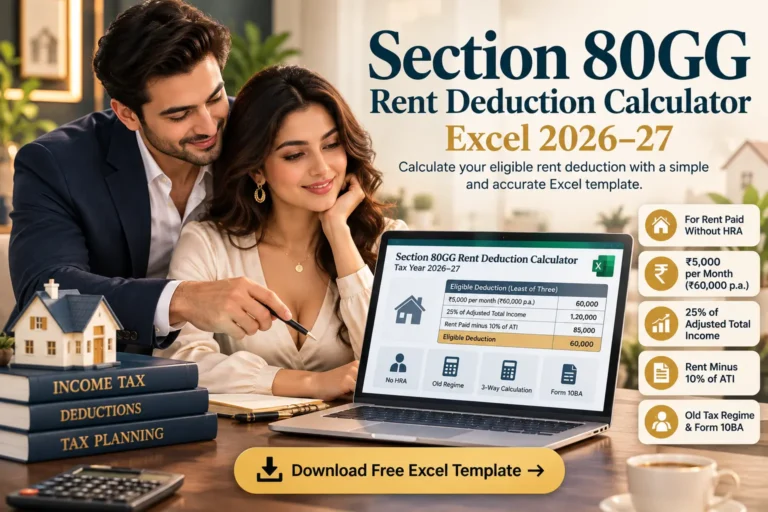
Calculate your Section 80GG rent deduction for 2026–27 with a free Excel calculator. Check eligibility, ₹60,000 annual limit, 25% income test, rent-minus-10% test and Form 10BA requirement.
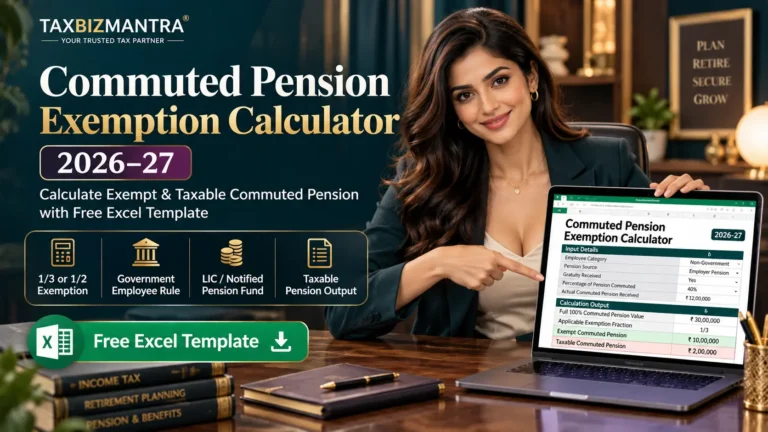
Calculate commuted pension exemption with this free Excel calculator for Tax Year 2026–27. Determine the full commuted value, applicable 1/3 or 1/2 exemption and taxable pension.
Can an Indian power of attorney make a foreign company a tax resident in India? The Delhi High Court examines the issue in SFDC Ireland Ltd. v. CIT.
Can the TDS limitation period restart for every quarterly statement? The Bombay High Court explains how Section 201(3) applies to each TDS statement.
Can the Income Tax Department inspect seized jewellery kept in sealed packages without first sharing the reasons? The Calcutta High Court answers this under Rule 112(13).
Can a court force the Income Tax Department to disclose PAN details in a cash loan recovery suit? The Madras High Court held that while the court can inform the Income Tax Department about suspected cash transactions, it cannot compel PAN disclosure through the suit.
Can prosecution survive after a compounding fee is paid? In Jyotsana Investments Co. Ltd. v. R.K. De, the Calcutta High Court examined a prosecution delayed for nearly 40 years and held that continuing the criminal proceedings after compounding, in the circumstances of the case, violated Article 21. The ruling highlights the importance of delay, compounding and the right to a fair and timely legal process.
Shiv Kumar Jaiswal v. State of U.P. examines whether criminal prosecution can continue when the underlying penalty order has already been deleted. The Allahabad High Court considered the effect of the deletion of the penalty on the foundation of the prosecution proceedings and addressed whether such prosecution could survive once the corresponding penalty no longer remained in force.
Vidya Sagar Sharma v. UOI examines whether a taxpayer could seek relief under the Vivad Se Vishwas 2024 Scheme after a DTVSV 2020 declaration became void. The J&K High Court considered the effect of the statutory revival of the pending revision proceedings and held that the assessee could pursue the DTVSV 2024 route.
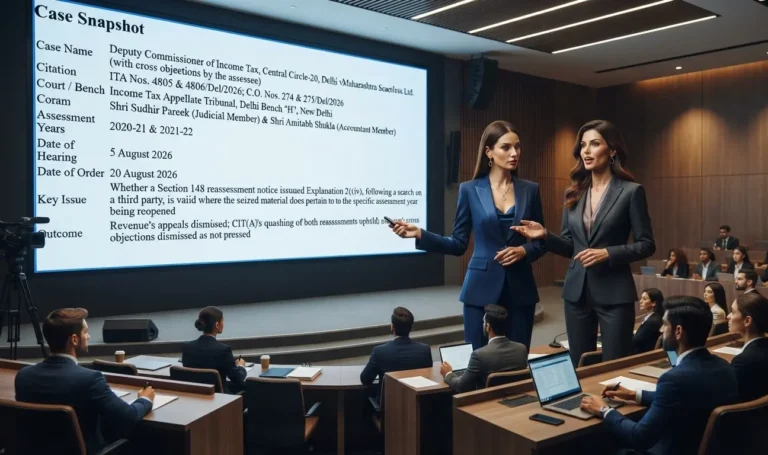
Can Section 148 reopening survive if the seized material relates to the wrong year? ITAT Delhi says the search material must have a clear connection with the assessment year being reopened.