EPF and PPF are often described as tax-free savings options. But “tax-free” does not mean exactly the same thing for both. The real difference appears when you examine the contribution rules, interest taxation, withdrawal conditions and the tax regime you choose.
The Employees’ Provident Fund (EPF) and the Public Provident Fund (PPF) are two popular long-term savings instruments in India. Although both are commonly associated with provident fund benefits, they are not identical. EPF is primarily an employment-linked retirement benefit, whereas PPF is an individual long-term savings account.
Their tax treatment also differs. EPF may involve employee contributions, employer contributions, interest accumulation and service-related withdrawal conditions. PPF generally follows the familiar Exempt-Exempt-Exempt (EEE) structure, subject to the applicable scheme and tax provisions.
This guide explains EPF vs PPF taxation under the Income-tax Act, 2025, including the treatment of contributions, interest, maturity proceeds, premature withdrawal and the special interest-taxation thresholds applicable to certain provident fund contributions.
PPF generally follows an Exempt-Exempt-Exempt (EEE) structure, subject to the applicable scheme and tax provisions. EPF is also tax-efficient, but its tax treatment is conditional. Employee contributions may qualify for deduction under the applicable provisions, interest relating to certain excess employee contributions may become taxable, and withdrawal before the required service period may have tax consequences. Employer contributions and related annual accretion are also subject to specific statutory rules and limits.
EPF vs PPF: The Basic Difference
EPF and PPF may appear similar because both are long-term provident fund instruments. However, their source of contribution, purpose, account structure and withdrawal rules are different.
Employees’ Provident Fund
EPF is generally connected with eligible employment under the Employees’ Provident Funds framework. Contributions are generally made by both the employee and the employer, subject to the applicable employment and contribution rules.
Public Provident Fund
PPF is a voluntary long-term savings scheme. An eligible individual can open an account and make contributions within the prescribed limits. There is no employer contribution, and the account does not depend on the individual’s employment. Withdrawals and premature closure remain subject to the applicable scheme conditions.
EPF and PPF may both be called provident funds, but their tax treatment cannot be determined merely from that description. The applicable statutory provision, type of fund, source of contribution and withdrawal conditions must be examined separately.
Tax Treatment of EPF and PPF Contributions
The first stage of provident fund taxation is the contribution itself. EPF and PPF differ significantly because EPF may contain both employee and employer contributions, while PPF is funded by the individual.
Employee Contribution to EPF
An employee’s contribution to a recognised provident fund may qualify for deduction under the applicable specified-investment provisions, subject to the prescribed conditions, limits and tax regime.
Under the Income-tax Act, 2025, the relevant deduction framework is contained in Section 123 read with Schedule XV, subject to the applicable provisions and restrictions.
The availability of the deduction depends on the tax regime selected. Therefore, an employee should not assume that every deduction available under the old regime is also available under the default new tax regime.
Employer Contribution to EPF
Employer contributions to a recognised provident fund are not automatically taxable merely because they are credited to the employee’s account. Their treatment depends on the applicable statutory conditions and limits.
In addition to the applicable provident fund conditions, the combined employer contribution to a recognised provident fund, the specified pension scheme and an approved superannuation fund is subject to an aggregate ceiling of ₹7,50,000 in a tax year.
To the extent the applicable aggregate limit is exceeded, the excess may be treated as a taxable perquisite under Section 17(1)(h) of the Income-tax Act, 2025.
Contribution to PPF
PPF contributions are made by the individual. There is no employer contribution and, therefore, the aggregate employer-contribution ceiling applicable to specified retirement funds does not apply to an individual’s PPF investment.
Eligible PPF contributions may qualify for deduction under Section 123 read with Schedule XV, subject to the applicable annual limit, qualifying conditions and tax regime. The commonly recognised specified-investment ceiling is ₹1,50,000 for the aggregate eligible deductions, subject to the applicable law. It is not a separate PPF-only limit.
The ₹7.5 lakh aggregate limit relates to specified employer retirement contributions. It is not a limit on an individual’s own PPF investment and it does not determine whether PPF interest or maturity proceeds are taxable.
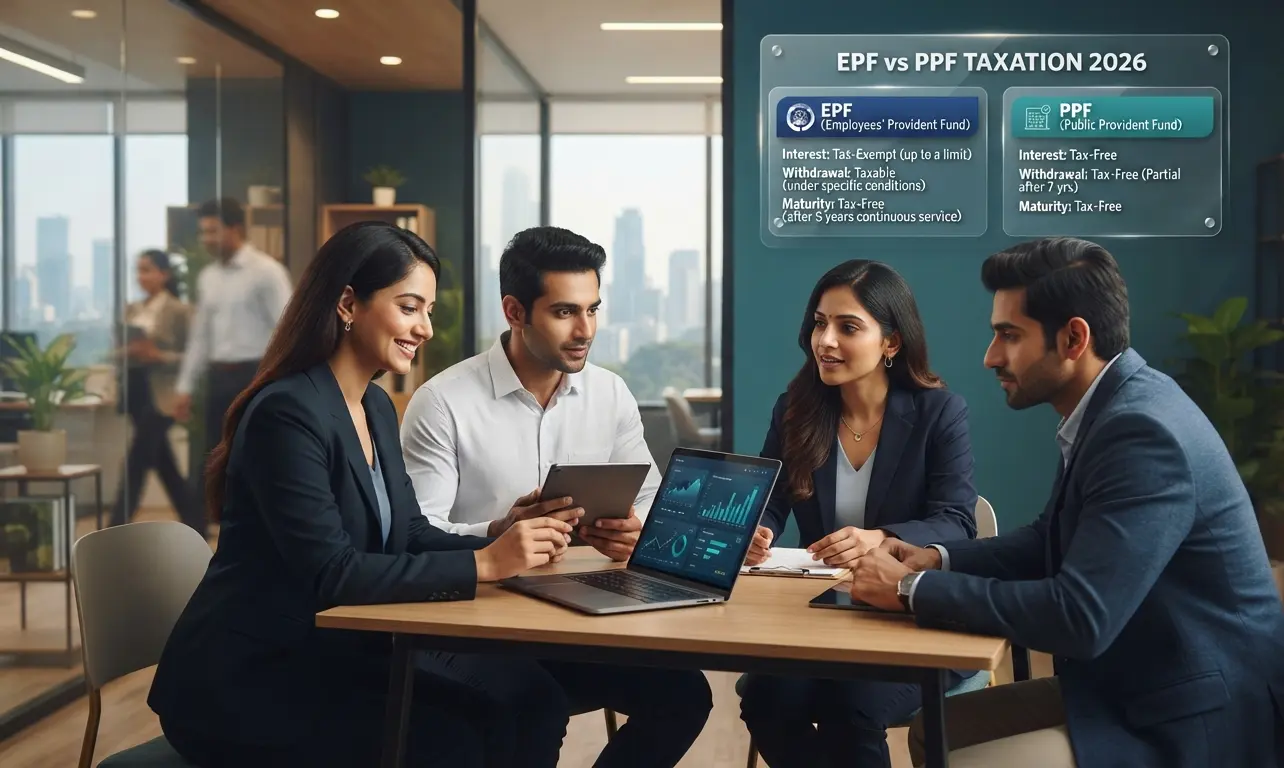
Is EPF and PPF Interest Tax-Free?
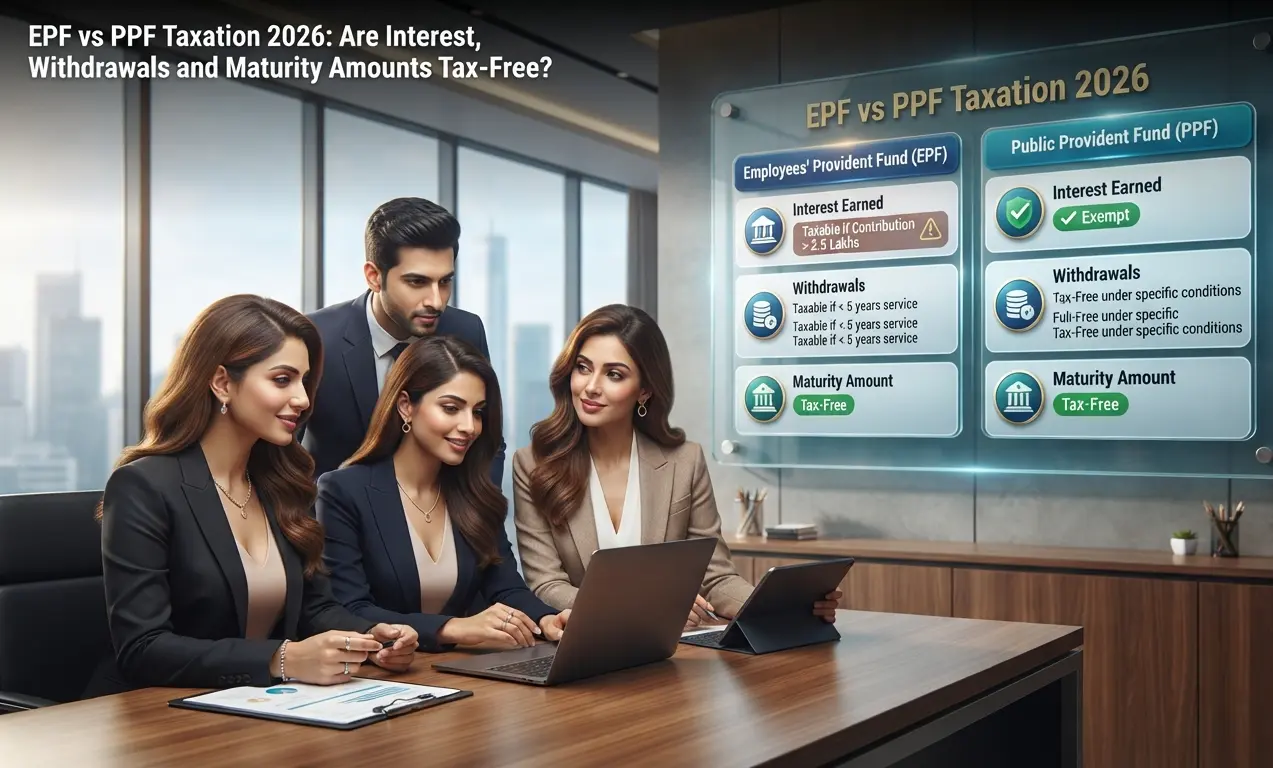
Interest taxation is one of the most important differences between EPF and PPF. PPF interest is generally exempt, while EPF interest is generally exempt subject to specific statutory exceptions.
Taxation of EPF Interest
Interest credited to a recognised provident fund is generally exempt from income tax. However, interest relating to certain excess employee contributions may become taxable.
The commonly applied thresholds are as follows:
- Where the employer also contributes to the provident fund, interest relating to the employee’s contribution exceeding ₹2,50,000 in a tax year may become taxable.
- Where the employer does not contribute to the fund, interest relating to the employee’s contribution exceeding ₹5,00,000 in a tax year may become taxable.
- Interest credited above the notified or otherwise applicable statutory rate may also be subject to tax under the relevant provident fund provisions.
The taxable amount is not necessarily the entire EPF interest. The rule generally targets the interest attributable to the contribution falling beyond the prescribed threshold. Separate computation mechanisms are used to identify the taxable portion.
Taxation of PPF Interest
Interest earned on PPF is generally exempt from income tax. Unlike EPF, PPF does not have an equivalent ₹2.5 lakh or ₹5 lakh employee-contribution threshold for taxing interest.
This is one of the principal reasons PPF is commonly described as an Exempt-Exempt-Exempt investment.
Contribution
Eligible contributions may qualify for deduction under the applicable specified-investment provisions, subject to the selected tax regime and statutory limits.
Interest
Interest credited to the PPF account is generally exempt from income tax during the investment period.
Maturity
Eligible maturity proceeds and permitted withdrawals are generally exempt from income tax.
The ₹2.5 lakh and ₹5 lakh thresholds relate to interest on specified employee contributions to provident funds during the relevant tax year. They do not mean that every EPF contribution above those amounts becomes taxable in full. The taxable portion is generally the interest attributable to the excess contribution, as determined under the prescribed computation rules.
Withdrawal and Maturity Taxation
The final stage of the EPF and PPF tax comparison is the treatment of money received from the account. EPF withdrawal is connected with employment and service conditions, while PPF follows a prescribed maturity and withdrawal framework.
EPF Withdrawal After the Required Service Period
Withdrawal from a recognised provident fund after the prescribed service period is generally exempt from income tax. The commonly applied condition is completion of five years of continuous service.
Eligible service with a previous employer may generally be included where the provident fund balance is transferred to the current employer’s provident fund account.
Certain exceptions may also apply where employment ends because of circumstances beyond the employee’s control, such as ill health, discontinuation of the employer’s business or other prescribed reasons.
EPF Withdrawal Before the Required Service Period
If a recognised provident fund is withdrawn before completion of the required service period and no statutory exception applies, the tax treatment may be recalculated as though the fund had not been recognised from the beginning.
In such a case, the employer’s contribution and the interest attributable to it may become taxable under the applicable salary provisions. The employee’s own contribution is not taxed again merely because it is returned, although any earlier deduction claimed may need to be considered under the applicable rules.
EPF Withdrawal and TDS
Tax deduction at source may apply to a taxable EPF accumulated balance under the applicable provisions. Section 192A generally deals with TDS on taxable payments from an employee provident fund account, subject to the prescribed threshold and exceptions.
TDS is only a mechanism for collecting tax. It does not by itself determine whether the entire withdrawal is taxable. Final taxability depends on the nature of the withdrawal and the applicable exemption conditions.
PPF Withdrawal and Maturity
PPF has a prescribed long-term maturity period, generally fifteen years from the end of the year in which the account is opened. The account may be extended in permitted blocks after maturity.
Eligible PPF maturity proceeds are generally exempt from income tax. Permitted partial withdrawals and premature-closure proceeds are also generally treated as exempt, subject to the conditions governing the PPF scheme.
EPF tax-free withdrawal depends on the applicable service and statutory conditions. PPF does not depend on completing five years of employment because it is not an employment-linked retirement fund.
EPF vs PPF Taxation: Side-by-Side Comparison
The following table summarises the principal tax differences between EPF and PPF. The exact result may vary depending on the type of provident fund, the applicable tax regime, contribution levels and the circumstances of withdrawal.
| Particulars | EPF | PPF |
|---|---|---|
| Nature of account | Employment-linked retirement benefit | Voluntary individual long-term savings account |
| Employee or individual contribution | May qualify for deduction under applicable provisions, subject to regime and limits | May qualify for deduction under Section 123 read with Schedule XV, subject to regime and limits |
| Employer contribution | Applicable; subject to statutory conditions and aggregate retirement-fund ceiling | Not applicable |
| Interest taxation | Generally exempt, subject to excess-contribution and other statutory exceptions | Generally exempt |
| ₹2.5 lakh / ₹5 lakh interest rule | May apply to interest relating to excess employee contributions | Not applicable in the same manner |
| Withdrawal taxation | Generally exempt after the required service period, subject to conditions | Eligible withdrawals and maturity proceeds are generally exempt |
| Premature withdrawal | May become taxable if the required service condition is not satisfied and no exception applies | Governed by PPF withdrawal and premature-closure rules; eligible proceeds are generally exempt |
| ₹7.5 lakh employer contribution ceiling | Relevant where applicable employer retirement contributions are aggregated | Not applicable |
| Overall tax character | Tax-efficient, but conditional | Generally EEE in character |
PPF is generally simpler from a tax-exit perspective because its interest and eligible maturity proceeds are ordinarily exempt. EPF can also provide a tax-free retirement corpus, but the result depends on the nature of contributions, applicable interest rules and the conditions attached to withdrawal.
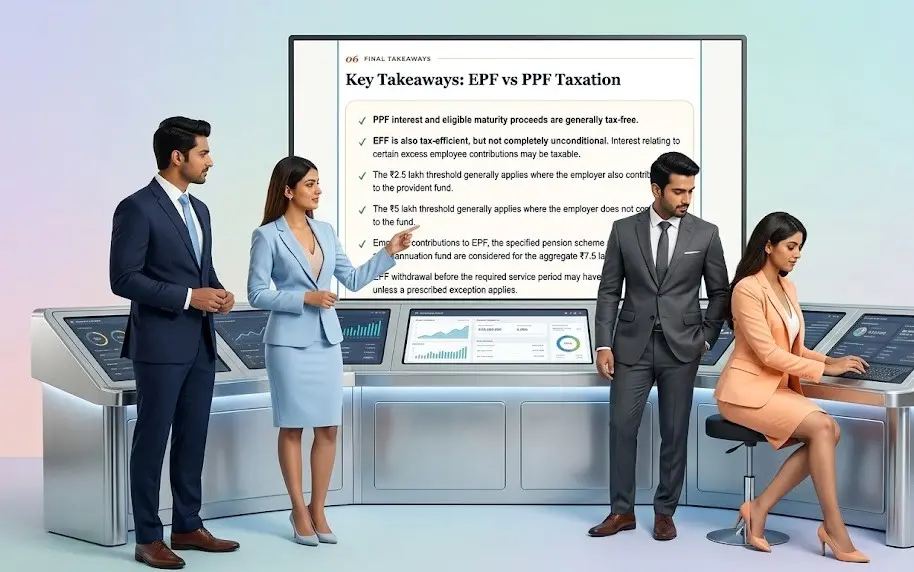
Key Takeaways: EPF vs PPF Taxation
- PPF interest and eligible maturity proceeds are generally tax-free.
- EPF is also tax-efficient, but not completely unconditional. Interest relating to certain excess employee contributions may be taxable.
- The ₹2.5 lakh threshold generally applies where the employer also contributes to the provident fund.
- The ₹5 lakh threshold generally applies where the employer does not contribute to the fund.
- Employer contributions to EPF, the specified pension scheme and an approved superannuation fund are considered for the aggregate ₹7.5 lakh ceiling.
- EPF withdrawal before the required service period may have tax consequences unless a prescribed exception applies.
- PPF is not subject to an employment-service condition because it is an individual savings account rather than an employer retirement benefit.
- Deduction on contributions depends on the applicable provisions, prescribed limits and the tax regime selected.
EPF and PPF are both powerful tax-efficient savings instruments, but their tax treatment is not identical. PPF generally offers a cleaner tax-free interest and maturity structure, while EPF provides an employment-linked retirement benefit whose exemption depends on statutory limits and withdrawal conditions.
Frequently Asked Questions
Is PPF interest completely tax-free?
Interest credited to a PPF account is generally exempt from income tax, subject to the applicable scheme and tax provisions. Unlike EPF, PPF does not have an equivalent ₹2.5 lakh or ₹5 lakh employee-contribution threshold for taxing interest.
Is EPF interest tax-free?
EPF interest is generally exempt, but interest relating to certain excess employee contributions may become taxable. The commonly applied threshold is ₹2.5 lakh where the employer also contributes and ₹5 lakh where the employer does not contribute. The taxable amount is generally the interest attributable to the excess contribution, as determined under the prescribed computation rules.
Is the EPF maturity amount tax-free?
EPF maturity or accumulated-balance withdrawal is generally exempt when the applicable service-period condition is satisfied or a prescribed exception applies. Withdrawal before the required period may have tax consequences.
Is the PPF maturity amount taxable?
Eligible PPF maturity proceeds are generally exempt from income tax. PPF is commonly treated as an EEE investment because eligible contributions, interest and maturity proceeds receive tax-exempt treatment subject to the applicable scheme conditions.
Does the ₹7.5 lakh limit apply to PPF?
No. The ₹7.5 lakh aggregate ceiling concerns specified employer contributions to recognised provident funds, the specified pension scheme and approved superannuation funds. It does not apply to an individual’s PPF contribution.
Can I claim a deduction for both EPF and PPF contributions?
Eligible EPF and PPF contributions may fall within the specified-investment deduction framework, subject to the overall statutory limit, qualifying conditions and the tax regime selected. The same contribution cannot be deducted twice.
Is EPF better than PPF from a tax perspective?
Neither is universally better. PPF generally provides a simpler tax-free interest and maturity structure. EPF, however, combines employee savings with employer contribution and is an important retirement benefit for eligible salaried employees. The better option depends on employment status, liquidity needs, contribution level and tax regime.
Does changing jobs affect the tax treatment of EPF?
Transfer of the EPF balance to the provident fund account maintained by the new employer generally helps preserve continuity of service for the applicable withdrawal exemption. An actual withdrawal before satisfying the required service condition may produce a different tax result.
Sources and References
This article is provided for general informational and educational purposes only. The tax treatment of EPF and PPF may depend on the type of provident fund, applicable statutory conditions, contribution levels, service period, withdrawal circumstances and the tax regime selected. Tax laws, rules, notifications and scheme conditions may change. Readers should verify the applicable provisions and consult a qualified chartered accountant or tax professional before taking a tax or investment decision.