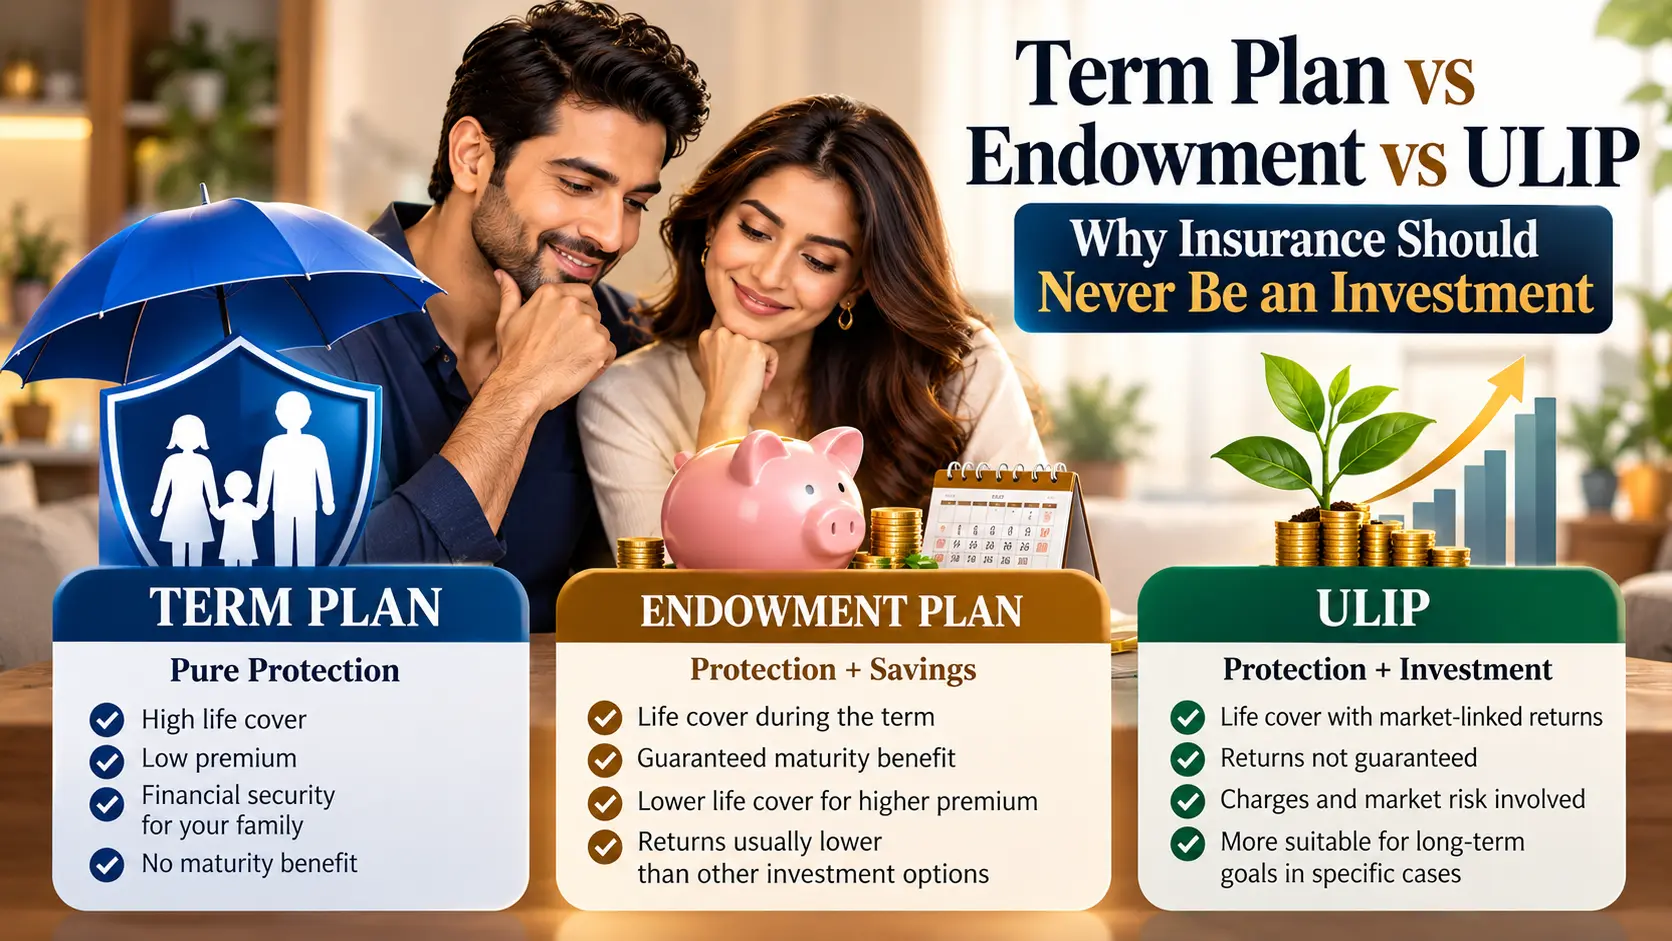
“At least I get my money back if I don’t die” is the single most expensive sentence in Indian personal finance. It’s the pitch behind endowment plans and ULIPs alike, and it’s why so many households end up paying a life-insurance premium for twenty or thirty years and finish with both weak cover and a mediocre return. This is the last piece in this series, and it exists to settle the question the other three kept circling: in a term plan vs endowment vs ULIP comparison, why does combining insurance with investment consistently cost you on both sides of that combination, instead of giving you the best of both?
- Term Plan vs Endowment vs ULIP: The Core Difference
- Why Combining Insurance and Investment Costs You Twice
- Endowment Plans, Explained Honestly
- Worked Example: Same ₹1 Lakh a Year, 20 Years, Three Ways
- The Commission Incentive Nobody Mentions
- When a Bundled Plan Might Actually Make Sense
- Complete Comparison Table
- FAQ — People Also Ask
Every insurance-linked investment product in India is sold on some version of the same reassurance: you’re not just protecting your family, you’re also building wealth, and if nothing bad happens, you get your money back with something extra on top. It sounds like a strictly better deal than “pure” term insurance, which gives you nothing at all if you survive the term. That framing is exactly backwards, and treating insurance as investment is where it goes wrong — this article exists to show why with real numbers rather than just an assertion. The short version, which the rest of this piece works through in detail: a product built to do two jobs at once — insure you and invest your money — ends up doing both jobs at a discount, because the same rupee can’t fully fund excellent protection and excellent growth simultaneously.
Term Plan vs Endowment vs ULIP: The Core Difference
All three are technically “life insurance,” but they solve completely different problems, and that’s the root of the confusion.
Pure risk cover. Your premium pays only for protection — there’s no fund, no bonus, no maturity payout. If you outlive the term, the policy simply ends, having done its job of standing by in case it was needed. Because nothing is being invested or returned, the premium is a small fraction of what the other two structures charge for the same rupee of cover.
A traditional, non-market-linked plan that combines a modest life cover with a savings component the insurer manages internally, paying out the sum assured plus accumulated bonuses on maturity (or on earlier death). The “guarantee” is really a smoothed, insurer-declared bonus rate rather than a market return, and it’s historically been a low one.
The market-linked version of the same idea: part of your premium buys a small amount of life cover, and the rest is invested in funds you can usually choose from, with a unit-linked NAV instead of an opaque bonus rate. In a straight ULIP vs endowment comparison, the ULIP is generally more transparent and offers more growth potential, but it’s still built around the same core compromise between insuring and investing.
Why Combining Insurance and Investment Costs You Twice
The mechanics are the same across both bundled products, even though the packaging differs.
- Weaker cover per rupee: Because part of every premium rupee is diverted into the savings or investment component, far less is left to fund actual mortality risk — which is why the same ₹1 lakh annual premium buys roughly ₹1 crore of term cover, but often only ₹10–15 lakh of cover in an endowment or ULIP.
- Weaker growth per rupee: The reverse cost hits the investment side. Mortality charges, insurer overheads, and (for endowment plans especially) high agent commissions are deducted before your money starts compounding — so even the invested portion grows from a smaller base and at a slower pace than a direct mutual fund or PPF contribution would.
- Illiquidity on both sides: Surrender an endowment plan in the first few years and you typically get back a fraction of what you paid in — sometimes very little in year one or two. ULIPs carry a hard 5-year lock-in, with early exits routed into a low-yield Discontinued Policy Fund. A pure term plan can simply be stopped with no such penalty, since there was never a fund to forfeit.
Endowment Plans, Explained Honestly
Endowment plans deserve a closer look because they’re older, more trusted by families who grew up watching parents and grandparents rely on them — LIC’s traditional plans being the most familiar example in India — and because endowment plan returns work on a genuinely different mechanism from a ULIP’s, not just an older wrapper around the same idea.
- Bonus-based, not market-linked: Returns come from an annually declared bonus rate (and sometimes a terminal bonus at maturity), set by the insurer based on its own investment performance and actuarial surplus — not a fund NAV you can track daily.
- Historically modest returns: Across the industry, traditional with-profit endowment plans have commonly delivered annualised returns in a roughly 4–6% range over the long term once bonuses are factored in — below what even conservative long-term debt instruments have often returned, let alone equity.
- Front-loaded costs, poor endowment plan surrender value: A large share of the first year’s premium — and a meaningful share of the next few years’ — goes toward the insurer’s expenses and agent commission before it starts working for you, which is why surrendering early can mean recovering only a small portion of what you’ve paid in.
- Tax treatment mirrors ULIPs at high premiums: Similar to ULIPs, maturity proceeds on endowment (and other traditional) policies issued after April 1, 2023 lose their Section 10(10D) tax-free status if the annual premium exceeds ₹5 lakh — a threshold worth checking against your own premium before assuming the payout will be tax-free.
Worked Example: Same ₹1 Lakh a Year, 20 Years, Three Ways
Take the same ₹1,00,000 annual budget and route it through each structure for 20 years. The point isn’t to nail an exact return — actual figures will vary by insurer, fund choice, and market conditions — it’s to see the shape of the trade-off clearly.
| Approach | Life Cover | Illustrative Maturity Value (20 yrs) |
|---|---|---|
| Term (₹15,000/yr) + Mutual Fund (₹85,000/yr, ~11% assumed) | ₹1,00,00,000 | ≈ ₹54,50,000 |
| Endowment (₹1,00,000/yr, ~5% assumed bonus rate) | ≈ ₹12,00,000 | ≈ ₹33,00,000 |
| ULIP (₹1,00,000/yr, ~9% assumed net-of-charges) | ≈ ₹10,00,000 | ≈ ₹51,00,000 |
| Fully illustrative — assumed rates of return are for explanatory purposes only, are not guaranteed, and actual outcomes depend on the specific policy, fund performance, and charges. | ||
Combining term insurance and mutual funds this way isn’t just cheaper — in this illustration it produces both the larger corpus and roughly eight to ten times the life cover of either bundled alternative, for the identical ₹1,00,000 annual outlay. That combination — better protection and better growth from the same money — is only possible because the two jobs aren’t being forced to share one product’s cost structure.
Endowment plans and ULIPs do offer something a term-plus-mutual-fund plan doesn’t: forced, structured savings. For someone who has tried and repeatedly failed to invest independently — skipping SIPs, redeeming early, never actually building the habit — a product that penalises early withdrawal can, in practice, outperform a “better” plan that never gets followed through. It’s a real behavioural argument, just not a mathematical one, and it’s worth being honest about which one applies to you before dismissing either option outright.
The Commission Incentive Nobody Mentions
Part of why bundled products get pushed so much harder across the counter than plain term insurance isn’t a mystery — it’s arithmetic on the seller’s side of the table.
The IRDAI commission rules changed in April 2023: the old fixed, product-wise commission caps were replaced with an overall “Expenses of Management” limit per insurer, giving companies more flexibility in how they structure commissions. Under the current framework, insurers can pay agents up to 100% of the first-year premium as commission on term plans with a premium-paying term over 10 years, versus up to 80% of the first-year premium on traditional plans like endowment and money-back policies. On the surface, that looks like term pays agents more — but percentages are deceptive here. 100% of a ₹15,000 term premium is ₹15,000 in an agent’s pocket. 80% of a ₹1,00,000 endowment premium is ₹80,000 — more than five times as much, from the same customer, in the same year. That gap in absolute earnings, not the percentage cap, is a large part of why bundled products get recommended so much more enthusiastically than plain term cover.
When a Bundled Plan Might Actually Make Sense
- You have a documented history of not sticking to independent investing, despite genuinely trying
- You specifically value a smoothed, less volatile payout over the higher expected but variable returns of market-linked investing
- You’re using it as a small, deliberate slice of a portfolio that’s otherwise well-diversified and adequately term-insured
- You don’t yet have adequate term cover, and a bundled plan is being sold as a substitute for it
- You’re buying it mainly because “at least I get my money back” sounds safer than pure protection
- Nobody has shown you the term-plus-separate-investment alternative side by side before you signed
Complete Comparison Table
| Parameter | 🔵 Term Plan | 🟤 Endowment | 🟠 ULIP |
|---|---|---|---|
| Cover per rupee of premium | Highest | Lowest | Low-moderate |
| Return type | None — pure protection | Insurer-declared bonus rate | Market-linked NAV |
| Typical long-term return | Not applicable | ≈ 4–6% historically | Market-dependent, net of charges |
| Lock-in | None | Effectively long-term; poor early surrender value | Mandatory 5 years |
| Transparency | High — premium is the only variable | Low — bonus rates aren’t market-tracked | High — NAV-based |
| Typical first-year agent commission cap (2023 rules) | Up to 100% of premium (small base) | Up to 80% of premium (large base) | Governed by overall insurer EOM limits |
| Best paired with | A separate mutual fund / PPF / NPS investment | Rarely the best primary choice | Rarely the best primary choice |
| Directional guide only — commission structures reflect IRDAI’s 2023 Expenses of Management framework; consult current insurer disclosures for exact figures. | |||