You own three flats. You live in one, your parents use another, and the third has been sitting empty since March. Which of them does the taxman treat as “not earning anything”, and which one gets taxed on rent nobody ever paid?
Part 1 showed how the annual value of a house is worked out. This part answers the question most home-owners actually type into Google: which of my houses counts as self-occupied, and which becomes a deemed let out property? For properties taxable under the head ‘Income from House Property’ under the Income Tax Act 2025, the practical classification is into self-occupied, let-out and deemed let-out properties, and the category decides whether its annual value is Nil, or a real number that lands in your income. The rule that separates them is short, but it is the one people get wrong most often.
Applicability note: The self-occupied rules sit in Section 21(6) and (7) of the Income Tax Act 2025 (corresponding broadly to Section 23(2) to (4) of the Income-tax Act, 1961), and apply from Tax Year 2026-27. The two-house limit has existed since 2019; Budget 2025 then relaxed the condition for treating a house as self-occupied, so older articles you find online may be out of date.
The Three Kinds of House: Self-Occupied, Let-Out and Deemed Let Out
For properties taxable under the head ‘Income from House Property’, these categories help determine how annual value is computed.
| Bucket | What it means | Annual value |
|---|---|---|
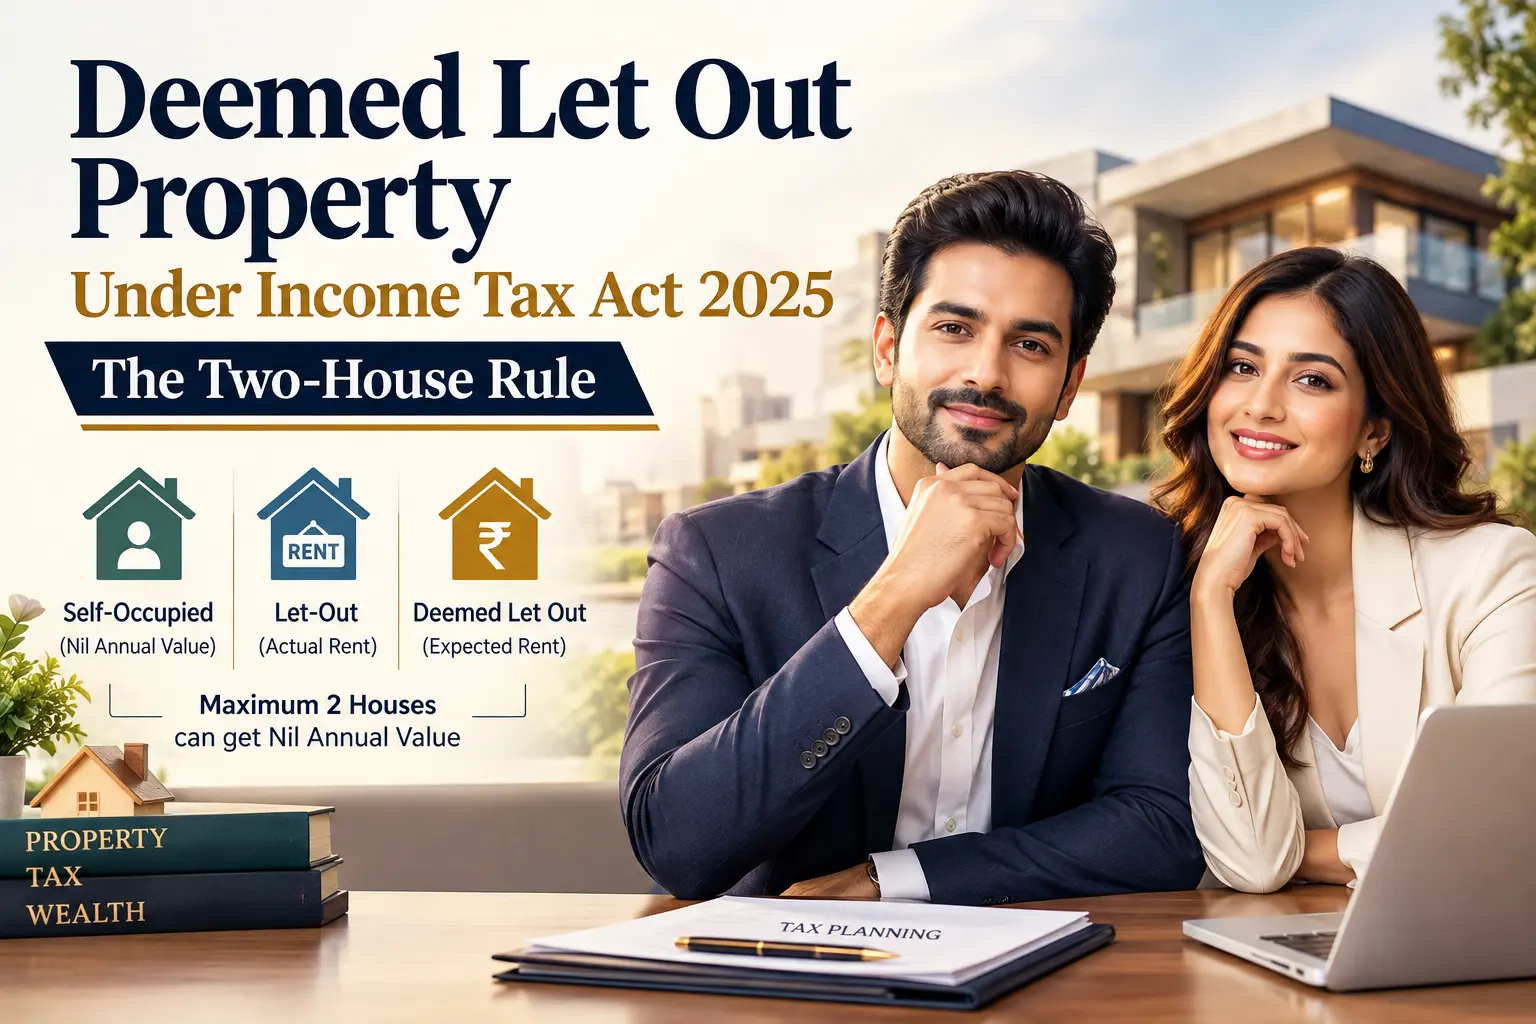
| Self-occupied | You live in it, or cannot occupy it for any reason, you have not let it out, and you derive no other benefit from it | Nil (up to two houses) |
| Let-out | You actually rented it to a tenant | Expected rent or actual rent, as covered in Part 1 |
| Deemed let out | A third or later house that you have not let out | Expected rent, taxed as if rented |
Self-Occupied / Nil Annual Value Property: When the Annual Value Is Nil (Section 23(2) of the 1961 Act)
The Act treats a “self-occupied” house, more precisely a self-occupied or Nil annual value property, as one you use as your own residence. Under the 2025 Act, the Nil treatment also applies where you cannot actually occupy it for any reason, for example because you work in another city and live in rented accommodation there. Earlier, this relief was tied to specific reasons such as employment or business elsewhere; the wording is now much wider. Section 21(7) then adds two firm conditions: the Nil value does not apply if the house, or any part of it, is actually let at any time during the Tax Year, or if you derive any other benefit from it. The Act does not list examples of an “other benefit”, so if someone uses your house in exchange for something, check the position with a Chartered Accountant.
The law speaks of “a house or any part thereof”, which means the test can apply to part of a building. If you live on one floor and rent out the other, the floor you live in is treated as self-occupied and the rented floor is taxed as let-out.
Usually Qualifies
Your own home; a house you cannot occupy because you live elsewhere for work; a house you occupy, or a house you cannot actually occupy for any reason, subject to the conditions in Section 21(7)
Does Not Qualify
A house let out at any time in the Tax Year, even for a single month, or one from which you derive any other benefit
That last point catches people out. If you let a house for even part of the year, it cannot be treated as self-occupied for that year, and it moves into the let-out computation instead. Letting out a flat for one month and then leaving it empty does not let you claim the Nil value for the rest of the year.
Two Self-Occupied Houses: The Rule and Your Choice (Section 23(4) of the 1961 Act)
Under Section 21(7)(a), the Nil value applies only to two houses, “as specified by the assessee”. If you own more, you decide which two get the relief. The law does not fix it for you. Every house beyond your chosen two is treated as deemed to be let out.
If you are a co-owner, the relief is available to each co-owner separately, as if each were the sole owner, again with a limit of two houses per person. Part 4 of this series covers co-ownership in detail.
Rakesh owns three flats, lets none of them out, and earns no rent or other benefit from any of them. The Mumbai flat, where he lives, would fetch an expected rent of ₹9,00,000 a year. The Pune flat, which his family uses, would fetch ₹6,00,000. The Goa holiday flat, which stays empty, would fetch ₹4,80,000, and he paid ₹20,000 in municipal taxes on it. He can only give Nil treatment to two of them. Since the house left over is taxed on its expected rent, as a starting point, if the properties have no significant differences in deductions or financing, leaving the house with the lowest expected annual value outside the two Nil-value houses may reduce the notional income. However, the actual tax impact should be compared after considering applicable deductions and the chosen tax regime. Making Mumbai and Pune self-occupied leaves Goa as the deemed let out flat, with an annual value of ₹4,80,000 and a Net Annual Value of ₹4,60,000 after municipal taxes. Choosing any other pair would push a higher figure, ₹6,00,000 or ₹9,00,000, into his income. A home loan on any of the flats can change this arithmetic, which is why Part 3 looks at interest deductions.
Deemed Let Out Property: How It Is Taxed
“Deemed let out property” is the label practitioners use for a house that falls outside your two Nil-value houses. The Act itself does not use that phrase. What it does is limit the Nil value in Section 21(6) to two specified houses, so every other house goes through the ordinary annual value rule in Section 21(1), as if it could be let. Because there is no actual rent, the annual value is simply the expected rent: the higher of municipal value and fair rent, capped at standard rent where rent control applies, exactly as explained in Part 1. From there, you subtract the municipal taxes you actually paid to reach the Net Annual Value, and then the usual house property deductions apply. Those deductions are the subject of Part 3.
The vacancy relief you saw in Part 1 does not help here. Section 21(2) applies only where a property or part of it “is let” and stood vacant. A deemed let out property was never let out at all, so its annual value is the expected rent, full stop.
Choosing Your Two Houses: The Tax Regime Twist
Which two houses to pick is not only about expected rent. Your choice of tax regime can change the outcome. Under the tax regime governed by Section 202, the computation does not allow the deduction under Section 22(1)(b) for properties covered by Section 21(6), and a loss under the head ‘Income from House Property’ cannot be set off against income under another head.
In plain words, if you have chosen the new tax regime, interest on a self-occupied house gets you no deduction, and a house property loss cannot be used to reduce your salary or other income. Under the old regime, the picture is different. Part 3 works through the numbers, so if you have a running home loan, read that part before you finalise which two houses to call self-occupied.
- Believing only one house can be self-occupied — that was the position before 2019. It is now two
- Treating a house as self-occupied after letting it for a month — any letting during the year takes it out of the Nil category for that year
- Overlooking the “other benefit” condition — Section 21(7)(b) denies the Nil value if you derive any benefit from the house, not only rent
- Assuming an empty third house has no tax effect — it is a deemed let out property, taxed on expected rent whether or not anyone pays you
- Expecting vacancy relief on a deemed let out property — vacancy relief is for houses that were actually let out, not for houses you simply left empty
- Picking your two houses at random — the house you leave out of the Nil category is the one that adds income, so the choice deserves a quick calculation
Frequently Asked Questions
How many houses can be self-occupied under the Income Tax Act 2025?
Up to two. Each of the two houses you choose gets a Nil annual value. Every house beyond those two is treated as a deemed let out property and taxed on its expected rent, even if it is empty.
What is a deemed let out property?
It is the label used for a house that is taxed as if it were rented out, even though you did not rent it. In practice, it is a third or later house that you own but have not let out. Its annual value is the expected rent, and you pay tax on that notional figure.
Can I choose which two houses are self-occupied?
Yes. If you own more than two houses, you decide which two get the Nil treatment. The house you leave outside that choice becomes the deemed let out property, so it usually makes sense to compare the tax on each combination.
What if I let out a self-occupied house for one month?
A house that is let out at any time during the Tax Year cannot be treated as self-occupied for that year. The same applies if you derive any other benefit from the house. It moves into the ordinary annual value computation, and the Nil value is not available for it.
Can a house where my parents live rent-free count as self-occupied?
Whether such a property qualifies depends on the facts. Section 21(6) provides Nil annual value where the owner occupies the property for his own residence or cannot actually occupy it for any reason. The provision should therefore not be read as automatically granting Nil annual value merely because a family member occupies the house rent-free. Where the facts involve family occupation, the position should be verified before filing the return.
Does each co-owner get the two-house benefit?
Yes. Where a house is co-owned, the Nil-value relief is available to each co-owner separately, as if each were the sole owner, subject to the limit of two houses per person.
Income From House Property — Series Index
Chargeability & Annual Value: How House Property Income Is Computed
The Section 20/21 framework this article builds on.
Deemed Let Out Property: The Two-House Rule
Which houses get a Nil value, and which are taxed on notional rent.
If you remember one line from this article, make it this: two houses can be Nil-valued, and everything after that is taxed on what it could earn, not on what it actually earns. If you own three or more properties, work out the tax on each possible pair before you file, and do not treat any house as “free” if you let it out even briefly.
Sources & References
- Income-tax Act, 2025 [Act No. 30 of 2025] — full text, as amended by Finance Act, 2026Income Tax India, incometaxindia.gov.in
- Section 202 — New Tax Regime for Individuals, HUF and OthersIncome Tax India, incometaxindia.gov.in
Sections 21(6) and 21(7) are summarised here for reader convenience. Always cross-check against the official Act text linked above and consult a Chartered Accountant before relying on this for a filing decision.
Disclaimer: This article is for general informational purposes only and does not constitute tax or legal advice. The Income-tax Act, 2025 and related rules are subject to notifications and amendments by the CBDT. Please consult a qualified Chartered Accountant for advice specific to your situation.