Case at a glance
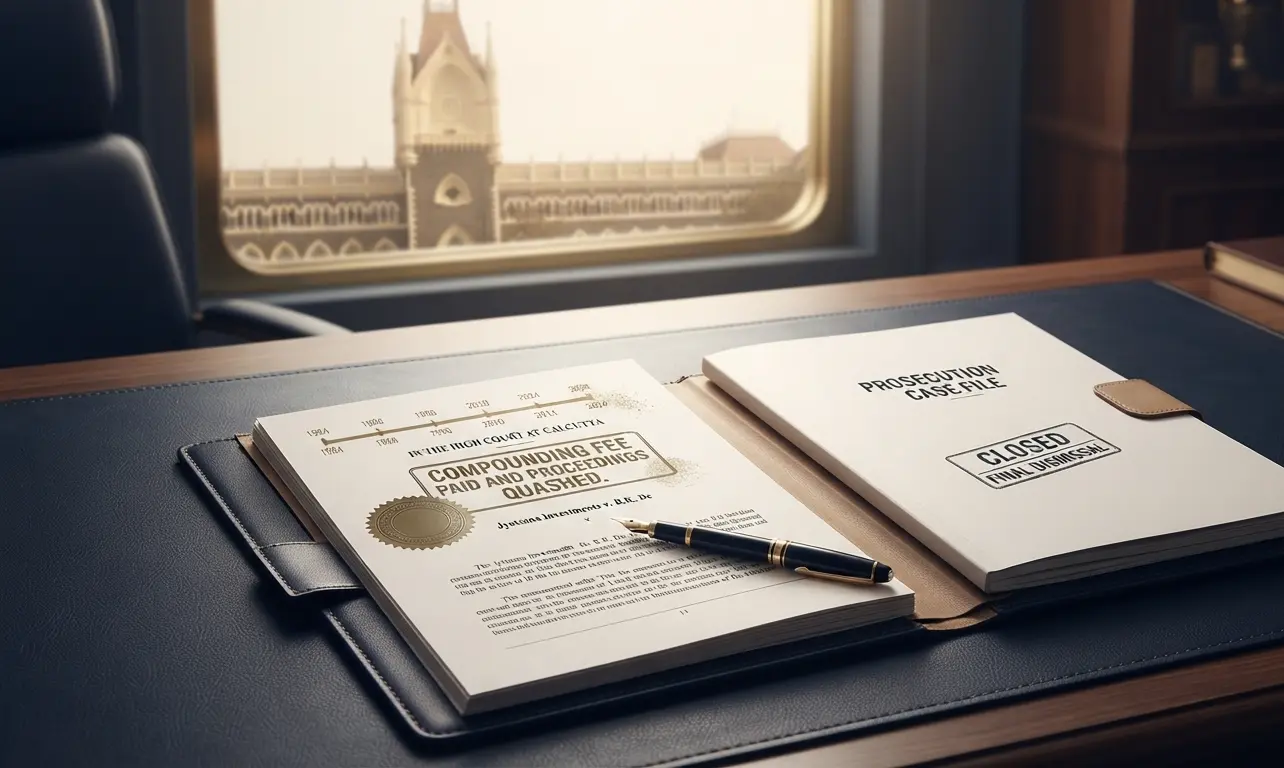
Case Name: Jyotsana Investments Co. Ltd. v. R.K. De
- Subject
- Prosecution quashed after compounding fee paid and a 40-year delay
- Issue
- Can a tax prosecution stayed in 1988 be revived decades later, after the Revenue has accepted the compounding fee and recovered the tax and interest?
- Citation
- (2026) 349 CTR 406; 183 taxmann.com 293 (Cal)
- Court
- Calcutta High Court
- Assessment year
- 1983-84
- Provisions
- Sections 276B(ii) and 278B, Income-tax Act 1961; Article 21, Constitution of India
- Outcome
- In favour of assessee
Background
Facts of the Case
- After a search in 1983, about 54 criminal cases were filed in 1986 against the company and its directors under Sections 276B(ii) and 278B.
- In 1988, the High Court stayed the proceedings pending disposal of the company’s compounding application.
- The company paid the compounding fee in 2001, and later paid interest in 2017.
- In 2015, the trial court revived the matter and issued arrest warrants and property attachment orders, including against accused who had died.
- The company challenged the proceedings in the High Court. Despite several opportunities, the Department did not appear to contest the case.
The ruling
Summary of Decision: What the High Court Held
- Keeping a prosecution alive for forty years is a clear violation of the right to a speedy trial, a fundamental right under Article 21 of the Constitution.
- In fiscal offences, once the exchequer has recovered the tax, interest and compounding fee, the public interest in continuing the prosecution ends.
- Trying to revive such a trial, especially against accused who have died, is a gross abuse of the process of law.
- When the Revenue accepts a statutory compounding fee while the stayed proceedings are pending, the offence is settled. The prosecution was therefore quashed after the compounding fee had been accepted.
Practice point
Key Takeaway on Prosecution Quashed After Compounding Fee
- Once the Revenue accepts the compounding fee, the offence is settled and the prosecution cannot be revived later.
- Long, unexplained delay in a tax prosecution is an independent ground to seek quashing under Article 21.
- Proceedings revived against accused who have died should be challenged immediately as an abuse of process.
- Keep proof of payment of the compounding fee, tax and interest on file. It is the foundation of this defence.
Keep reading