Case at a glance
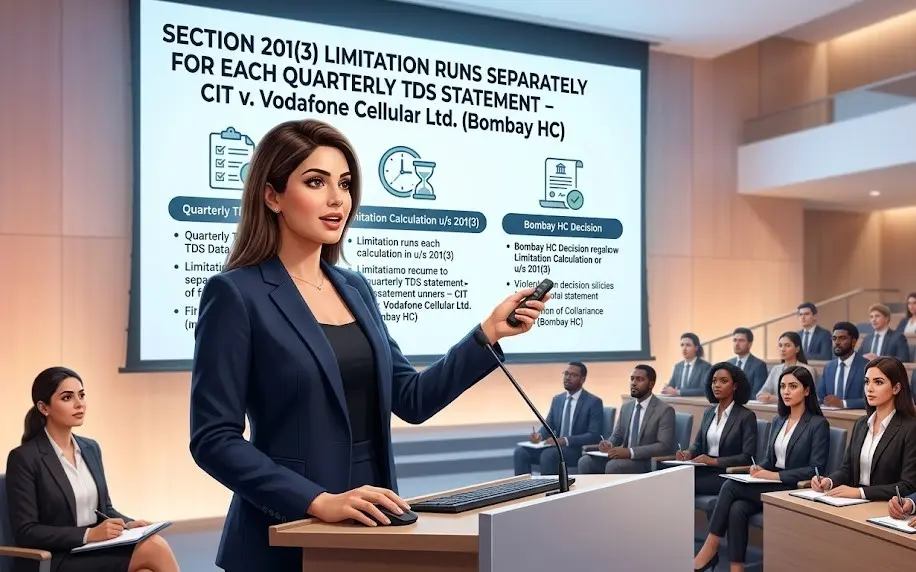
Case Name: CIT v. Vodafone Cellular Ltd.
- Subject
- Section 201(3) limitation for TDS default orders when statements are filed quarterly
- Issue
- Does the limitation period under Section 201(3) run separately for each quarterly TDS statement, or once for the whole year?
- Citation
- (2026) 349 CTR 783 (Bom)
- Court
- Bombay High Court
- Assessment year
- 2009-10
- Provisions
- Sections 200 and 201(3), Income-tax Act 1961; Rule 31A, Income-tax Rules 1962
- Outcome
- Partly in favour of assessee
Background
Facts of the Case
- The assessee filed its first three quarterly TDS statements for the year during financial year 2008-09.
- The fourth-quarter statement was filed in financial year 2009-10.
- An order under Section 201 covering all four quarters was passed on 15 June 2012.
- The dispute was whether the order was within the time limit under Section 201(3) for each of the quarters.
The ruling
Summary of Decision: What the High Court Held
- TDS statements must be filed quarterly under Rule 31A, so each quarterly filing is a separate compliance period with its own starting point for Section 201(3) limitation.
- For the first three quarters, the order was passed more than two years after the end of the financial year in which those statements were filed, so it was barred by limitation.
- The fourth-quarter statement was filed in financial year 2009-10, and the order for that quarter was within the prescribed period. The demand for the fourth quarter was sustained.
Practice point
Key Takeaway on Section 201(3) Limitation
- Limitation for a TDS default order is counted separately for each quarterly statement, not once for the whole year.
- An order covering the full year can be time-barred for earlier quarters even if it is valid for later ones.
- When challenging a TDS default order, check each quarter’s filing date and test limitation quarter by quarter.
- Keep the filing acknowledgement for every quarterly statement. It is the evidence that starts the clock.
Keep reading