Case at a glance
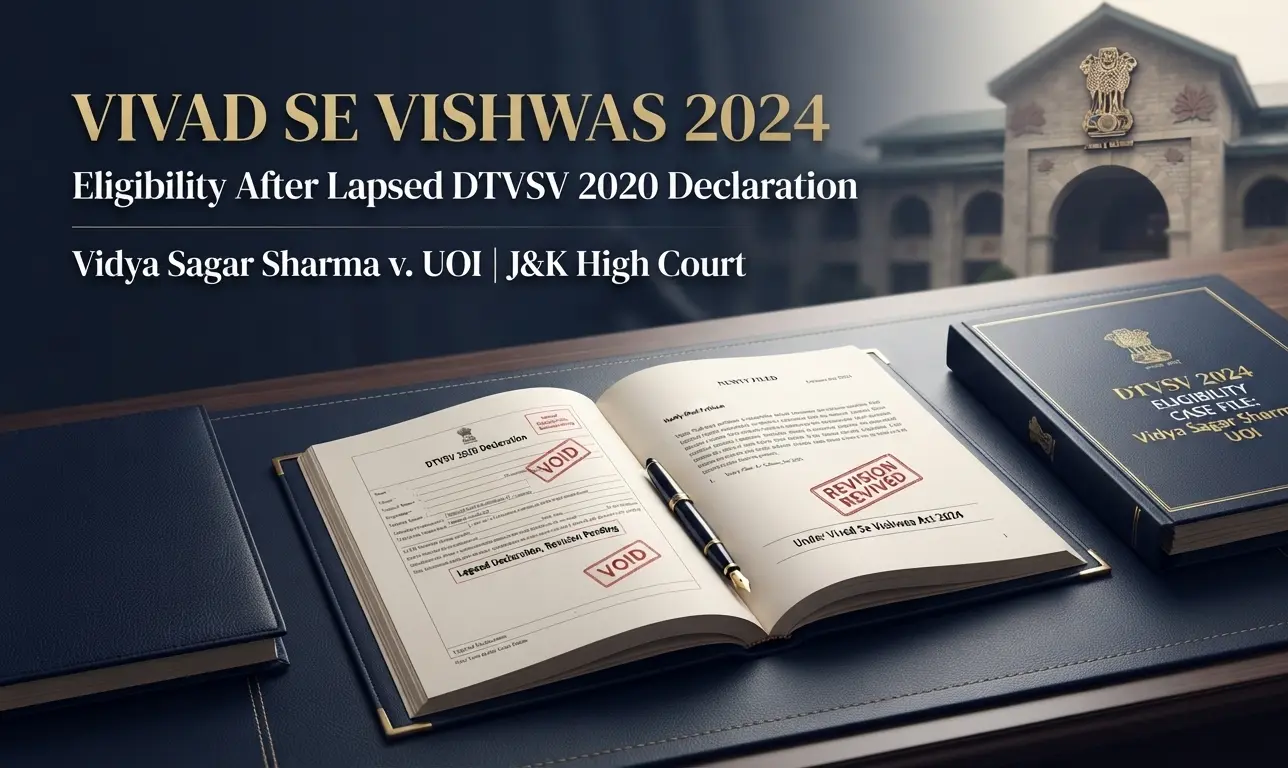
Case Name: Vidya Sagar Sharma v. UOI
- Subject
- Vivad Se Vishwas 2024 eligibility after a lapsed DTVSV 2020 declaration
- Issue
- If a DTVSV 2020 declaration becomes void for non‑payment, is the withdrawn revision petition treated as pending, so the assessee can apply under VSV 2024?
- Citation
- (2026) 349 CTR 121; 184 taxmann.com 44 (J&K)
- Court
- High Court of Jammu & Kashmir and Ladakh (writ)
- Provisions
- Section 4(6), DTVSV Act 2020; DTVSV Scheme 2024; Sections 144 and 271(1)(c), Income-tax Act 1961
- Outcome
- In favour of assessee
Background
Facts of the Case
- The AO passed a best-judgment assessment under Section 144 and levied penalty under Section 271(1)(c).
- The assessee filed revision petitions against both orders.
- He then opted for DTVSV 2020 and withdrew the petitions, but did not pay the amount in Form 3, so Form 4 was never filed and the declaration became void.
- His later VSV 2024 application was rejected by the AO on the ground that no revision was pending on the cut-off date.
The ruling
Summary of Decision: What the High Court Held
- Under Section 4(6) of the DTVSV Act 2020, once the assessee failed to pay within the stipulated time, the revision petitions revived automatically, by operation of law.
- Both sides were restored to their position before the declaration, so the petitions were pending on the cut-off date. The assessee had therefore rightly applied, and his Vivad Se Vishwas 2024 eligibility remained intact.
- The assessee was given 30 days to approach the AO to complete the 2024 scheme formalities for both tax arrears and penalty, and the AO must allow him to do so within that period.
Practice point
Key Takeaway on Vivad Se Vishwas 2024 Eligibility
- A lapsed DTVSV 2020 declaration does not bar a VSV 2024 application.
- Proceedings withdrawn under the 2020 scheme revive automatically if the declarant fails to pay.
- If a VSV 2024 application was rejected as “nothing pending”, this ruling supports a challenge.
- It helps only where the 2020 settlement was never completed (no Form 4 filed).
- Relief covers both tax arrears and penalty, so claim both.
Keep reading