Case at a glance
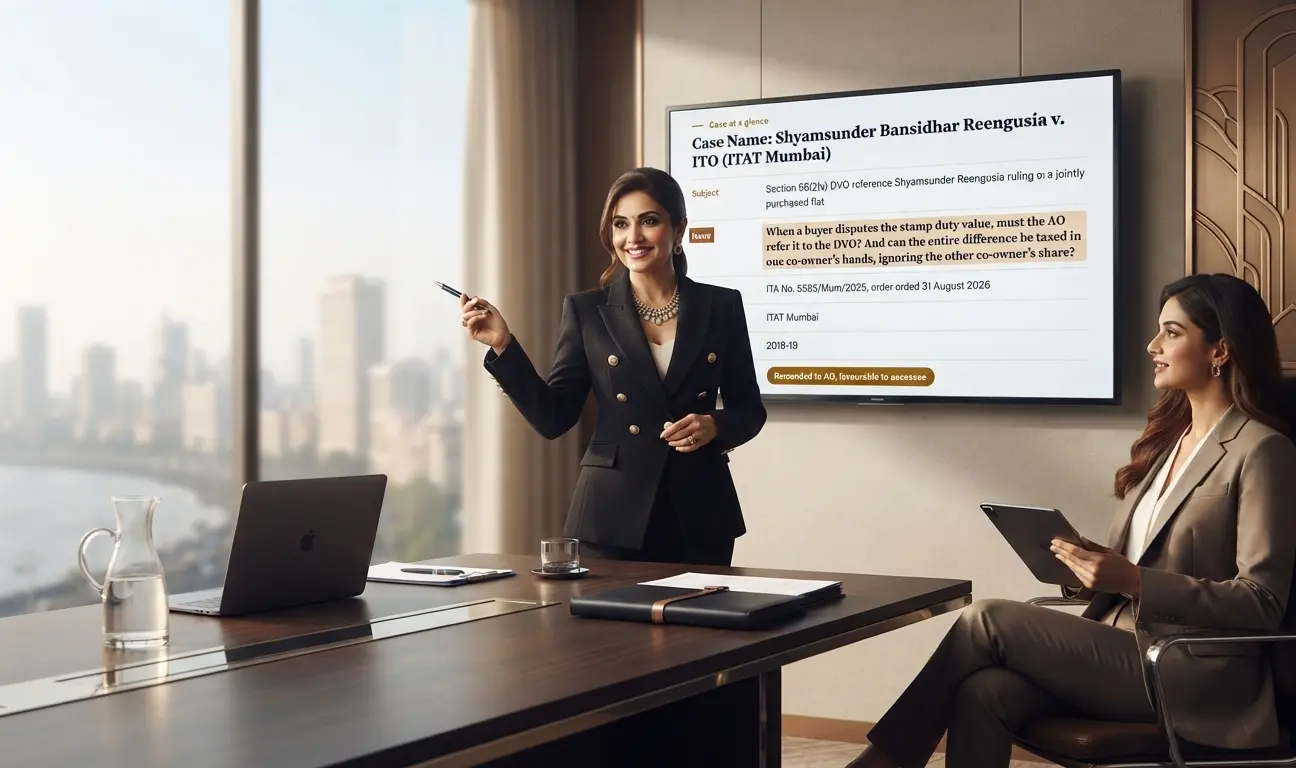
Case Name: Shyamsunder Bansidhar Reengusia v. ITO (ITAT Mumbai)
- Subject
- Section 56(2)(x) DVO reference Shyamsunder Reengusia ruling on a jointly purchased flat
- Issue
- When a buyer disputes the stamp duty value, must the AO refer it to the DVO? And can the entire difference be taxed in one co‑owner’s hands, ignoring the other co‑owner’s share?
- Appeal no.
- ITA No. 5585/Mum/2025, order dated 31 August 2026
- Forum
- ITAT Mumbai
- Assessment year
- 2018-19
- Amount involved
- Rs 34,81,500 (stamp duty value Rs 94,81,500 less price Rs 60,00,002)
- Outcome
- Remanded to AO, favourable to assessee
Background
Facts of the Case
- The assessee and his wife jointly bought a flat for Rs 60,00,002. Its stamp duty value was Rs 94,81,500, a difference of Rs 34,81,500.
- The assessee held a 41.08% share and his wife 58.92%.
- The assessee disputed the stamp duty value, filed a valuation report and specifically asked for a reference to the Departmental Valuation Officer (DVO). The authorities did not consider the request.
- The entire difference was added in the assessee’s hands, on the ground that his wife’s case had escaped scrutiny. The CIT(A) upheld this.
The ruling
Summary of Decision: What the Tribunal Held
- Once the assessee specifically disputed the stamp duty value and furnished a valuation report, the AO should have referred the valuation to the DVO before working out the taxable difference.
- There was no justification for taxing the entire difference in the assessee’s hands merely because no action was taken against his wife. The specific shares in the jointly held flat could not be ignored.
- The CIT(A)’s order was set aside and the matter sent back to the AO to determine the value through a DVO reference, after giving the assessee a reasonable hearing.
Practice point
Key Takeaway: Section 56(2)(x) DVO Reference Shyamsunder Reengusia Ruling
- If you dispute the stamp duty value, say so in writing, file a valuation report and ask for a DVO reference. That request is what made the difference here.
- For jointly bought property, only your share of the difference can be taxed in your hands. A co-owner’s case escaping scrutiny is no reason to tax you on their share.
- On the AO’s own figures, the assessee’s 41.08% share of the difference works out to about Rs 14.30 lakh, not Rs 34.82 lakh. The final figure now depends on the DVO’s valuation.
- This is a remand, not a deletion, and an ITAT order is persuasive, not binding outside the bench.
Keep reading