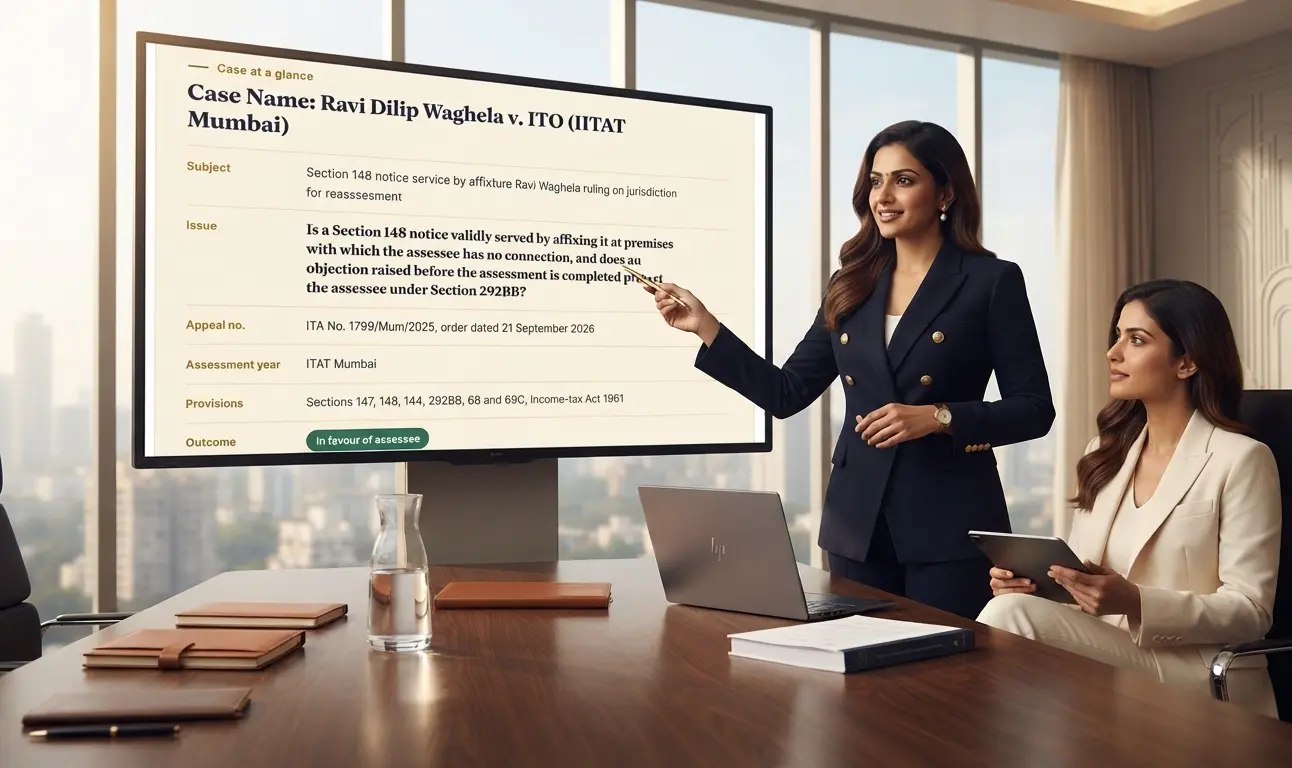
Case at a glance
Case Name: Ravi Dilip Waghela v. ITO (ITAT Mumbai)
- Subject
- Section 148 notice service by affixture Ravi Waghela ruling on jurisdiction for reassessment
- Issue
- Is a Section 148 notice validly served by affixing it at premises with which the assessee has no connection, and does an objection raised before the assessment is completed protect the assessee under Section 292BB?
- Appeal no.
- ITA No. 1799/Mum/2025, order dated 21 September 2026
- Forum
- ITAT Mumbai
- Assessment year
- 2012-13
- Provisions
- Sections 147, 148, 144, 292BB, 68 and 69C, Income-tax Act 1961
- Outcome
- In favour of assessee
Background
Facts of the Case
- A Section 148 notice dated 27 March 2019 was sent to the assessee’s Bandra address and remained unserved.
- The notice was then affixed on a locked room at Sonam Apartment, Bhiwandi. Nothing showed the assessee lived or did business there, and the Department’s own record indicated he did not reside there.
- Only after the correct Vile Parle address and email were traced was a final show-cause notice dated 22 November 2019 actually delivered. The assessee replied at once, objecting to the disputed PAN and the earlier proceedings.
- The AO completed a best-judgment reassessment under Sections 144 and 147, adding Rs 1,27,62,500 under Section 69C and Rs 18,85,000 under Section 68.
The ruling
Summary of Decision: What the Tribunal Held
- Affixing the notice at premises with no connection to the assessee is not valid service of a Section 148 notice.
- The assessee objected before the assessment was completed, so the proviso to Section 292BB applied. He could not be treated as having accepted the defective service.
- Without valid service of the jurisdictional Section 148 notice, the AO could not assume jurisdiction to reassess under Section 147.
- The reassessment under Sections 144 and 147 was quashed, and the additions under Sections 69C and 68 fell with it.
Practice point
Key Takeaway: Section 148 Notice Service by Affixture Ravi Waghela Ruling
- Service by affixture is valid only at a place connected with the assessee, such as where he lives or does business.
- Object to defective service in writing before the assessment is completed. That objection is what keeps the defence open under the Section 292BB proviso.
- Check the Department’s own records for the addresses it held. Here they showed the assessee did not live at the affixture address.
- If the jurisdictional notice fails, every addition in the reassessment falls with it, whatever its merits.
- This is an ITAT order, so it is persuasive, not binding outside the bench.
Keep reading