Case at a glance
Case Name: ACIT v. Sheth Developers Pvt. Ltd. (ITAT Mumbai)
- Subject
- Form 10-IC late filing Sheth Developers ruling on the Section 115BAA concessional tax regime
- Issue
- Can a company be denied the Section 115BAA concessional tax regime only because it filed Form 10‑IC after the due date for filing its return?
- Appeal no.
- ITA No. 6204/Mum/2025, order dated 24 August 2026
- Forum
- ITAT Mumbai (Revenue’s appeal)
- Assessment year
- 2020-21
- Provisions
- Section 115BAA, Income-tax Act 1961; Rule 21AE and Form 10-IC, Income-tax Rules 1962
- Outcome
- Remanded to AO, favourable to assessee
Background
Facts of the Case
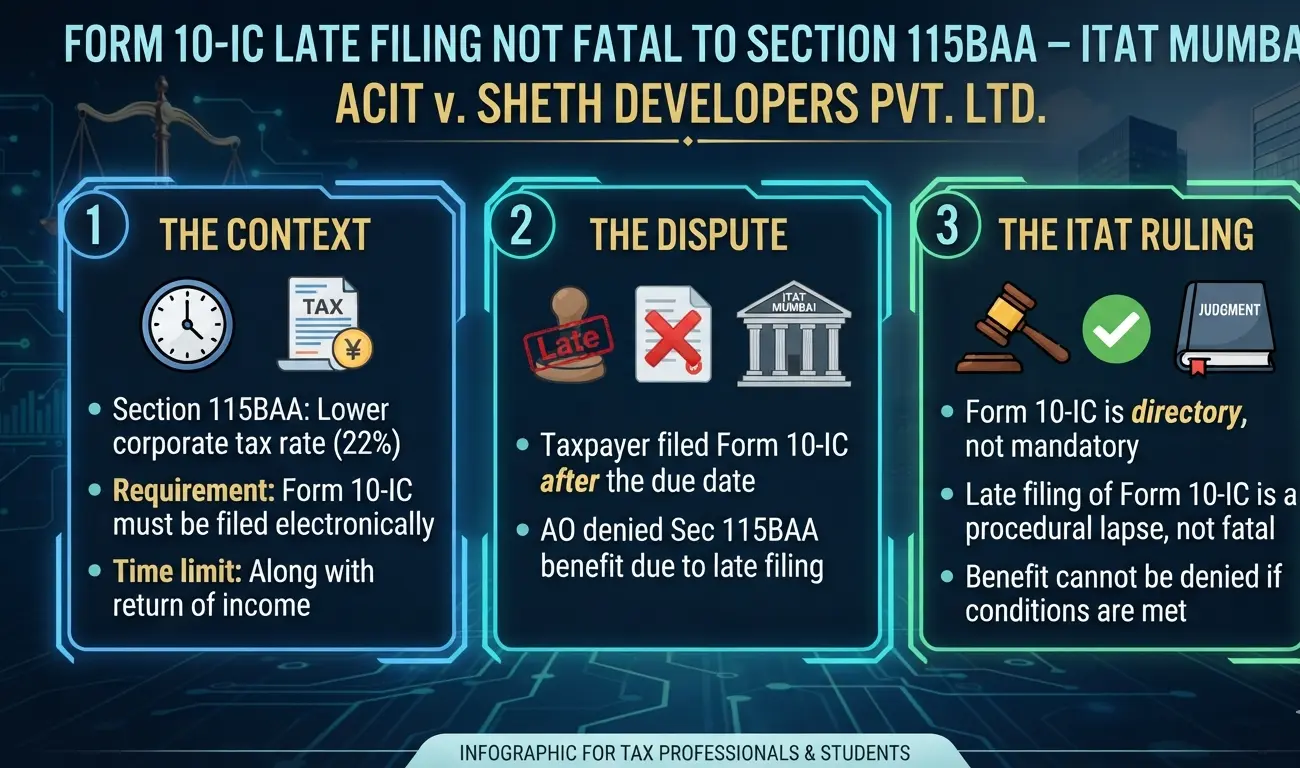
- The assessee company claimed the concessional tax regime under Section 115BAA for AY 2020-21.
- It filed Form 10-IC, the option form for the regime, but only after the due date for filing the return of income.
- The benefit was allowed at the first appellate stage, and the Revenue appealed to the Tribunal, arguing that the form had not been filed within the prescribed time.
The ruling
Summary of Decision: What the Tribunal Held
- Where Form 10-IC has in fact been filed, filing it late can be treated as a procedural lapse. Form 10-IC late filing does not, by itself, disentitle the assessee from the Section 115BAA benefit.
- In the interest of justice, the matter was sent back to the AO to verify the facts, ensure compliance with Rule 21AE, and check whether the other conditions of the regime were met.
- After that verification, the AO was directed to allow the benefit in accordance with law. The Revenue’s ground was allowed for statistical purposes.
Practice point
Key Takeaway: Form 10-IC Late Filing Sheth Developers Ruling
- A delayed Form 10-IC is not automatically fatal to Section 115BAA, as long as the form was actually filed.
- This is a remand, not a final allowance. The other conditions of Section 115BAA and Rule 21AE must still be shown to be met before the AO.
- Keep the Form 10-IC acknowledgement and evidence of meeting the regime’s conditions ready for verification.
- This is an ITAT order, so it is persuasive, not binding outside the bench. Check for High Court rulings on the point before relying on it.
Keep reading