A search on a third party turned up an Excel sheet of cash payments — and the tax department used it to reopen two years of assessments against a company that received none of the payments on record for those years. Every entry in the seized sheet was dated between 2012 and 2018. The years actually reopened were AY 2020-21 and AY 2021-22. ITAT Delhi has now confirmed that this gap is fatal: Section 148 reopening based on search material requires the material to actually say something about the year being reopened — not just mention the taxpayer’s name somewhere in a search conducted on someone else.
Quick Answer
Can a tax department reopen an assessment under Section 148 using documents seized in a search on a different company?Yes, in principle, under Explanation 2(iv) to Section 148 — but ITAT Delhi has confirmed that the seized material must actually pertain to escapement of income for the specific assessment year being reopened. If the seized documents relate only to earlier, unconnected years, the reopening for a different year is not validly triggered, even though the search itself concerned the same taxpayer.
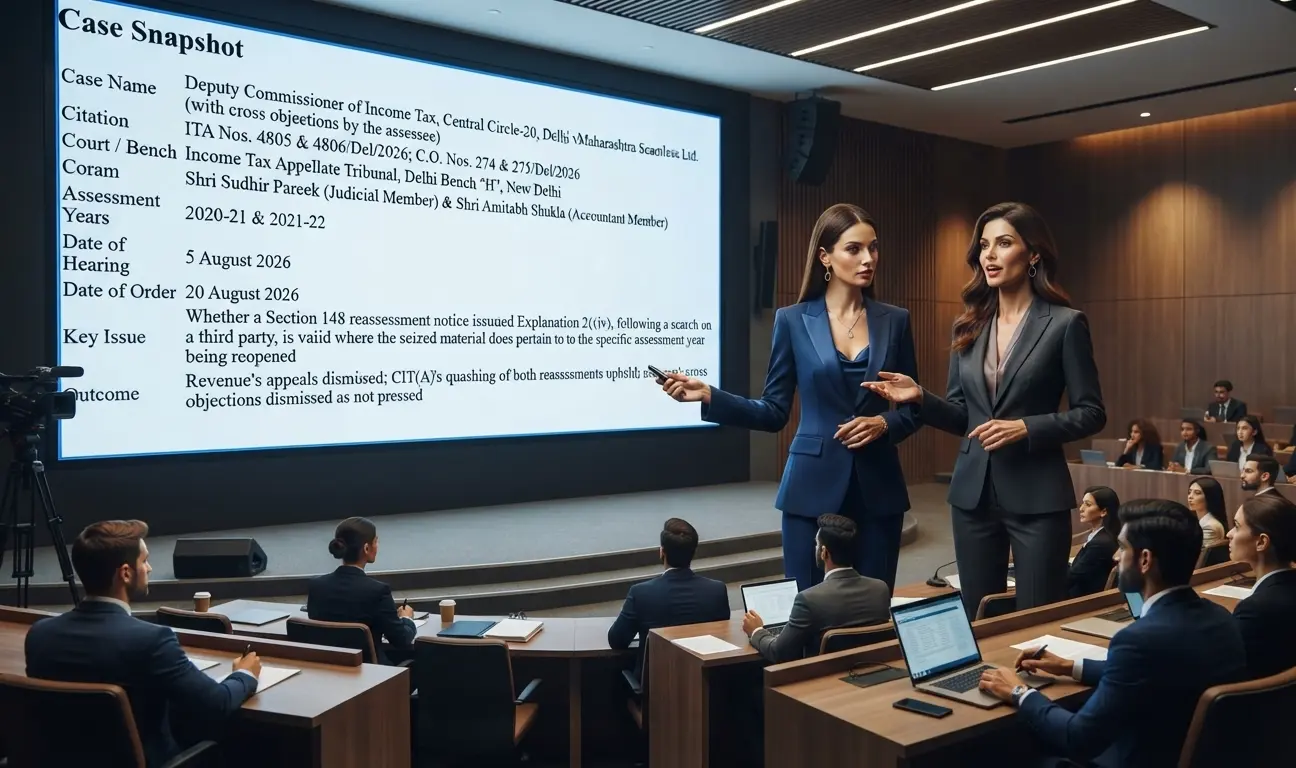
Case Snapshot
| Case Name | Deputy Commissioner of Income Tax, Central Circle-20, Delhi v. Maharashtra Seamless Ltd. (with cross objections by the assessee) |
| Citation | ITA Nos. 4805 & 4806/Del/2026; C.O. Nos. 274 & 275/Del/2026 |
| Court / Bench | Income Tax Appellate Tribunal, Delhi Bench “H”, New Delhi |
| Coram | Shri Sudhir Pareek (Judicial Member) & Shri Amitabh Shukla (Accountant Member) |
| Assessment Years | 2020-21 & 2021-22 |
| Date of Hearing | 5 August 2026 |
| Date of Order | 20 August 2026 |
| Key Issue | Whether a Section 148 reassessment notice issued under Explanation 2(iv), following a search on a third party, is valid where the seized material does not pertain to the specific assessment year being reopened |
| Outcome | Revenue’s appeals dismissed; CIT(A)’s quashing of both reassessments upheld; assessee’s cross objections dismissed as not pressed |
Table of Contents
Legal Issue: Section 148 Reopening Based on Search Material
Explanation 2(iv) to Section 148 deems an Assessing Officer to have “information” suggesting that income has escaped assessment where, pursuant to a search conducted on another person under Section 132 on or after 1 April 2021, documents seized are found to pertain or relate to the assessee. Because the search in this case was conducted after 1 April 2021, the Section 153C search-assessment machinery was unavailable — Section 153C(3) bars that provision from applying to searches on or after that date, leaving reassessment under Sections 147/148 as the only available route. The dispute was whether this deeming fiction applies simply because some documents relating to the assessee were found in the search, or whether the seized material must itself evidence escapement of income specific to the assessment year actually being reopened.
Facts of the Case
A search and seizure action was carried out on M/s Proform Interiors Pvt. Ltd. (referred to in parts of the order as “Proforma Interiors”) — a party unconnected to the assessee — on 9 February 2022. Based on an Excel sheet of alleged cash payments found during that search, the AO issued notices under Section 148 to Maharashtra Seamless Ltd. on 31 March 2023 for AY 2020-21 and AY 2021-22, invoking Explanation 2(iv). Assessment orders under Section 147 read with Section 143(3) followed on 31 March 2024, including an education cess disallowance of Rs.3,20,41,541 (AY 2020-21 only), Section 14A/Rule 8D disallowances of Rs.11,41,49,920 (AY 2020-21) and Rs.8,39,17,530 (AY 2021-22), and an estimated addition of 2% of total purchases treated as unverifiable — Rs.31,17,58,000 (AY 2020-21, on purchases of Rs.1,558.79 crore) and Rs.28,54,01,300 (AY 2021-22, on purchases of Rs.1,427.0065 crore).
On appeal, the CIT(A)-27, Delhi (order dated 23 January 2026) quashed both the Section 148 notices and the consequent Section 147 assessments. Examining the seized material as reproduced in the Assessment Order itself, the CIT(A) found that every cash-payment entry was dated between 17 December 2012 and 11 October 2018 — relevant to AY 2013-14 through AY 2019-20 — with no entry at all relating to AY 2020-21 or AY 2021-22, the years actually reopened. Applying Explanation 2(iv) as retrospectively amended by the Finance Act 2022 (correcting a drafting anomaly in the original Finance Act 2021 version, per CBDT Circular No.23/2022, para 31.3), the CIT(A) held that no incriminating material implicated the assessee for the years under consideration, and the reopening could not be sustained.
The Revenue appealed to the Tribunal against both years. The assessee had also filed detailed cross objections (C.O. Nos. 274 and 275/Del/2026) raising roughly nineteen further grounds — challenging the authority of the Joint Commissioner of Income Tax (OSD) to pass the order, the absence of a valid transfer order under Section 127, missing statutory approvals under Sections 148B and 151, alleged change of opinion, and the quantum additions themselves — but the assessee’s counsel did not press these cross objections at the hearing, and they were dismissed on that basis alone, without being argued or decided on their merits.
Arguments of the Parties
For the Revenue (DR: Sh. Bhopal Singh, CIT-DR)
- The CIT(A) erred by misapplying para 31.3 of CBDT Circular No.23/2022 and ignoring the express statutory provisions of the Act.
- Under Explanation 2(iv) to Section 148, the AO is deemed to have information suggesting escapement of income once satisfied that documents seized during the search pertain or relate to the assessee — the CIT(A) wrongly required the material to itself evidence escapement for the specific year.
- The notice was validly issued within three years from the end of the relevant assessment year under Section 149(1)(a); for notices issued within that three-year window, no minimum threshold of escaped income is required.
For the Assessee (AR: Sh. Ved Jain, Adv. & Sh. Ayush Garg, CA)
- The search on the third party yielded an Excel sheet of cash payments, but no entry in that sheet is relevant to AY 2020-21 or AY 2021-22 — the AO’s own satisfaction note tabulates these payments, all dated between 2012 and 2018.
- Since the seized material contains no transaction relating to the assessee for either year actually reopened, the CIT(A) correctly quashed the reassessment.
- It is a settled principle that where no addition is made on the very ground for which the assessment was reopened, no addition can be sustained on other, unrelated issues.
- The cross objections raising further jurisdictional and merits challenges were not pressed at the hearing.
Court/Tribunal’s Decision
The Tribunal dismissed both of the Revenue’s appeals and dismissed the assessee’s cross objections as not pressed, upholding the CIT(A)’s quashing of the Section 148 notices and the consequent Section 147 reassessment orders for both AY 2020-21 and AY 2021-22.
Reasoning Behind the Decision
The Tribunal’s own reasoning is brief: having heard the parties and reviewed the material, it held that the CIT(A)’s order was “reasonable” and “self explanatory,” with its detailed findings already set out, and that no interference was warranted. In substance, the Tribunal adopted and endorsed the CIT(A)’s factual finding — supported by the AO’s own tabulation of the seized cash-payment data — that no incriminating material existed for either AY 2020-21 or AY 2021-22, and that the retrospectively amended Explanation 2(iv) to Section 148 could not be stretched to justify reopening those years on the strength of documents relating only to earlier, unconnected years.
Key Legal Principle
Explanation 2(iv) to Section 148 — even as retrospectively validated by the Finance Act 2022 and explained in CBDT Circular No.23/2022 — requires that the seized material from a third-party search actually pertain or relate to escapement of income for the specific assessment year being reopened. The deeming fiction of “information” is not triggered merely because some documents concerning the assessee were found somewhere in the search; if those documents relate only to different, unconnected years, Explanation 2(iv) cannot be used to reopen a year for which no such material exists.
Practical Implications for Practitioners
- Always map the seized material’s own dates against the specific year being reopened: A mismatch — as here, material from 2012-2018 used to justify reopening AY 2020-21/2021-22 — can be fatal to the reopening on its own, independent of any broader jurisdictional challenge.
- “No addition on the ground for reopening, no addition on unrelated grounds” remains a useful fallback: Even where other defences are weaker, this settled principle can dispose of a reassessment where the department’s own stated basis for reopening doesn’t survive scrutiny.
- Don’t treat this order as deciding the nineteen cross-objection grounds: None of the jurisdictional and merits challenges raised in the cross objections — the JCIT(OSD)’s authority, the Section 127 transfer order, Sections 148B/151 approvals, change of opinion, or the specific quantum additions — were actually argued or decided. This order sets no precedent on any of them.
- Know which regime applies to a third-party search before building a defence: A search conducted after 1 April 2021 on someone other than the taxpayer routes into Section 147/148 reassessment via Explanation 2(iv), not Section 153C — the two regimes raise different arguments.
Related Judgments and Limitations
| Authority | Type | Relevance |
|---|---|---|
| CBDT Circular No. 23/2022, dated 3 November 2022, Para 31.3 | CBDT Explanatory Circular (Finance Act 2022) | Central to the reasoning — explains the retrospective correction of a drafting anomaly in Explanation 2 to Section 148, effective from 1 April 2021 |
Frequently Asked Questions
Yes, in principle, under Explanation 2(iv) to Section 148 — but per this ITAT Delhi ruling, only if the seized material actually pertains to escapement of income for the specific assessment year being reopened, not merely because some documents relating to the assessee were found somewhere in the search.
Per this ruling, the reopening for the unrelated year is not validly triggered, and the Section 148 notice and consequent assessment can be quashed — as happened here for both AY 2020-21 and AY 2021-22.
No. The assessee’s cross objections raising these points were not pressed at the hearing and were dismissed on that basis alone — none of them were actually argued or decided.
No. Since the entire reassessment was quashed at the threshold for lack of year-specific incriminating material, none of the specific quantum additions were examined on their merits by either the CIT(A) or the Tribunal.
No. It is a Division Bench ruling of ITAT Delhi and is persuasive rather than binding elsewhere, and its reasoning largely defers to the CIT(A)’s own findings rather than independently developing the law.
Final Verdict
Based on the above facts and reasoning, the Revenue’s appeals were dismissed and the assessee’s cross objections were dismissed as not pressed. ITAT Delhi upheld the CIT(A)’s quashing of the Section 148 notices and Section 147 reassessment orders for both AY 2020-21 and AY 2021-22, holding that no incriminating material relevant to either year was found in the third-party search, so Explanation 2(iv) to Section 148 could not validly support reopening either year.
Also Read
Corresponding Provisions Under the Income-tax Act, 2025
This case was decided under the Income-tax Act, 1961, as it concerns Assessment Years 2020-21 and 2021-22. Under the Income-tax Act, 2025, the reassessment framework has moved to Sections 279-286: Section 147 (power to assess/reassess escaped income) corresponds to Section 279; Section 148 (reassessment notice) corresponds to Section 280; Section 148A (show-cause procedure) corresponds to Section 281; Section 149 (time limits) corresponds to Section 282; and Section 151 (sanction for issuing notice) corresponds to Section 284. These mappings were verified against multiple independent sources at the time of writing but should be re-checked against the enacted text before being relied on for tax years governed by the new Act.
Source Judgment: DCIT, Central Circle-20, Delhi v. Maharashtra Seamless Ltd., ITA Nos. 4805 & 4806/Del/2026 with C.O. Nos. 274 & 275/Del/2026, ITAT Delhi “H” Bench, order pronounced 20 August 2026. This order can be looked up on the official ITAT judicial search portal using the ITA numbers above.
Want the full order copy? Download it here.
Legal Disclaimer: This article is for general informational purposes only and analyses a specific Tribunal order under the Income Tax Act, 1961, as it applied to Assessment Years 2020-21 and 2021-22. It is not legal or tax advice, and it does not account for developments after the date of publication or for the specific facts of any reader’s case. Several grounds raised by the assessee in this matter were not pressed and remain undecided, as noted above. Readers should verify the applicable current position and consult a qualified Chartered Accountant or tax professional before acting on this or any similar matter.