Atal Pension Yojana taxation is an important consideration for subscribers planning their retirement income. The tax treatment of APY needs to be examined separately at the contribution, pension and exit or benefit stages. The key question is whether APY contributions qualify for a deduction, whether the pension received after the age of 60 is taxable, and how amounts paid to the spouse or nominee are treated under the applicable income-tax provisions.
The Atal Pension Yojana (APY) is a government-backed pension scheme intended to provide a regular pension after the subscriber reaches the age of 60 years. From an income-tax perspective, however, APY should not be treated as automatically tax-free merely because it is a government-backed pension scheme.
The taxation of Atal Pension Yojana needs to be examined separately for APY contributions, deductions claimed during the contribution period, pension received after retirement, pension received by the spouse, and amounts paid to the nominee or legal heirs.
This guide explains Atal Pension Yojana taxation under the applicable income-tax provisions, including whether APY contributions qualify for a deduction, whether the pension is taxable, and how exit, death-related and nominee benefits are treated.
Atal Pension Yojana taxation depends on the nature of the payment and the applicable income-tax provisions. APY contributions may qualify for a deduction under Section 124 of the Income-tax Act, 2025 (corresponding to Section 80CCD of the Income-tax Act, 1961), subject to the prescribed conditions and limits. The deduction for an individual’s own contribution is generally relevant under the old tax regime and is not ordinarily available under the new tax regime.
The pension received under APY is generally treated as taxable pension income and is not automatically exempt merely because it arises from a government-backed pension scheme. The tax treatment of spouse pension, nominee payments, premature closure, exit or other death-related benefits depends on the nature of the payment and the applicable provisions.
Atal Pension Yojana Taxation: An Overview
Atal Pension Yojana taxation can be understood by examining four important aspects: the contribution stage, the pension receipt stage, the death-benefit stage and any permitted premature exit or closure payment.
Contribution Stage
The subscriber makes contributions during the contribution period. APY contributions may qualify for a deduction under Section 124 of the Income-tax Act, 2025 (corresponding broadly to Section 80CCD of the Income-tax Act, 1961), subject to the applicable conditions and limits.
Pension Stage
The subscriber receives the selected pension after reaching 60 years of age. The pension is generally treated as taxable pension income and is not automatically exempt merely because it arises from a government-backed pension scheme.
Death Benefit Stage
After the death of the subscriber, the spouse generally continues to receive the pension. After the death of both the subscriber and spouse, the nominee receives the accumulated pension wealth in accordance with the applicable APY rules.
Premature Exit or Closure Stage
Any permitted premature exit or closure payment must be examined according to its nature and the applicable tax provisions. It should not automatically be treated as tax-free merely because it arises from APY.
A deduction for APY contributions and the taxability of APY pension are two separate issues. Claiming a deduction during the contribution period does not make the future pension automatically exempt from tax.
Atal Pension Yojana Contributions: Tax Treatment and Deduction
The contribution stage is an important part of Atal Pension Yojana taxation. Contributions made to APY are payments towards a future pension. Their tax treatment depends on whether the subscriber satisfies the conditions for claiming a deduction under the applicable income-tax provisions and tax regime.
The payment of an APY contribution does not itself create taxable income for the subscriber. However, the contribution does not automatically qualify for a deduction merely because it is paid into a government-backed pension scheme.
Under Section 124 of the Income-tax Act, 2025 (corresponding to Section 80CCD of the Income-tax Act, 1961), an eligible contribution to a notified pension scheme may qualify for a deduction, subject to the prescribed conditions, applicable tax regime and statutory limits.
- The APY contribution must fall within the scope of the relevant pension-investment deduction provisions.
- The subscriber must satisfy the eligibility conditions applicable to the selected tax regime.
- The deduction is subject to the applicable individual and overall limits. It cannot be claimed merely because the payment is made to a government-backed pension scheme.
- The same contribution cannot be claimed under more than one deduction provision.
- The availability of the deduction must be examined separately from the taxability of the pension received in the future.
An APY contribution is an investment outflow. Its tax benefit, if available, arises through an eligible deduction claim. The contribution itself is not treated as an exempt receipt merely because it is paid into Atal Pension Yojana.
Can Atal Pension Yojana Contributions Be Claimed as a Tax Deduction?
Eligible Atal Pension Yojana contributions may qualify for a deduction under the applicable provisions relating to contributions to specified pension schemes. The deduction is subject to the prescribed conditions, monetary limits and tax regime applicable to the taxpayer.
Under Section 124 of the Income-tax Act, 2025 (corresponding to Section 80CCD of the Income-tax Act, 1961), eligible contributions to a notified pension scheme may qualify for a deduction, subject to the applicable conditions and limits.
The availability of the deduction is an important part of Atal Pension Yojana taxation. It must be examined for the relevant tax year because the old and new tax regimes do not provide identical deductions.
Old Tax Regime
Under the old tax regime, eligible APY contributions may qualify for a deduction under Section 124 of the Income-tax Act, 2025 (corresponding to Section 80CCD of the Income-tax Act, 1961), subject to the prescribed conditions, applicable limits and overall deduction restrictions.
New Tax Regime
Under the new tax regime, deductions are restricted to those specifically permitted by law. An individual’s own APY contribution is not ordinarily eligible for the deduction under Section 124 of the Income-tax Act, 2025 (corresponding to Section 80CCD of the Income-tax Act, 1961).
Even where an APY contribution qualifies for a deduction, that does not mean the pension received later is exempt. The contribution-stage tax benefit and pension-stage taxability must be analysed separately.
Is the Pension Received Under Atal Pension Yojana Taxable?
The regular pension received under Atal Pension Yojana (APY) is generally taxable in the hands of the recipient as pension income. APY pension should not be assumed to be exempt merely because the scheme is sponsored or supported by the government.
The pension is generally received periodically after the subscriber reaches 60 years of age. The amount must ordinarily be included in the recipient’s taxable income and taxed according to the applicable slab rates, exemptions, rebates and tax regime.
Therefore, the pension-stage treatment is an important part of Atal Pension Yojana taxation. The taxability of the pension must be considered separately from any deduction that may have been available when the contributions were made.
- APY pension is generally taxable as pension income in the hands of the recipient.
- The pension is not automatically exempt merely because APY is a government-backed pension scheme.
- The pension may be subject to the applicable basic exemption limit, slab rates, rebates and other general provisions available to the recipient.
- The tax treatment should be examined under the tax regime and law applicable to the relevant financial year.
- A specific exemption should not be assumed unless it is expressly available under the applicable law.
APY should not be treated as an investment where contributions, pension receipts and final benefits are automatically tax-free. The regular pension is generally taxable when received, subject to the applicable income-tax provisions and general reliefs available to the recipient.
Is Pension Received by the Spouse Under Atal Pension Yojana Taxable?
Under Atal Pension Yojana (APY), the spouse generally becomes entitled to receive the pension after the death of the subscriber, subject to the applicable scheme conditions. The spouse generally continues to receive the pension amount payable under the APY rules.
The tax treatment of the pension received by the spouse must be examined in the hands of the spouse as the person receiving the income. The fact that the pension originally arose from the deceased subscriber’s APY account does not automatically make the receipt exempt.
The surviving spouse should generally consider the pension as taxable pension income, subject to the applicable income-tax provisions, slab rates, rebates and deductions available to the spouse. This forms part of the broader Atal Pension Yojana taxation analysis.
The identity of the recipient matters. Pension received by the surviving spouse must be examined separately from the pension wealth paid to the nominee after the death of both the subscriber and spouse. The tax treatment of these receipts should not be assumed to be identical.
What Is the Tax Treatment of APY Death and Nominee Benefits?
Under Atal Pension Yojana (APY), the benefits payable after the death of the subscriber depend on the applicable scheme rules. Generally, the spouse becomes entitled to receive the same pension payable to the subscriber during the spouse’s lifetime.
After the death of both the subscriber and the spouse, the nominee becomes entitled to receive the pension wealth accumulated under the APY rules. Therefore, the regular pension received by the spouse and the lump-sum pension wealth received by the nominee are separate types of receipts and should not be treated identically for tax purposes.
Regular Pension to Spouse
A regular pension received by the surviving spouse should be examined in the hands of the spouse as the recipient. Its tax treatment depends on the applicable income-tax provisions and the legal character of the pension payment.
Lump-Sum Nominee Payment
The pension wealth received by the nominee after the death of both the subscriber and spouse is a separate death-related receipt. It should not automatically be classified as regular pension income. Its tax treatment must be examined under the provisions applicable to the relevant tax year.
A payment made following the death of the subscriber is not automatically tax-free merely because it is described as a death benefit. The exact nature of the receipt, the identity of the recipient and any specific exemption or exclusion available under the applicable law must be verified for the relevant tax year.
Is APY Withdrawal or Closure Amount Taxable?
Atal Pension Yojana (APY) is designed to provide a pension and does not operate like an ordinary savings account with unrestricted withdrawals. However, voluntary exit before the age of 60 is permitted subject to the applicable APY rules.
In case of voluntary exit before 60, the subscriber is generally refunded the contributions made by the subscriber along with the net actual accrued income earned on those contributions, after deducting applicable account maintenance charges. The treatment of any Government co-contribution and the income earned on it may depend on the subscriber’s eligibility and the applicable scheme conditions.
The tax treatment of an APY withdrawal or closure payment depends on the nature of the amount received and the applicable income-tax provisions. It is therefore not appropriate to describe every APY closure or withdrawal amount as automatically exempt or automatically taxable.
- The reason for closure or withdrawal should first be identified, such as voluntary exit, death-related closure or another permitted exit circumstance.
- The amount should be classified according to its legal nature, such as a refund of the subscriber’s contribution, accrued income, pension wealth, pension income or another type of receipt.
- Any specific exemption, exclusion or special tax treatment available under the applicable law should be checked before treating the payment as tax-free.
- The tax treatment of a lump-sum payment may differ from the treatment of regular pension receipts.
APY withdrawal taxability cannot be decided only by looking at the amount received. The reason for payment, the recipient and the legal character of the receipt are important.
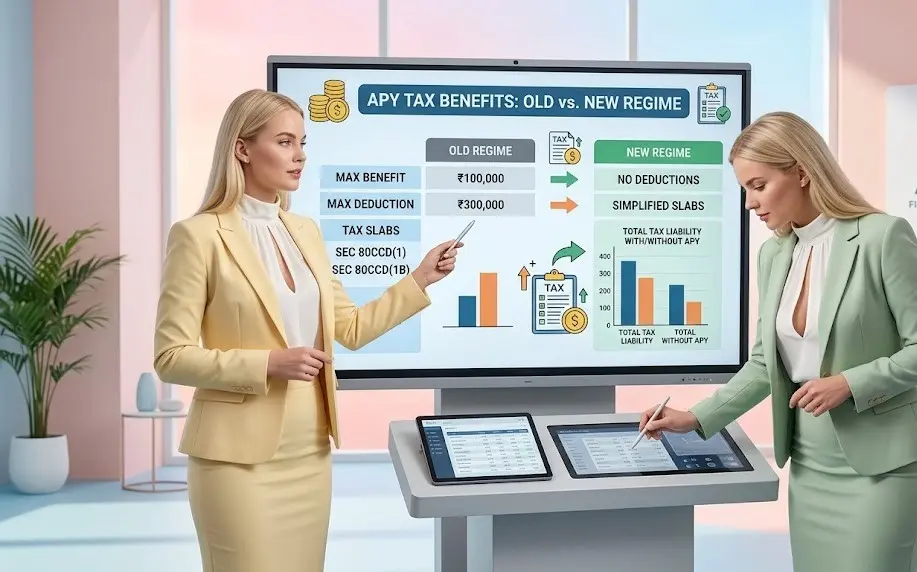
APY Tax Benefits Under the Old and New Tax Regimes
Tax benefits available for Atal Pension Yojana (APY) contributions depend on the tax regime selected by the taxpayer and the provisions applicable for the relevant tax year. APY is covered by the tax-benefit framework applicable to the notified pension scheme, subject to the prescribed conditions and limits.
| Tax Point | Old Tax Regime | New Tax Regime |
|---|---|---|
| APY contribution | An individual’s eligible APY contribution may qualify for deduction under Section 80CCD(1), subject to the applicable percentage limits and the overall Section 80CCE ceiling. | Deduction for the individual’s own APY contribution under Section 80CCD(1) is generally not available under the new tax regime. Section 80CCD(2), where applicable, relates to eligible employer contributions to NPS and should not be confused with an individual’s APY contribution. |
| Additional pension contribution deduction | An additional deduction of up to ₹50,000 may be available under Section 80CCD(1B), subject to the applicable conditions and limits. | The additional deduction under Section 80CCD(1B) is generally not available under the new tax regime. |
| Regular APY pension | Generally taxable in the hands of the recipient under the applicable income-tax provisions, slab rates, rebates and eligible deductions. | Generally taxable in the hands of the recipient under the applicable income-tax provisions, slab rates and rebates. The selected regime does not automatically make regular APY pension tax-free. |
| Spouse pension | Generally examined in the hands of the spouse as the person receiving the pension, subject to the applicable provisions. | Generally examined in the hands of the spouse as the person receiving the pension, subject to the applicable provisions. |
| Death or nominee payment | The tax treatment depends on the nature of the receipt, the identity of the recipient and any specific exemption or exclusion available under the applicable law. | The tax treatment depends on the nature of the receipt, the identity of the recipient and any specific exemption or exclusion available under the applicable law. |
The selected tax regime primarily affects the availability of deductions for APY contributions. It does not automatically convert regular APY pension, spouse pension or death-related receipts into tax-free income.
APY Taxability: Contribution, Pension and Withdrawal
| APY Component | General Tax Treatment |
|---|---|
| APY contribution | The contribution itself is not treated as taxable income merely because it is paid. An eligible deduction may be available subject to the selected tax regime, applicable conditions and prescribed limits. |
| Deduction for contribution | The availability of a deduction depends on the selected tax regime, the applicable provisions, eligibility conditions and prescribed limits. Individual APY contributions generally do not qualify for deduction under the new tax regime. |
| Regular APY pension | Generally taxable in the hands of the recipient under the applicable income-tax provisions, subject to applicable slab rates, rebates and eligible deductions. |
| Pension received by spouse | Generally examined in the hands of the spouse as the person receiving the pension, subject to the applicable income-tax provisions. |
| Death or nominee benefit | The tax treatment depends on the nature of the payment, the identity of the recipient and any specific exemption or exclusion available under the applicable law. |
| Permitted withdrawal or closure amount | The treatment must be examined according to the reason for payment, the legal character of the receipt and the applicable tax provisions for the relevant year. |
Key Takeaways
- APY contributions are not automatically deductible merely because the scheme is government-backed.
- An eligible deduction may be available subject to the applicable tax regime, conditions and prescribed limits.
- Regular APY pension is generally taxable in the hands of the recipient under the applicable income-tax provisions.
- Pension received by the spouse must be examined separately in the hands of the spouse as the person receiving the income.
- Death benefits and nominee payments require classification based on the nature of the receipt, the recipient and the applicable law.
- Permitted withdrawal or closure amounts should not automatically be treated as tax-free.
- A contribution-stage deduction does not make future APY pension receipts exempt.
APY provides a pension benefit, but it should not be treated as a completely tax-free investment. Eligible contributions may provide a deduction under the applicable provisions, subject to the selected tax regime, conditions and limits, while regular pension receipts are generally taxable in the hands of the recipient. The tax treatment of spouse pension, death benefits and permitted withdrawal amounts depends on the nature of the payment, the recipient and the applicable law.
Frequently Asked Questions About Atal Pension Yojana Taxation
Are Atal Pension Yojana contributions tax-deductible?
Eligible Atal Pension Yojana contributions may qualify for a deduction under the applicable pension contribution provisions, subject to the conditions, limits and tax regime applicable to the taxpayer. Under the old tax regime, the deduction may be available under Section 80CCD(1), and an additional deduction may be available under Section 80CCD(1B), subject to the prescribed limits.
Is APY pension taxable?
Yes. Regular pension received under Atal Pension Yojana is generally taxable in the hands of the recipient under the applicable income-tax provisions, subject to the relevant slab rates, rebates and eligible deductions.
Is APY pension tax-free because it is a government scheme?
No. Government backing does not automatically make Atal Pension Yojana pension tax-free. The pension is generally taxable under the applicable income-tax provisions unless a specific exemption or exclusion applies.
Is pension received by the spouse under APY taxable?
Pension received by the surviving spouse should be examined separately in the hands of the spouse as the person receiving the income. It is generally subject to the applicable income-tax provisions, and its exact treatment should not be assumed solely from the fact that it originated from the deceased subscriber’s APY account.
Is the APY death benefit received by a nominee taxable?
It depends on the nature of the payment and the applicable provisions. The pension wealth received by the nominee after the death of both the subscriber and spouse is a separate death-related receipt and should not automatically be treated as regular pension income or as tax-free without examining its legal character.
Is APY withdrawal or closure amount tax-free?
Not automatically. Any permitted withdrawal or closure amount must be examined according to the reason for payment, the nature of the receipt, the identity of the recipient and the applicable tax provisions for the relevant tax year.
Can APY deduction be claimed under the new tax regime?
Generally, an individual’s own APY contribution does not qualify for deduction under Section 80CCD(1) or the additional deduction under Section 80CCD(1B) when the new tax regime is selected. The taxpayer should verify the deductions specifically permitted for the relevant tax year before claiming any deduction.
Does claiming an APY deduction make the pension tax-free?
No. A deduction claimed at the contribution stage and the taxability of pension received later are separate issues. Regular APY pension is generally taxable in the hands of the recipient under the applicable income-tax provisions.
Sources and References
- Income Tax Department — Official Portal — Official source for income-tax provisions, rules, notifications, forms and return-filing guidance.
- Pension Fund Regulatory and Development Authority — Official regulatory information relating to pension schemes, including the Atal Pension Yojana.
- India Post — Official government information relating to pension and small-savings schemes.
- Income Tax Department — Official Portal — For the latest applicable tax provisions, rules, notifications and return-filing guidance.
Disclaimer: This article on Atal Pension Yojana taxability is provided for general informational and educational purposes only. The tax treatment of APY contributions, pension receipts, spouse pension, death benefits, nominee payments and withdrawal or closure amounts may depend on the nature of the receipt, the applicable provisions, the relevant Tax Year, the tax regime selected and the facts of the case.
Tax laws, rules, notifications and scheme conditions may change. Readers should verify the applicable provisions before claiming a deduction or reporting any APY-related receipt in an income-tax return. The information should not be treated as legal, tax, financial or investment advice.
TaxBizmantra does not guarantee that the information remains complete, error-free or applicable to every taxpayer. Readers should consult a qualified Chartered Accountant or tax professional before taking a tax or investment decision.