Case at a glance
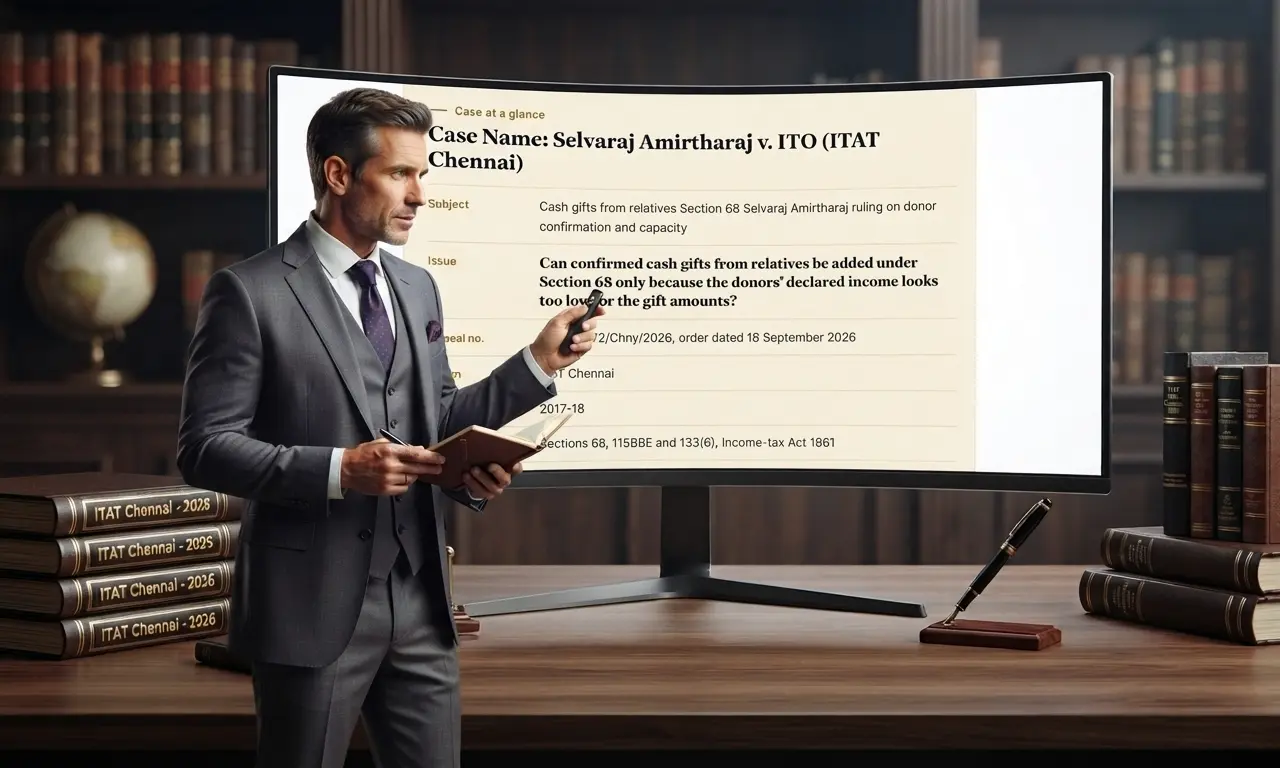
Case Name: Selvaraj Amirtharaj v. ITO (ITAT Chennai)
- Subject
- Cash gifts from relatives Section 68 Selvaraj Amirtharaj ruling on donor confirmation and capacity
- Issue
- Can confirmed cash gifts from relatives be added under Section 68 only because the donors’ declared income looks too low for the gift amounts?
- Appeal no.
- ITA No. 372/Chny/2026, order dated 18 September 2026
- Forum
- ITAT Chennai
- Assessment year
- 2017-18
- Provisions
- Sections 68, 115BBE and 133(6), Income-tax Act 1961
- Outcome
- In favour of assessee
Background
Facts of the Case
- In FY 2016-17, the assessee received cash gifts of Rs 85.30 lakh from five relatives: his wife, a maternal uncle, two paternal uncles and his sister’s husband.
- He filed gift deeds, the donors’ income-tax returns and financial statements. All five donors confirmed the gifts in reply to notices under Section 133(6).
- The AO still treated the Rs 85.30 lakh as unexplained cash credits under Section 68, read with Section 115BBE.
- The CIT(A) upheld the addition, doubting the donors’ financial capacity and relying on adverse findings in some donors’ own assessments.
The ruling
Summary of Decision: What the Tribunal Held
- By producing donor confirmations, gift deeds and the donors’ returns, the assessee discharged his initial burden under Section 68.
- The authorities only compared the donors’ declared income with the gift amounts. They did not examine accumulated capital, withdrawals, cash balances or other resources.
- Adverse findings in some donors’ own assessments could not be applied to the assessee without independent material showing the money was his own.
- Doubts about the donors’ sources belong in the donors’ assessments. The Revenue had no material that the cash came from the assessee, so the addition of Rs 85.30 lakh was deleted.
Practice point
Key Takeaway: Cash Gifts from Relatives Section 68 Selvaraj Amirtharaj Ruling
- For cash gifts, collect gift deeds, donor confirmations, the donors’ ITRs and financial statements before scrutiny begins.
- Make sure donors reply to any Section 133(6) notice. Their confirmation was central here.
- If the AO relies only on the donors’ low declared income, argue that their overall resources, such as savings, capital and withdrawals, must be examined.
- Adverse findings in a donor’s own case are not automatically evidence against you.
- This is an ITAT order, so it is persuasive, not binding outside the bench. Large cash gifts remain high-risk, so documentation matters.
Keep reading