Insurance in India became meaningfully cheaper on September 22, 2025, when the government made the applicable GST rate zero on individual life and health insurance policies. That’s the good news. The confusing part hasn’t changed: people comparing term insurance vs health insurance vs ULIP still often struggle to understand which one they need, in what order, or whether they need all three. Product incentives can also influence recommendations, making it important to focus on your actual financial protection needs rather than simply choosing the product being promoted. Here’s the honest breakdown.
When comparing term insurance vs health insurance vs ULIP, many buyers focus on the product being recommended rather than the financial protection they actually need. A bank representative may introduce a ULIP as an investment opportunity, while an insurance agent may recommend a combination plan that brings life cover and investment features together. But term insurance, health insurance, and ULIPs serve different purposes: term insurance protects your family’s income, health insurance helps manage medical expenses, and a ULIP combines life insurance with market-linked investing. This guide explains the key differences between term insurance, health insurance, and ULIPs, the order in which you should generally consider buying them, and why understanding your needs is more important than choosing the product with the most persuasive sales pitch.
Term Insurance vs Health Insurance vs ULIP: The GST Change That Made Individual Insurance Cheaper
At its 56th meeting on September 3, 2025, the GST Council approved a major change that took effect from September 22, 2025: the GST rate on eligible individual life insurance and individual health insurance policies was reduced from 18% to zero. The exemption covers term insurance, ULIPs, endowment plans, individual health insurance, family floater plans, senior citizen health covers, and eligible top-up or super top-up policies. However, the treatment of a particular premium can depend on the applicable GST time-of-supply rules, including the timing of the supply, invoice and premium payment. The exemption is specifically for individual policies; group insurance and employer-sponsored group life or health policies generally continue to attract 18% GST.
Assume your annual term insurance premium is ₹15,000 before GST. Under the earlier 18% GST rate, you would have paid an additional ₹2,700, taking the total to ₹17,700. For an eligible individual policy covered by the exemption effective from September 22, 2025, the same ₹15,000 premium would generally be payable without GST. That means a saving of ₹2,700 a year on the assumed premium. The same principle applies to eligible individual health insurance premiums, subject to the applicable GST time-of-supply rules.
There’s an important exception worth knowing: group insurance policies—including many employer-provided group life and health policies—generally continue to attract 18% GST. The exemption is specifically for eligible individual policies purchased by the policyholder. Even when your employer provides group health or life cover, review its sum insured, exclusions, dependants’ coverage and continuity before deciding whether additional personal insurance is required.
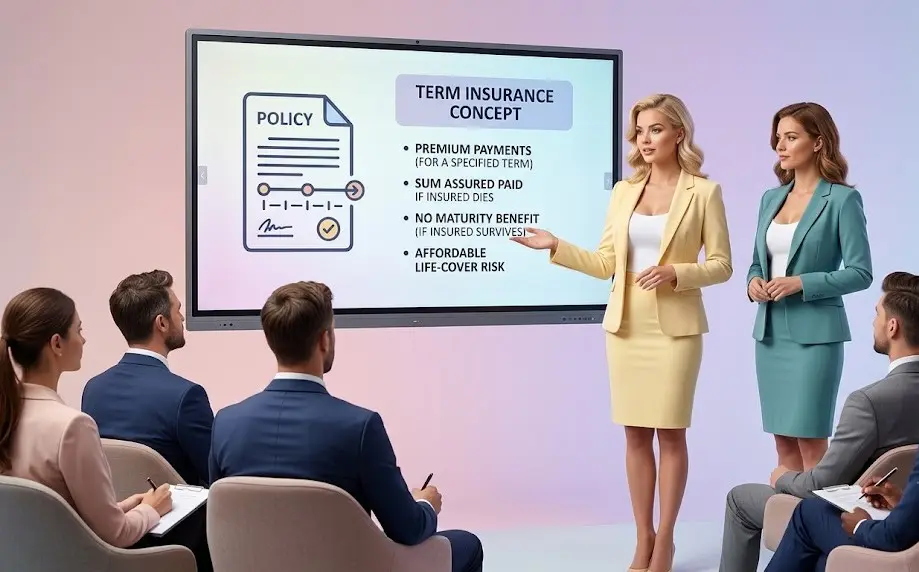
Term insurance is one of the simplest forms of life insurance. You pay a premium for a specified policy term, and if the insured person dies during that term, the nominee receives the applicable sum assured, subject to the policy terms and conditions. Under a standard pure-term insurance policy, if the insured person survives the policy term, no maturity benefit is payable and the cover ends. This absence of an investment or maturity component is one of the main reasons pure-term insurance is generally more affordable than savings-oriented or investment-linked life insurance products. The premium primarily pays for life-cover risk, although the actual cost can also reflect policy features, riders, underwriting, taxes and other applicable charges.
- Purpose: Replace or supplement the income available to your dependents if you die, helping them manage regular expenses, outstanding loans and future financial goals
- Coverage rule of thumb: A sum assured of around 10 to 15 times annual income is sometimes used as an initial estimate, but the appropriate cover should also account for outstanding loans, existing assets, inflation, dependants and future goals such as children’s education
- What actually matters when choosing a policy: Do not choose solely on the lowest premium or one claim-settlement statistic. Consider the insurer’s claim-settlement record, financial strength, policy terms, exclusions, service quality and the suitability of the coverage
- GST status: 0% since September 22, 2025 for eligible individual life insurance policies, subject to the applicable GST rules
- Best bought: Generally as early as practical, once you have a genuine need for life cover. Premiums are usually influenced by your age, health, policy term, sum assured and other underwriting factors, so buying earlier may help you secure a lower premium for comparable coverage
Health insurance exists to protect your savings, not to make you money. That distinction matters because it changes how you should think about the premium you pay for a policy you may never claim on. A single serious hospitalisation can cost several lakhs, and a health insurance policy helps ensure that an eligible medical bill does not have to be funded entirely from your emergency fund, retirement savings or borrowed money. The actual protection available will depend on the policy’s sum insured, coverage terms, exclusions, deductibles and claim conditions.
Individual vs Family Floater vs Super Top-Up
- Individual policy: A separate sum insured is available for each insured family member. A large claim by one person generally does not reduce the sum insured available to the other insured members, subject to the policy terms
- Family floater: A single shared sum insured applies to the insured family members. It may be more economical than buying separate policies, but a large claim by one member can reduce the remaining coverage available to everyone else during the policy period
- Super top-up: A policy that provides additional coverage after the specified aggregate deductible is crossed during the policy period. Depending on the terms, the deductible may be met through one large claim or multiple eligible claims. It can be a cost-efficient way to increase overall protection without paying the full premium for a much larger base policy
Relying solely on your employer’s group health insurance can be a significant insurance risk for salaried Indians. Group cover is generally linked to employment and may end when you leave the organisation, although continuation, portability or conversion options may be available under the insurer’s and employer’s policy terms. The coverage may also be insufficient because of the sum insured, family coverage limits, exclusions, room-rent restrictions, sub-limits or other conditions. An individual or family floater policy in your own name can provide greater independence from employment and help fill these gaps. Eligible individual health insurance policies have also benefited from the GST exemption effective from September 22, 2025.
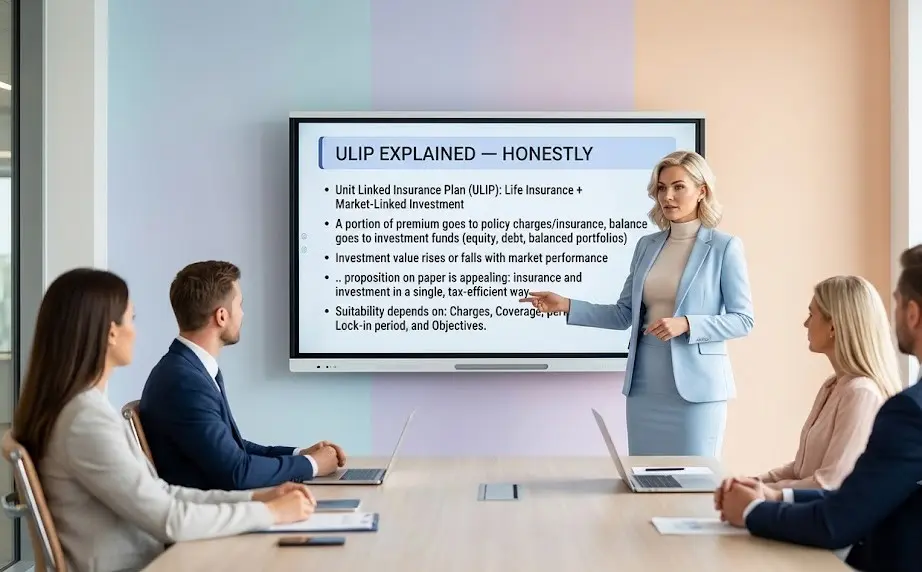
A Unit Linked Insurance Plan (ULIP) combines life insurance with market-linked investment. Depending on the policy structure, a portion of the premium is used toward applicable insurance and policy charges, while the balance is allocated to investment funds linked to assets such as equity, debt or balanced portfolios. The investment value can rise or fall with market performance, and the policy’s charges, fund allocation and insurance benefits affect the overall outcome. On paper, the proposition is appealing: insurance and investment in a single product, often presented as a tax-efficient way to build wealth. In practice, the suitability of a ULIP depends on its charges, insurance coverage, investment performance, lock-in period, liquidity and the buyer’s objectives.
Where ULIPs May Fall Short
- Charges: ULIPs may include premium-allocation charges, policy-administration charges, mortality charges, fund-management charges, switching or other applicable charges. The exact structure varies by product, so compare the policy’s benefit illustration and charge schedule rather than relying on a universal percentage
- Lock-in: A mandatory five-year lock-in generally applies to ULIPs. If the policy is surrendered or premiums are discontinued during this period, the applicable fund value may be transferred to a Discontinued Policy Fund, subject to the policy terms and applicable regulations. The amount is generally payable only after completion of the lock-in period, unless a specified death benefit or other permitted event applies
- Insurance cover: The death benefit and the relationship between the sum assured and fund value depend on the particular ULIP. Some policies provide the higher of the sum assured or fund value, while others may have a different structure. Therefore, do not assume that the insurer’s risk exposure always equals the sum assured minus the fund value
- Limited flexibility: The lock-in period, policy charges, surrender conditions and consequences of stopping premiums can make a ULIP less flexible than keeping life insurance and investments in separate products
When comparing a ULIP with a term plan and a separate investment, use the same total outflow, insurance coverage, investment horizon, risk level and tax assumptions. A separate term policy may provide a larger life cover at a lower premium, while a separate investment may offer greater transparency and flexibility. However, the outcome depends on the specific products, charges, market performance, tax treatment and the time for which each investment is held.
The Tax Rule Most ULIP Buyers Don’t Know
ULIP maturity proceeds are not automatically tax-free. For ULIPs issued on or after February 1, 2021, the exemption under Section 10(10D) is subject to the applicable statutory conditions, including the condition that the aggregate annual premium payable for such ULIPs does not exceed ₹2.5 lakh. Other conditions under Section 10(10D), including those relating to the nature and continuity of the policy, must also be satisfied. Where the exemption is not available, the tax treatment must be determined under the applicable capital-gains provisions. The classification and rate depend on the relevant law, the nature of the underlying fund or asset and the applicable holding-period rules; therefore, a non-exempt ULIP should not automatically be described as attracting one fixed LTCG or STCG rate. Policies issued before February 1, 2021 may be covered by the earlier rules, subject to the conditions applicable to those policies.
If You Already Own a ULIP
If you’re reading this because you already have a ULIP—perhaps sold to you as a “tax-saving investment plan” a few years ago—don’t panic or make an emotional decision. Exiting, continuing or reducing premiums can have different financial and insurance consequences. A sensible decision should be based on the policy’s current value, future benefits, charges, tax treatment and your own financial objectives.
- Check your lock-in status: If you’re within the first five years, review the policy’s discontinuance rules, applicable charges, fund value, insurance benefits and tax implications before considering surrender or stopping premiums. Poor recent performance alone does not establish that surrendering is the better option
- Check the actual fund performance against a suitable benchmark or comparable mutual fund category over the same period, while accounting for risk, asset allocation, charges and the difference between past performance and future expectations
- Never decide based on sentiment or an agent’s persuasion: Compare the current fund value, surrender value, future premiums, charges, death benefit, maturity benefit, tax treatment and the financial consequences of continuing, surrendering or making the policy paid-up, where permitted
- If you’re past the five-year lock-in and the policy is performing reasonably: Continuing may be more practical than exiting, particularly if the policy has favourable terms or may qualify for tax treatment under the earlier Section 10(10D) rules. Confirm the applicable conditions before assuming that maturity proceeds will be tax-free
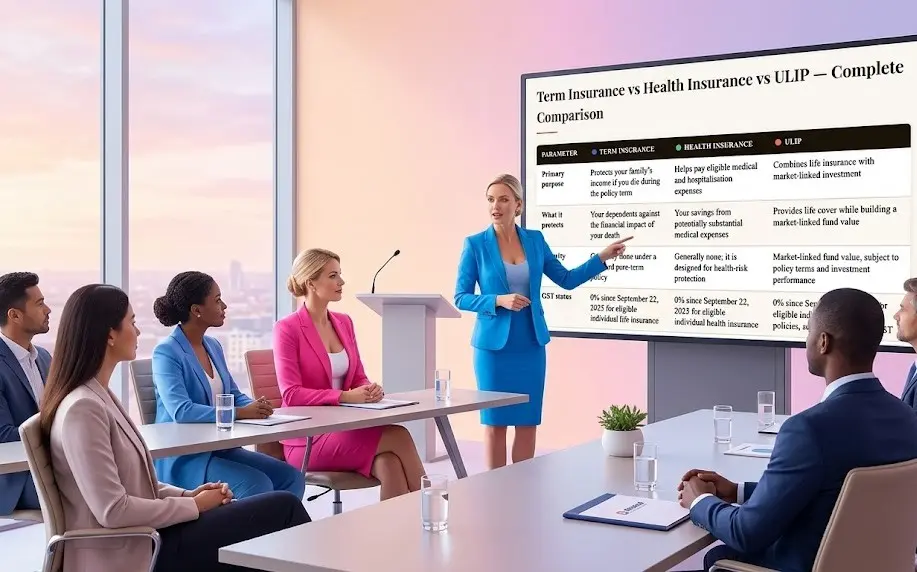
Term Insurance vs Health Insurance vs ULIP — Complete Comparison
| Parameter | 🔵 Term Insurance | 🟢 Health Insurance | 🟠 ULIP |
|---|---|---|---|
| Primary purpose | Protects your family’s income if you die during the policy term | Helps pay eligible medical and hospitalisation expenses | Combines life insurance with market-linked investment |
| What it protects | Your dependents against the financial impact of your death | Your savings from potentially substantial medical expenses | Provides life cover while building a market-linked fund value |
| Maturity value | Generally none under a standard pure-term policy | Generally none; it is designed for health-risk protection | Market-linked fund value, subject to policy terms and investment performance |
| GST status | 0% since September 22, 2025 for eligible individual life insurance policies | 0% since September 22, 2025 for eligible individual health insurance policies | 0% since September 22, 2025 for eligible individual life insurance policies, subject to applicable GST rules |
| Lock-in or continuity | No investment lock-in, but discontinuing the policy ends or reduces life cover according to the policy terms | Usually renewed annually, although multi-year policies are also available; coverage depends on renewal and policy conditions | Generally has a mandatory five-year lock-in |
| Charges and costs | Primarily reflects mortality risk, underwriting, policy features, riders and applicable charges | Depends on age, health, coverage, deductibles, policy features and insurer pricing | May include premium-allocation, policy-administration, mortality, fund-management and other applicable charges |
| Tax treatment | Death benefits and eligible maturity or other payments are subject to the applicable provisions of the Income-tax Act | Health insurance is generally a protection product; tax treatment of premiums and claims depends on the applicable provisions | Section 10(10D) exemption is subject to statutory conditions, including the applicable aggregate annual premium limit for certain ULIPs; non-exempt proceeds require analysis under the applicable tax provisions |
| Best suited for | People whose dependents, loans or financial obligations require income protection | Individuals and families seeking protection against eligible medical expenses | Buyers who understand the product’s insurance structure, charges, lock-in and market-linked risks |
| Key limitation | Provides no investment value under a standard pure-term policy | Claims are subject to coverage limits, exclusions, waiting periods, deductibles and policy terms | Lower flexibility during the lock-in period and a more complex cost and benefit structure |
| Sources: GST Council 56th meeting materials and Department of Financial Services insurance FAQs; IRDAI regulations; Income-tax Act, including Section 10(10D); Finance Bill 2025 memorandum. | |||
The Right Order to Buy Term Insurance, Health Insurance and ULIP Alternatives
- Health insurance — consider an individual or family floater policy after reviewing any employer-provided cover, its limits, exclusions and dependant coverage
- Term insurance — prioritise adequate life cover if anyone financially depends on your income or you have significant financial obligations
- Build an emergency fund covering approximately 3–6 months of essential expenses, adjusted for income stability and personal circumstances
- Consider a super top-up after reviewing your base health policy, deductible, exclusions and overall coverage requirement
- Consider suitable wealth-building options such as mutual funds, PPF or NPS based on your goals, risk tolerance, liquidity needs and tax position
- Review your term insurance coverage as your income, liabilities, family responsibilities and financial goals change
Frequently Asked Questions — Term vs Health vs ULIP
Sources & References
Official sources used for GST treatment, ULIP taxation and insurance guidance.
- Department of Financial Services — Insurance GST FAQ
- GST Council — Insurance GST Recommendations
- Income Tax Department — Section 10(10D) and ULIP Tax Rules
- IRDAI — Insurance Regulations and Policyholder Guidance
Verify the applicable law, policy terms and current regulatory guidance before making insurance or tax decisions.