Case at a glance
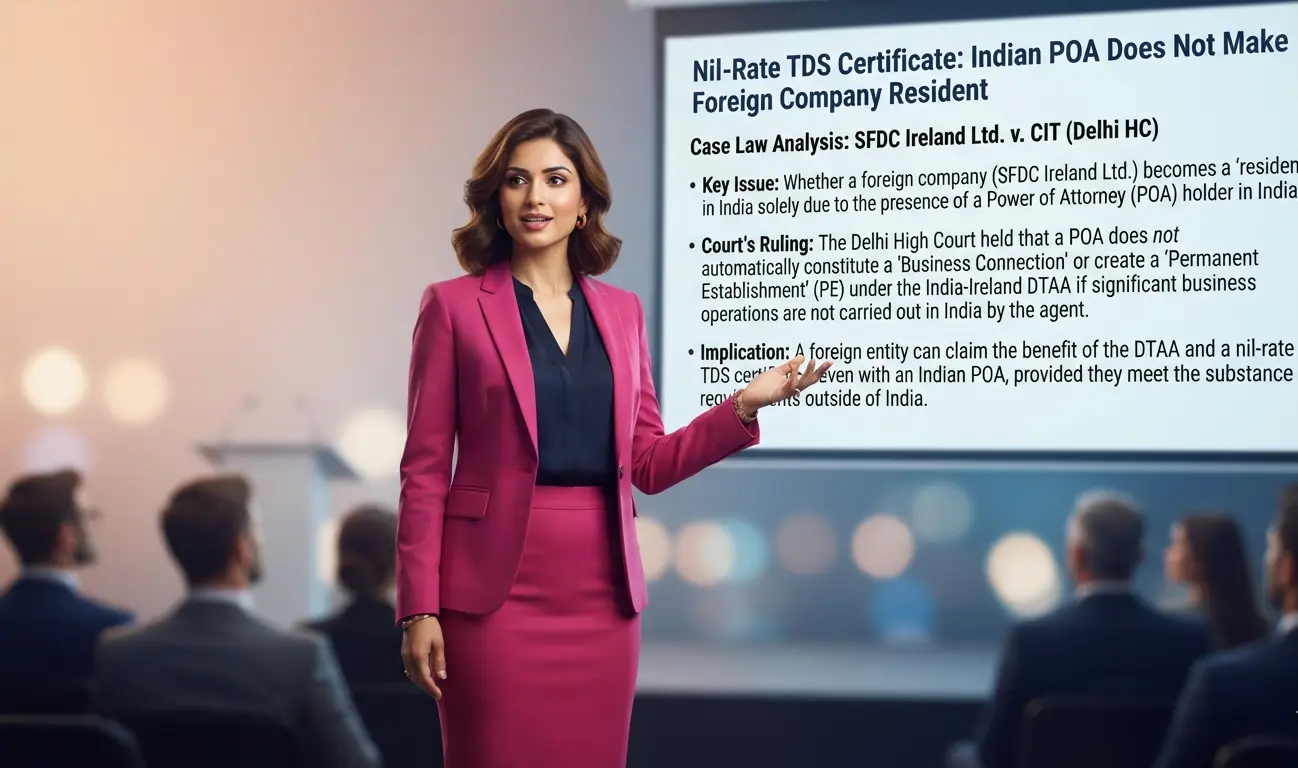
Case Name: SFDC Ireland Ltd. v. CIT
- Subject
- Nil-rate TDS certificate refused to a foreign company with a power of attorney holder in India
- Issue
- Can the Department refuse a nil‑rate TDS certificate by treating an Irish company as resident under Section 6(3) only because its Indian power of attorney holder filed its forms, despite earlier High Court orders in the company’s favour?
- Citation
- (2026) 349 CTR 729; 182 taxmann.com 533 (Delhi)
- Court
- Delhi High Court (writ)
- Assessment year
- 2025-26
- Provisions
- Section 6(3), Income-tax Act 1961
- Outcome
- In favour of assessee
Background
Facts of the Case
- The assessee is a company incorporated in Ireland. It had a power of attorney holder residing in India, who filed its forms.
- In earlier years, the High Court had passed orders in the assessee’s own case granting it nil-rate TDS certificates.
- This time, the Department refused the nil-rate certificate and directed tax to be deducted at 10 per cent.
- The assessee challenged the refusal before the Delhi High Court.
The ruling
Summary of Decision: What the High Court Held
- Giving a power of attorney to a person in India, who then files forms for the company, does not make the company resident in India under Section 6(3). This is especially so when there is no finding that its entire business is managed or controlled from India, or that it has a permanent establishment in India.
- Proceedings for each assessment year are separate. Even so, to depart from earlier binding orders, the authority must show a change in facts or a new fact that justifies a different view.
- There was no such finding here. The order directing deduction at 10 per cent was quashed, and a nil-rate TDS certificate was directed to be issued for AY 2026-27 and later years.
Practice point
Key Takeaway on Nil-Rate TDS Certificate Refusals
- An Indian power of attorney holder handling filings does not, by itself, make a foreign company resident in India.
- A residence finding needs evidence that the business is managed or controlled from India, or a finding of a permanent establishment.
- Where certificates were granted in earlier years, especially under court orders, the Department must point to changed or new facts before refusing.
- A refusal that does not identify any such change is open to challenge in a writ petition.
Keep reading