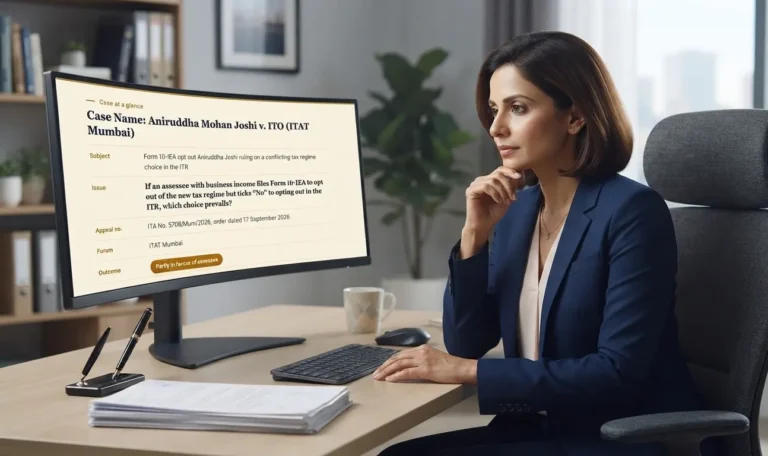
Case at a glance
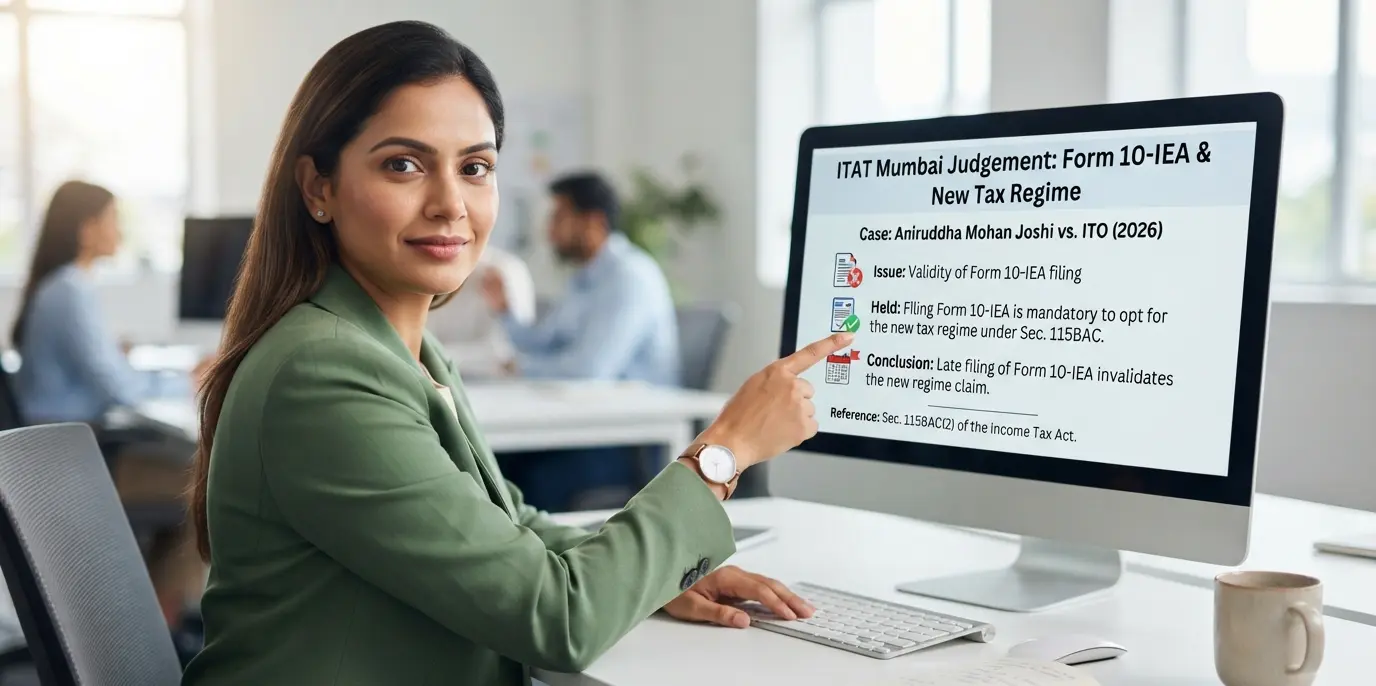
Case Name: Aniruddha Mohan Joshi v. ITO, Ward 16(2)(1), Mumbai (ITAT Mumbai, 2026)
- Subject
- Form 10-IEA new tax regime conflict: which choice governs when the Form 10-IEA opts out of the new regime but the return says the taxpayer does not wish to opt out
- Issue
- Where an assessee with business or professional income filed Form 10-IEA opting out of the new tax regime, but then ticked “No” to opting out in his return, could the CPC process the return under the old regime and raise a demand of Rs.1,41,480?
- Appeal no.
- ITA No. 5706/MUM/2026, order pronounced on 17 September 2026
- Forum
- ITAT Mumbai “A” Bench (Shri Om Prakash Kant, Accountant Member, and Shri Siddhartha Nautiyal, Judicial Member); order authored by Shri Om Prakash Kant
- Assessment year
- 2025-26
- Provisions
- Sections 115BAC, 143(1), 154, 80C, 80D and 80TTB, Income-tax Act 1961 (Sections 202, 270(1), 287, 123, 126 and 153 of the Income-tax Act 2025)
- Outcome
- Partly in favour of assessee
- Order copy
- Download the full order
Background
Facts of the Case
- The assessee, an individual from Mumbai, had opted for the new tax regime for AY 2024-25, the preceding year. [Para 6.1 of the order]
- For AY 2025-26, he filed Form 10-IEA on 31 August 2025, opting out of the new tax regime under Section 115BAC and choosing the old regime. [Paras 3 and 6.1 of the order]
- On 16 September 2025, he filed his return in Form ITR-3, declaring total income of Rs.33,88,170. Against the question “Do you wish to opt out of the new tax regime for the current assessment year?” in Clause A(19)(b) of Part A, he ticked “No”. [Paras 2 and 6 of the order]
- The CPC processed the return under Section 143(1) on 29 January 2026, taking into account the Form 10-IEA, and raised a demand of Rs.1,41,480. A rectification request filed on 11 February 2026 was rejected under Section 154 on 17 February 2026. [Para 3 of the order]
- The first appellate authority, the Additional/Joint Commissioner of Income-tax (Appeals), dismissed the appeal on 20 March 2026, holding that since the assessee had himself opted out of the new regime through Form 10-IEA, the claim in the return was incorrect and the CPC’s adjustment was justified. [Paras 1 and 4 of the order]
- Before the Tribunal, the assessee argued that the choice in the return should prevail, that the intimation was invalid because no prior intimation of the adjustment was given, and, in the alternative, that if the old regime applied he should get the old-regime deductions under Sections 80C, 80D and 80TTB. [Paras 1 and 5 to 8 of the order]
The timeline
The Two Conflicting Choices: Key Dates
- AY 2024-25
- Assessee had opted for the new tax regime
- 31 Aug 2025
- Form 10-IEA filed for AY 2025-26: opts out of the new regime and chooses the old regime
- 16 Sep 2025
- Return filed in ITR-3: answers “No” to opting out of the new regime
- 29 Jan 2026
- Intimation under Section 143(1): CPC follows Form 10-IEA; demand of Rs.1,41,480
- 17 Feb 2026
- Rectification under Section 154 rejected
- 20 Mar 2026
- First appeal dismissed by the Additional/Joint Commissioner (Appeals)
- 17 Sep 2026
- Tribunal: Form 10-IEA prevails, but old-regime deductions to be allowed
The return was filed on 16 September 2025. For AY 2025-26, the CBDT had extended the due date for returns originally due on 31 July 2025 to 16 September 2025. The timing of the return was not in dispute.
The ruling
Summary of Decision: What the Tribunal Held
Partly allowing the assessee’s appeal, the Tribunal held:
- That once a specific form has been prescribed for opting out of the new tax regime, an assessee who has opted out through Form 10-IEA cannot choose the new regime merely by ticking a box in the return, so the CPC rightly followed the Form 10-IEA. [Paras 6.2 to 6.6 of the order]
- That the intimation under Section 143(1) could not be quashed for want of prior intimation, since the assessee produced no material from the portal to show that no prior intimation was issued, and Rallis India was distinguishable on facts. [Paras 7 and 7.1 of the order]
- That if the assessee is treated as having opted for the old regime, the deductions available under the old regime must be allowed, and the matter was restored to the Assessing Officer for that limited purpose. [Para 8 of the order]
Why
Reasoning Behind the Decision
- The prescribed form decides the regime. In this Form 10-IEA new tax regime dispute, the Tribunal noted that under Section 115BAC, the option to move out of the new regime is exercised by filing Form 10-IEA, and that for an assessee with business or professional income the option, once exercised, can be withdrawn only in a later year. The question was whether the assessee could reverse his Form 10-IEA choice for the same year otherwise than through the form. The Tribunal held he could not: once a specific form is prescribed, the choice cannot be made or reversed by a tick box in the return. [Paras 6.2 to 6.4 of the order]
- The option in Form 10-IEA had already been accepted. The assessee was in the new regime for AY 2024-25 and opted out for AY 2025-26 through the form filed on 31 August 2025, which was accepted. The later “No” in the return did not undo that option. The Tribunal described it as a case where “wrong box has been ticked”. [Paras 6.1, 6.3 and 6.6 of the order]
- Akshay Nitin Malu was distinguishable. The assessee relied on the Pune Tribunal’s decision in Akshay Nitin Malu v. ITO (ITA No. 1651/PUN/2024). There, the assessee had chosen the old regime in both the form and the return, but the CPC computed income under the new regime, and the Tribunal directed that the old regime be applied. Here, the form and the return contradicted each other, so that decision did not help. [Paras 6 and 6.5 of the order]
- No proof that prior intimation was missing. The assessee argued that the adjustment was made without the prior intimation required by Section 143(1). The Tribunal asked him to produce details from the income-tax portal showing that no intimation was sent by email or letter, and he produced none. [Para 7 of the order]
- Rallis India turned on an admission. In Rallis India Ltd. v. CPC (Writ Petition No. 37314 of 2025, decided on 19 January 2026), the Bombay High Court quashed the intimation because the department admitted in its affidavit that no notice of the proposed adjustment had been issued. In the absence of such an admission or other proof here, the Tribunal held that decision did not apply. [Para 7.1 of the order]
- The old regime must come with its deductions. On the alternative plea, the Tribunal found merit: if the CPC holds that the old regime applies, the deductions available under the old regime must also be allowed. It restored the matter to the Assessing Officer to consider the assessee’s claim, which the grounds put at Rs.1,50,000 under Section 80C, Rs.50,000 under Section 80D and Rs.50,000 under Section 80TTB. [Paras 1 and 8 of the order]
Practice point
Key Takeaway: Getting the Form 10-IEA New Tax Regime Choice Right
- The form and the return must say the same thing. If you file Form 10-IEA to opt out of the new tax regime, answer “Yes” to opting out in the return and compute income under the old regime, with your deductions.
- Changing your mind needs the form, not a tick box. According to this ruling, a choice made in Form 10-IEA cannot be reversed for the same year by ticking a box in the return. For business or professional income, withdrawal is restricted, so check the rules before filing the form at all.
- If the CPC applies the old regime, claim the deductions. Here, the assessee’s alternative plea was that, once the old regime was applied, its deductions should also be allowed, and the Tribunal accepted it. Ask for Sections 80C, 80D and other deductions in the rectification request and in appeal, as this assessee did in the alternative.
- Prove the absence of prior intimation. If you challenge a Section 143(1) intimation for want of prior intimation, download your e-proceedings and communication history from the portal and file it. Without that evidence, the Tribunal will not presume that no intimation was sent.
- Check your filing dates. Form 10-IEA must be filed by the due date for the return under Section 139(1). For AY 2025-26, the due date for returns originally due on 31 July 2025 was extended to 16 September 2025.
- The order has drafting slips. It refers to the form as both “10-IEA” and “10-IE”, spells the Pune case as both “Akshay” and “Akshar”, records once that the assessee’s return “mentioned that assessee was opting out”, and calls the deduction ground “ground number 4” when it was ground 5. None affects the result.
Read the full Tribunal order
Download the complete order copy as a PDF.
Download order
Keep reading