Case at a glance
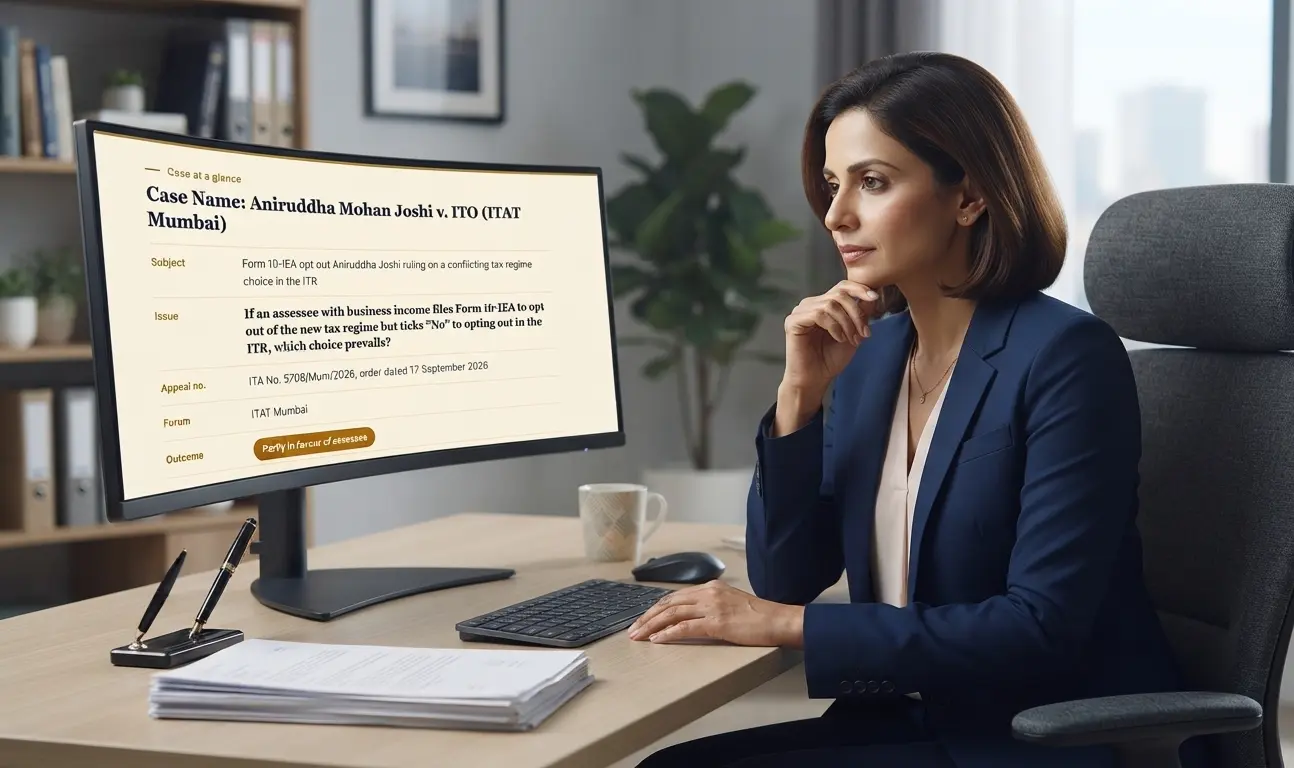
Case Name: Aniruddha Mohan Joshi v. ITO (ITAT Mumbai)
- Subject
- Form 10-IEA opt out Aniruddha Joshi ruling on a conflicting tax regime choice in the ITR
- Issue
- If an assessee with business income files Form 10‑IEA to opt out of the new tax regime but ticks “No” to opting out in the ITR, which choice prevails?
- Appeal no.
- ITA No. 5706/Mum/2026, order dated 17 September 2026
- Forum
- ITAT Mumbai
- Assessment year
- 2025-26
- Provisions
- Sections 115BAC and 143(1), Income-tax Act 1961; Form 10-IEA
- Outcome
- Partly in favour of assessee
Background
Facts of the Case
- The assessee, who had business or professional income, was taxed under the new regime for AY 2024-25.
- For AY 2025-26, he filed Form 10-IEA on 31 August 2025 to opt out of the new regime and choose the old regime.
- On 16 September 2025, he filed ITR-3 and answered “No” to the question asking whether he wished to opt out of the new regime.
- CPC processed the return under Section 143(1) on the basis of Form 10-IEA and raised a demand of Rs 1,41,480. His rectification request was rejected, and he appealed.
The ruling
Summary of Decision: What the Tribunal Held
- Where Section 115BAC prescribes a specific form for exercising the option, the assessee cannot opt in or out any other way. A contrary tick in the return does not override a valid Form 10-IEA opt-out.
- Akshay Nitin Malu v. ITO (ITAT Pune) was distinguished, because there both the form and the return chose the old regime. Here they were inconsistent.
- The challenge that no prior intimation was given under Section 143(1) failed, because the assessee produced no portal records to support it.
- On the alternative plea, since the old regime applied, the eligible old-regime deductions had to be considered. The matter was restored to the AO for that limited purpose, and the appeal was partly allowed.
Practice point
Key Takeaway: Form 10-IEA Opt Out Aniruddha Joshi Ruling
- For business or professional income, Form 10-IEA is what decides the regime. The ITR checkbox cannot change it afterwards.
- Before filing the ITR, check whether a Form 10-IEA was filed for that year, and make the return consistent with it.
- If CPC applies the old regime because of Form 10-IEA, claim the old-regime deductions, such as Chapter VI-A deductions, in rectification or appeal.
- If you dispute the absence of a Section 143(1) intimation, produce portal records. A bare claim will fail.
- This is an ITAT order, so it is persuasive, not binding outside the bench.
Keep reading