Case at a glance
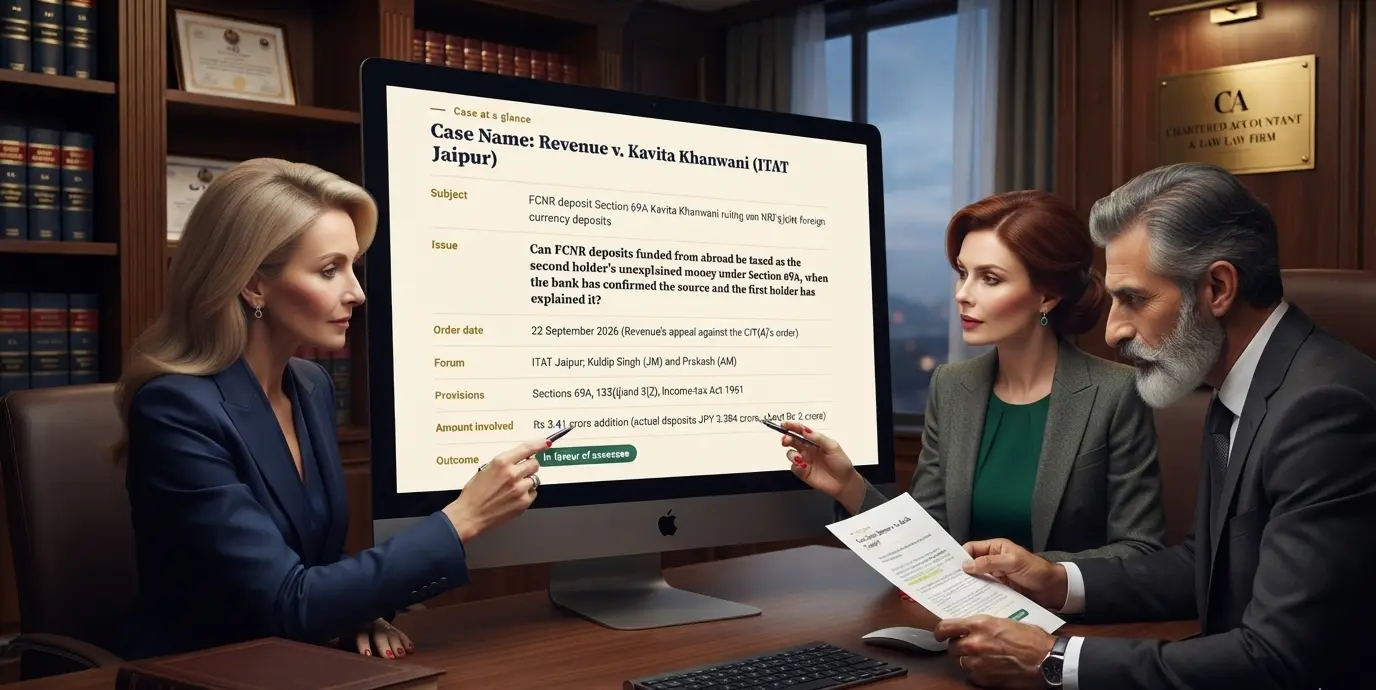
Case Name: Revenue v. Kavita Khanwani (ITAT Jaipur)
- Subject
- FCNR deposit Section 69A Kavita Khanwani ruling on an NRI’s joint foreign currency deposits
- Issue
- Can FCNR deposits funded from abroad be taxed as the second holder’s unexplained money under Section 69A, when the bank has confirmed the source and the first holder has explained it?
- Order date
- 22 September 2026 (Revenue’s appeal against the CIT(A)’s order)
- Forum
- ITAT Jaipur; Kuldip Singh (JM) and Prakash (AM)
- Provisions
- Sections 69A, 133(6) and 5(2), Income-tax Act 1961
- Amount involved
- Rs 3.41 crore addition (actual deposits JPY 3.384 crore, about Rs 2 crore)
- Outcome
- In favour of assessee
Background
Facts of the Case
- The assessee, Kavita Khanwani, is an NRI living in Dubai and originally from Beawar, Rajasthan.
- She and her husband jointly held two FCNR (foreign currency) term deposits with IndusInd Bank. The husband was the first holder and she was the second holder.
- Both deposits were in Japanese yen: JPY 1.726 crore made on 14 October 2017 and JPY 1.658 crore made on 21 February 2018. Together, JPY 3.384 crore, about Rs 2 crore.
- The money was sent from Dubai through banking channels into a joint NRE account, and the deposits were made from that account.
- The AO issued separate Section 69A notices to both spouses. She apparently did not receive hers and gave no reply. The AO added Rs 3.41 crore to her income as unexplained money and treated her as a resident.
- For the same deposits, the AO accepted her husband’s explanation.
- The CIT(A) deleted the addition in her case, and the Revenue appealed to the Tribunal.
The ruling
Summary of Decision: What the Tribunal Held
- The AO had himself written to IndusInd Bank under Section 133(6) on 9 November 2022. The bank confirmed the deposits and where the money came from. The facts were therefore already on the AO’s record, and the Revenue did not question the bank statements.
- The AO had read the yen figures as rupees. The deposits were JPY 3.384 crore, worth about Rs 2 crore, so the addition of Rs 3.41 crore did not match any rupee amount she held.
- Section 69A applies only when a person owns money and cannot explain where it came from. The bank’s records traced each deposit to a Rs 1 crore remittance in the husband’s name, and the AO had accepted his explanation. The same money could not be treated as the wife’s unexplained money.
- The CIT(A) had rightly found her to be a non-resident, based on her Dubai address and NRE/FCNR accounts. The Revenue had not alleged, much less shown, that the money came from any source in India. Under Section 5(2), a non-resident is taxed only on income received or arising in India.
- Finding no error in the CIT(A)’s order, the Tribunal upheld the deletion of the Rs 3.41 crore addition and dismissed the Revenue’s appeal.
Practice point
Key Takeaway: FCNR Deposit Section 69A Kavita Khanwani Ruling
- If a notice on FCNR deposits shows an amount that doesn’t match your deposits, check whether foreign currency was read as rupees.
- If the bank has confirmed the source in reply to a Section 133(6) notice, rely on it. It is strong proof.
- For joint deposits, once one holder’s explanation is accepted, the same money cannot be taxed as unexplained in the other holder’s hands.
- NRIs should keep proof of foreign residence and NRE/FCNR records. A non-resident is taxed only on Indian-source income.
- She got relief only in appeal because she missed the assessment notice. Keep your email and address updated on the income tax portal.
- This is an ITAT order, so it is persuasive, not binding outside the bench.
Keep reading