Case at a glance
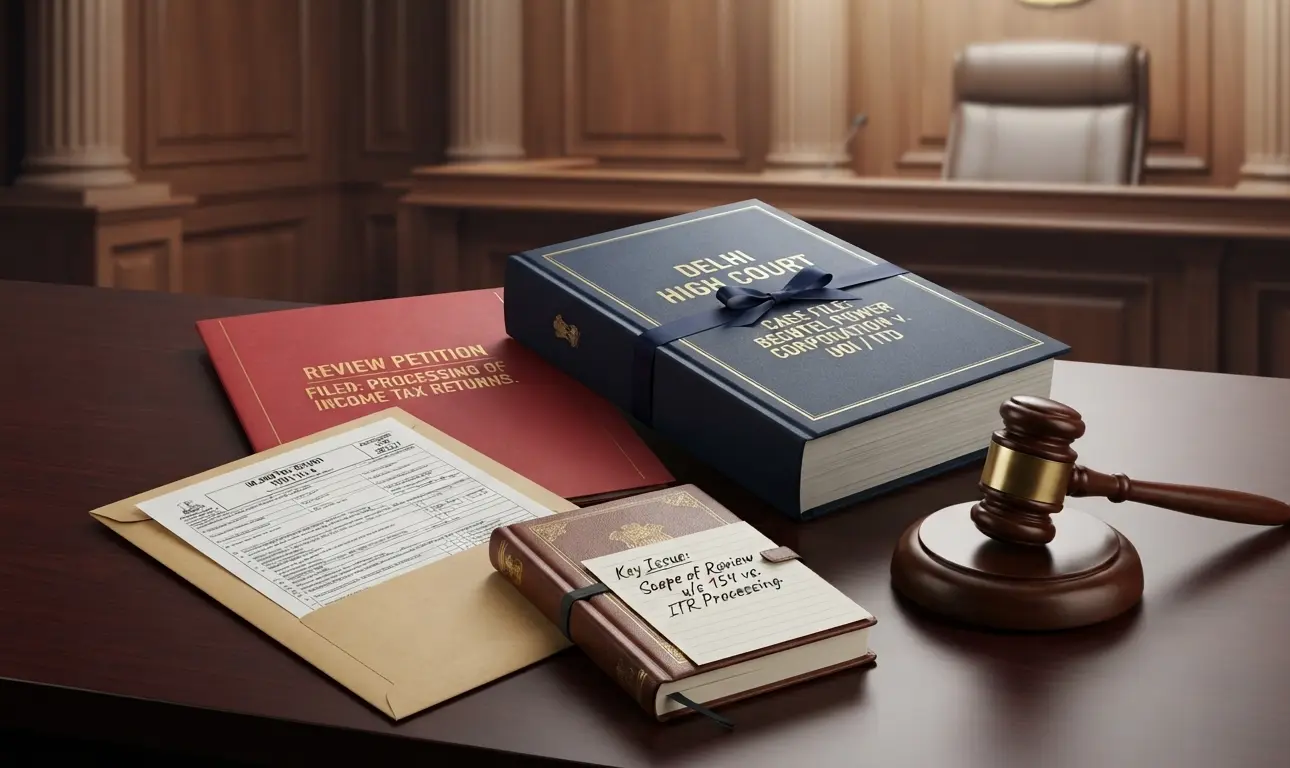
Case Name: Bechtel Power Corporation & Anr. v. ACIT
- Subject
- Review Petition in Income Tax Cases and processing of income tax returns
- Issue
- Whether the assessee could seek review on the ground that the Court had not specifically decided whether the returns were duly and validly filed.
- Citation
- (2026) 349 CTR 803 (Delhi)(HC); Editorial: (2026) 349 CTR 807 (Delhi)(HC)
- Court
- Delhi High Court
- Provisions
- Sections 139, 143(3) and 260A(7), Income-tax Act, 1961
- Assessment Year
- AY 2013-14
- Outcome
- Review Petition Not Maintainable
Background
Why Was the Review Petition Filed?
- The assessee was represented by counsel and was given a full opportunity of hearing before the judgment was pronounced.
- The assessee subsequently sought review of the judgment, contending that the Court had not specifically decided whether the returns were duly and validly filed.
- The earlier judgment had directed that the returns be processed in accordance with law.
- The judgment had also clarified that, if the period available for processing had expired, the returns were to be accepted at face value.
The ruling
Delhi High Court on Review of an Income Tax Judgment
- The High Court found that there was no error apparent on the face of the record warranting exercise of its limited review jurisdiction.
- The Court noted that its earlier judgment had already directed the returns to be processed in accordance with law.
- The earlier judgment had also clarified that, where the period for processing had expired, the returns were to be accepted at face value.
- The limited power of review cannot be exercised merely to substitute another view for a view already taken by the Court after hearing the parties.
- Accordingly, the review petition was held to be not maintainable.
Key takeaway
What This Income Tax Ruling Means
- A review petition cannot be used simply to seek a different view from one already taken by the Court after hearing the parties.
- An error apparent on the face of the record is required for exercise of the Court’s limited review jurisdiction.
- Where the Court has already issued directions for processing income tax returns in accordance with law, a review cannot be used merely to re-argue the matter.
- The ruling relates to AY 2013-14 and concerned the processing of income tax returns in accordance with the directions already issued by the Court.
Keep reading