Pay your credit card bill a day late and you usually pay twice: once in late charges, once in a mark on your credit report. The RBI credit card rules 2026 promise to soften that, and the headlines called it a three-day grace period. The reality is narrower, and it isn’t live yet. Here’s what the RBI’s own notification says, what it leaves out, and what to do while you wait.
Here’s the version most people heard: RBI gives credit card users three extra days to pay. Sounds like relief. But I went to the notification itself, the one dated April 27, 2026, and the picture is more careful than the headlines. The three days are real. So is the date they begin, April 1, 2027, which is still months away. And the notification talks a lot about penalties and credit reporting while saying nothing at all about interest. This guide walks through the RBI credit card guidelines the way a friend with a highlighter would: what’s live, what’s coming, what’s old news dressed up as new, and what you should do about it this month.
RBI Credit Card Rules 2026: What Changed and What Hasn’t Yet
Three separate things get lumped together under “new RBI credit card rules”, and mixing them up is where most of the confusion starts. They have different dates, different rulebooks, and different effects on your wallet. Here’s the timeline in one place.
| Date | What happened | Status today |
|---|---|---|
| Nov 28, 2025 | RBI issues the consolidated Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025 for commercial banks | In force |
| Apr 27, 2026 | RBI issues Amendment Directions, 2026 (RBI/2026-27/29), rewriting one paragraph on past-due reporting and late charges | Issued, not yet effective |
| Jul 1, 2026 | Weekly credit reporting by lenders to credit bureaus starts (RBI deferred it from the earlier April 1, 2026 date) | In force |
| Apr 1, 2027 | The 3-day rule and the new late-charge base come into force | Upcoming |
| Sources: RBI Directions and Amendment Directions (see Sources at the end). | ||
So when someone tells you “the new RBI rules are here”, ask which one. The April 2027 change is the one people mean when they say “grace period”, and it’s the one that hasn’t started.
The 3-Day Rule, Explained With Dates
Strip away the legal drafting and the amendment does two things. Your card issuer can report your account to the credit bureaus as “past due”, or charge late payment fees and related penal charges, only once you’ve been past due for more than three days. Same trigger and same wait, for both.
Now the part people skip. Those days aren’t counted from the moment the three days end. They’re counted from the due date printed on your statement. So the three days work like a threshold you have to cross, not a free pass that gets quietly subtracted later. This is why calling it a classic credit card grace period isn’t quite right.
- Interest isn’t mentioned. The amended paragraph covers penal charges and credit reporting. It doesn’t say interest stops for three days. If you carry a balance past the due date, check your card’s terms before assuming anything.
- It isn’t live until April 1, 2027. Until then your issuer’s current terms apply. Don’t plan around a cushion your bank hasn’t confirmed in writing.
Late Payment Charges: What “Outstanding Amount” Means
The second change is quieter, but it could save more money. From April 1, 2027, credit card late payment charges and related charges can be levied only on the outstanding amount after the due date, not on the total amount due.
Why does that matter? Many issuers set late fees in slabs tied to the total amount due on your statement. Under the new wording, the base shifts to what’s still unpaid after the due date. Here’s how that plays out.
One thing to keep straight: the paragraph we read doesn’t fix a fee amount. How much an issuer charges is still the issuer’s call. What the rule changes is the number the charge is measured against.
The Rule at a Glance
| Item | What the new rule says | What it doesn’t say |
|---|---|---|
| When penal charges can start | Only after more than 3 days past due | Doesn’t say interest pauses |
| How days are counted | From the due date on your statement | The count doesn’t restart on day 4 |
| What late charges apply to | Outstanding amount after the due date | Doesn’t set the fee amount |
| Credit bureau reporting | “Past due” reported only after more than 3 days | Doesn’t change how scores are calculated |
| Starts | April 1, 2027 | Nothing changes on your bill today |
| Based on paragraph 23(5) as amended by RBI/2026-27/29 dated April 27, 2026. | ||
Weekly Credit Reporting and Your CIBIL Score
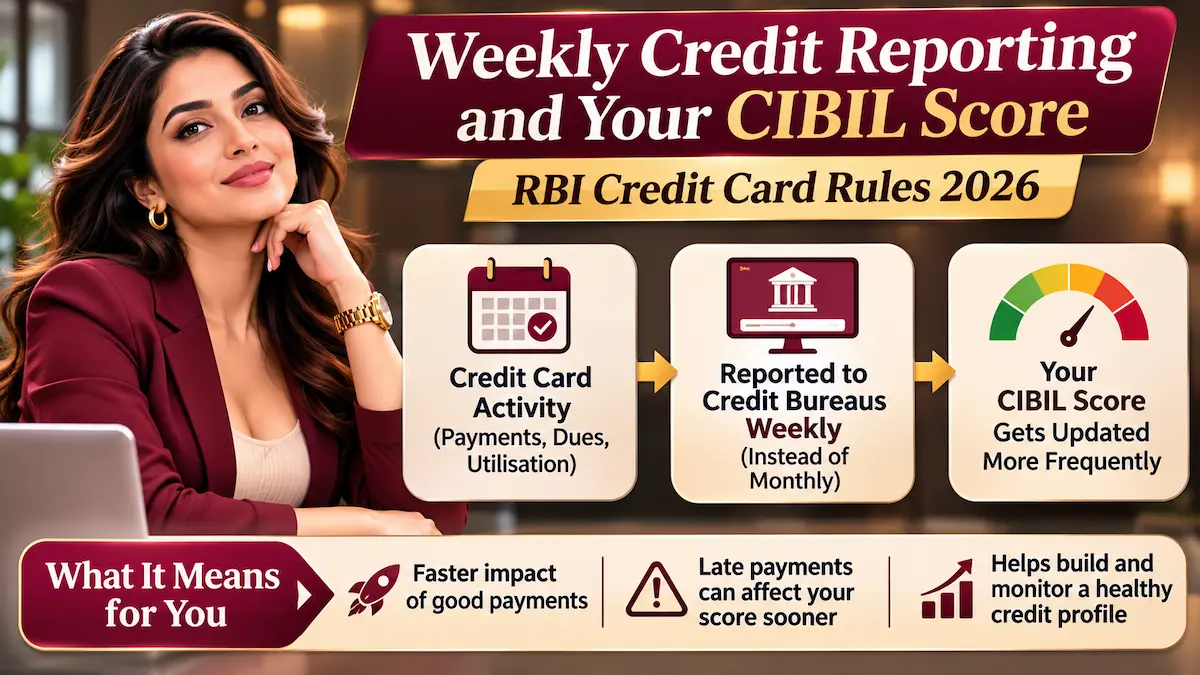
Separately from the card rules, RBI changed how often lenders send data to the credit bureaus. The old rhythm was fortnightly. Lenders now send weekly incremental updates plus a full monthly file, and that applies to all four bureaus, CIBIL included. RBI first set April 1, 2026 for this, then deferred it to July 1, 2026, as Business Standard reported in December 2025. That date has passed, so weekly credit reporting is now live.
In plain terms, good news and bad news both travel faster now. Clear your dues and it can show up on your report sooner. Miss a due date and that shows up sooner too. The formula behind your CIBIL score hasn’t changed, and weekly reporting doesn’t entitle you to a free report every week; that’s a separate matter.
The two changes also fit together. Weekly reporting decides how fast information reaches the bureaus. From April 2027, the 3-day rule will decide what counts as “past due” in the first place.
Rules You Already Have
Some of what gets sold as “new” isn’t. It’s useful, though, and many cardholders don’t know they can lean on it. These protections come from the earlier 2022 rules and were carried into the consolidated November 2025 Directions.
- No credit card limit increase without your consent. Your bank can’t upgrade your card or raise your limit unless you explicitly agree. Silence isn’t approval.
- No unsolicited cards. Issuers shouldn’t send you a card you never asked for.
- Clear terms upfront. Fees and key conditions, including the Most Important Terms and Conditions (MITC), are meant to be disclosed before you sign up.
- Credit card closure rules. Once your dues are cleared, the bank must close the card within seven working days of your request. A delay can attract compensation of ₹500 per day under the Directions.
If your bank doesn’t sort it out, escalate in writing to its grievance cell first, then to the RBI Integrated Ombudsman at cms.rbi.org.in. Keep dates, call references and screenshots.
Reported Elsewhere, Not Confirmed
A few claims are doing the rounds that we couldn’t match to the RBI notification itself. They may turn out to be real. They may also be draft proposals or secondary summaries. Until you see them in an RBI notification, treat them with some caution.
- A ban on bundled insurance or add-on sales with cards from July 1, 2026. One explainer describes it as based on draft guidelines. We didn’t find it in the April 27, 2026 notification.
- Disaster-related relief from July 1, 2026. Reported by a news outlet, but not in the paragraph of the amendment we read.
What to Do Now
Rules that start in April 2027 shouldn’t change how you pay in November 2026. A few habits will protect you today and make the new rule a bonus later.
- Set autopay for the total due, not the minimum
- Keep a due-date reminder anyway, because autopay fails when the bank account is short
- Don’t bank on three free days. Interest isn’t addressed in the notification
- Pay as much as you can before the due date, even if it’s not the full bill
- Weekly reporting rewards on-time behaviour quickly
- Keep utilisation low and check your credit report once a month
If these rules made you rethink which card you carry, compare options on annual fee, how you actually spend, and how easy it is to pay on time. Approval is the bank’s decision and isn’t guaranteed.
Disclosure: some links on this page are affiliate links. If you apply through them we may earn a commission, at no extra cost to you. Commission doesn’t decide which cards we write about.
Frequently Asked Questions — RBI Credit Card Rules 2026
- RBI (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025, dated November 28, 2025: rbi.org.in
- RBI Amendment Directions, 2026 (RBI/2026-27/29), dated April 27, 2026, modifying paragraph 23(5): text as published by TaxGuru. Cross-check on rbi.org.in.
- RBI deferral of credit information reporting norms to July 1, 2026: Business Standard, Dec 2025. Cross-check the notification on rbi.org.in.