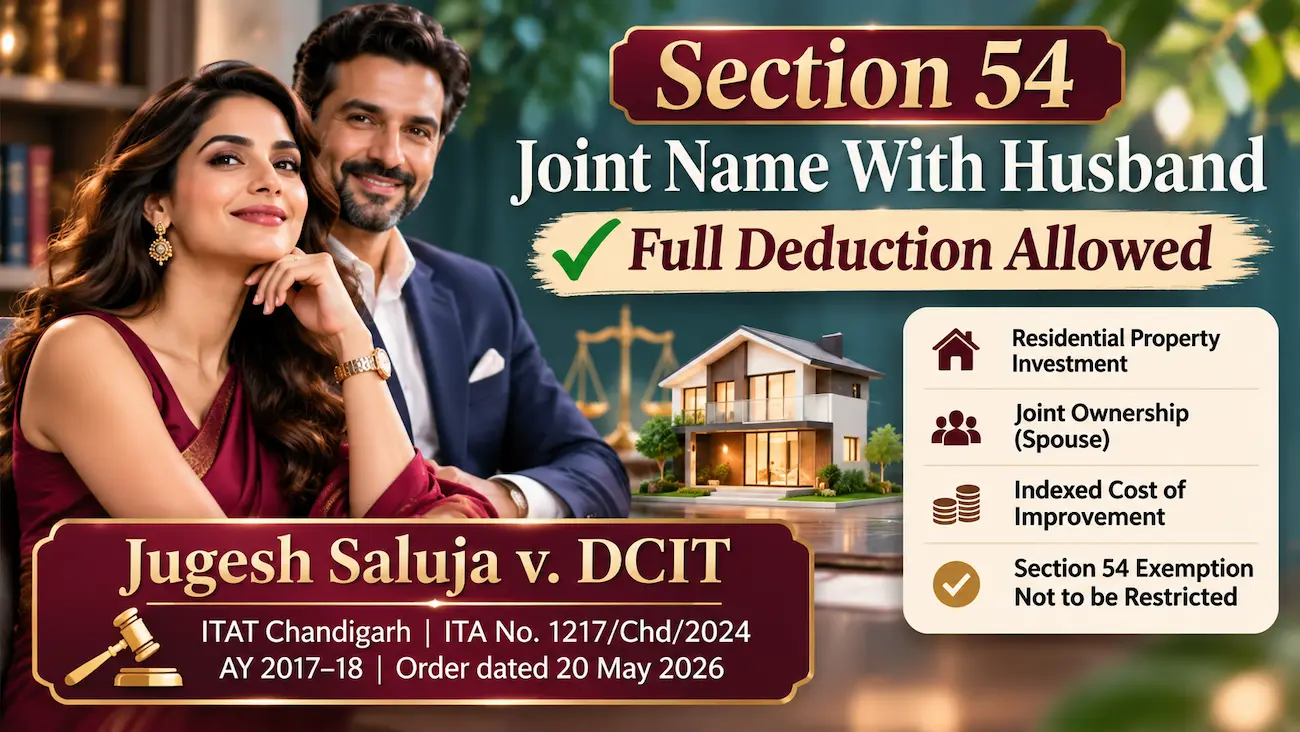
Jugesh Saluja sold her house in Sector 33-A, Chandigarh, and paid Rs.2.13 crore from her own bank account for a new flat in Pune. Because her husband’s name also appeared on the agreement, the Assessing Officer allowed her only half the Section 54 deduction. He also stripped out GST and other charges from the cost of the new flat, and disallowed the entire Rs.1.03 crore she had claimed as indexed cost of acquisition and improvement, because bills going back to the 1980s could no longer be produced.
ITAT Chandigarh has now settled the Section 54 joint name with husband question in her favour: where the entire investment came from the assessee, adding the spouse as a joint holder does not reduce the deduction. The Tribunal also allowed GST and most purchase-related charges as part of the cost of the new house, excluded optional club charges, and sent the improvement-cost issue back for a fresh computation at PWD rates.
Quick Answer
Can the Section 54 deduction be cut to 50% because the new house is bought jointly with the husband?According to ITAT Chandigarh, no, if the assessee paid the whole price. In this Section 54 joint name with husband case, the assessee paid the entire consideration from her own bank account and the Revenue showed no contribution from her husband. Following the Karnataka High Court in Jennifer Bhide and the Delhi High Court in Ravinder Kumar Arora, the Tribunal deleted the 50% restriction. It held that GST, stamp duty, registration and infrastructure-type charges form part of the cost of the new house, but optional club charges do not.
Case Snapshot
| Case Name | Jugesh Saluja v. Deputy Commissioner of Income Tax, Circle 4(1), Chandigarh (ITAT Chandigarh, 2026) |
| Citation | ITA No. 1217/Chd/2024 |
| Court / Bench | Income Tax Appellate Tribunal, Chandigarh “A” Bench |
| Coram | Shri Laliet Kumar (Judicial Member) & Shri Krinwant Sahay (Accountant Member); order authored by Shri Laliet Kumar |
| Assessment Year | 2017-18 |
| Date of Hearing | 22 April 2026 |
| Date of Order | 20 May 2026 |
| Key Issues | (1) Whether the Section 54 deduction can be restricted to 50% because the new house was bought jointly with the husband; (2) which payments form part of the cost of the new house; (3) whether indexed cost of improvement can be disallowed entirely for want of old bills |
| Outcome | Assessee’s appeal partly allowed for statistical purposes: 50% restriction deleted; club charges excluded; cost of improvement remanded for recomputation at PWD rates |
| Order Copy | Download the full order |
Table of Contents
Legal Issue: Section 54 Joint Name With Husband
Section 54 exempts long-term capital gains on the sale of a residential house to the extent the gains are invested in another residential house, bought within one year before or two years after the sale, or constructed within three years. The deduction is the capital gain or the cost of the new house, whichever is lower.
The section does not say that the new house must be bought in the assessee’s sole name. Families often add a spouse as a joint owner for convenience or succession. Assessing Officers often respond by allowing the deduction only in proportion to the assessee’s share in the title. This case raised that Section 54 joint name with husband question, together with two practical questions every house seller faces: which payments count as the cost of the new house, and what happens when decades-old construction bills are lost.
Facts of the Case
The house sold. The assessee bought a residential plot of 523.13 square yards at House No. 156, Sector 33-A, Chandigarh, by a registered sale deed dated 2 September 1985, at a total cost of Rs.2,49,000. She built a house on it in FY 1986-87 at a cost of Rs.6,25,100, and carried out further improvements of Rs.4,89,000 in FY 1996-97 and Rs.6,50,000 in FY 2006-07. She sold the house by a registered sale deed dated 14 December 2016. [Paras 3, 9 and 10 of the order]
The return. For AY 2017-18, the sale consideration was taken under Section 50C at Rs.4,39,66,173. The assessee claimed the following, and declared long-term capital gains of Rs.73,42,538: [Para 3 of the order]
| Item | Amount (Rs.) |
|---|---|
| Sale consideration adopted under Section 50C | 4,39,66,173 |
| Less: indexed cost of acquisition and improvement | 1,03,41,977 |
| Less: deduction under Section 54 (new flat in Pune) | 2,12,81,658 |
| Less: deduction under Section 54EC (specified bonds) | 50,00,000 |
| Long-term capital gains declared | 73,42,538 |
The new flat. On 26 July 2017, the assessee paid Rs.2,12,81,658 from her Axis Bank account, the same account in which the sale consideration had been received, for leasehold rights in Unit No. 098-0904, Tower 098, Amanora Park Town, Pune. The Agreement to Lease, dated 27 July 2017, was in the joint names of the assessee and her husband, Shri Gurcharan Singh Saluja.
The order records that the payment included a one-time premium of Rs.1,70,22,000 with CGST and SGST of Rs.10,21,320 each. The assessee also paid stamp duty of Rs.6,81,000, registration charges of Rs.30,000, and charges for utilities, the Amanora Cluster Fund, infrastructure, club membership and the Amanora Environment Fund. [Paras 15 and 16 of the order]
The assessment. The Assessing Officer disallowed the entire Rs.1,03,41,977 claimed as indexed cost of acquisition and improvement because bills and vouchers for the construction and improvements were not produced. He held that the Section 54 deduction was available only for the assessee’s 50% share in the jointly held flat, excluded GST, infrastructure, utility, cluster fund, club and other incidental charges from the cost, and restricted the deduction to Rs.88,66,540. With additions of Rs.1,03,41,977 and Rs.1,24,15,208, income was assessed at Rs.3,13,09,655. The CIT(A), NFAC, confirmed both additions on 5 November 2024 after calling for a remand report. [Paras 4 and 5 of the order]
Arguments of the Parties
For the Assessee (Shri Tejmohan Singh, Advocate)
- The cost of improvement could not be rejected merely because old bills were unavailable. The house existed, and the stamp valuation authority itself had valued the superstructure when the house was sold.
- The assessee had furnished year-wise details of construction and improvements. If the Assessing Officer doubted them, he should have used the valuation mechanism in Section 55A instead of disallowing the whole claim.
- The entire consideration for the Pune flat was paid from the assessee’s own bank account out of the sale proceeds. Including the husband as a joint holder could not restrict the deduction.
- Reliance was placed on the Karnataka High Court in Jennifer Bhide and the Delhi High Court in Ravinder Kumar Arora.
For the Revenue (Shri Vivek Vardhan, Addl. CIT, Sr. DR)
- Despite repeated opportunities during the assessment, the assessee produced no supporting evidence for the claimed cost of improvement.
- The new flat was admittedly owned jointly, so the Assessing Officer rightly restricted the Section 54 deduction to the assessee’s share of ownership.
- The lower authorities’ orders should be upheld on both issues.
Court/Tribunal’s Decision
Partly allowing the assessee’s appeal for statistical purposes, the Tribunal held:
(i) That, as the entire investment in the new flat came from the assessee’s own funds and the husband contributed nothing, the Section 54 deduction could not be restricted merely because he was a joint holder. [Paras 19 to 21 of the order]
(ii) That the premium, GST, stamp duty, registration, utility, cluster fund, infrastructure and environment fund charges form part of the cost of the new house, but optional club charges and the taxes on them do not. [Paras 17 and 18 of the order]
(iii) That the cost of construction and improvement could not be wholly disallowed for want of old bills; the Assessing Officer must recompute it on the 3,300 square feet in the sale deed at PWD rates for each relevant year, with indexation. [Paras 11 to 13 of the order]
Reasoning Behind the Decision
1. The source of the investment, not the name on the deed, decides the deduction. The Tribunal found it undisputed that the full price of the Pune flat was paid from the assessee’s Axis Bank account, the same account into which the sale proceeds were received. The Revenue brought no material to show any contribution by the husband. The only reason for restricting the deduction was that his name appeared in the Agreement to Lease. [Paras 15, 19 and 20 of the order]
2. High Court authority settles the joint-name point. The Tribunal held that the issue is “no longer res integra”. In DIT v. Mrs. Jennifer Bhide (2011) 349 ITR 80 (Kar) and CIT v. Ravinder Kumar Arora 342 ITR 38 (Del), the High Courts held that where the entire investment in the new house is made by the assessee, the deduction cannot be denied because the house is bought jointly with a spouse or another family member. The Tribunal held that “the substance of the transaction and the source of investment are material considerations, not mere inclusion of a joint name in the title documents.” [Paras 7 and 20 of the order]
3. Payments integral to acquiring the flat are part of its cost. The Tribunal examined each payment. It held that the one-time premium, the GST on it, stamp duty, registration charges, utility charges, the Amanora Cluster Fund, infrastructure charges and the Amanora Environment Fund were directly connected with and incidental to acquiring the leasehold rights. They therefore partake of the character of cost of acquisition and qualify for the Section 54 deduction. [Para 17 of the order]
4. Optional club charges are not. Club membership was optional and not a condition for acquiring or enjoying the flat. It neither enhanced the assessee’s rights in the property nor formed an inseparable part of the acquisition. The fact that the developer collected it along with the other charges did not make it part of the cost of the house. The club charges and the taxes on them were therefore excluded. [Para 18 of the order]
5. A house that exists must have cost something to build. On the cost of improvement, the Tribunal relied on the registered sale deed of 14 December 2016, which recorded a constructed house with a covered area of 3,300 square feet. The stamp valuation authority had valued that superstructure at Rs.800 per square foot, or Rs.26,40,000. Once the construction was admitted by the parties and recognised by the registering authority, the claim could not be rejected in full merely because bills for work done decades earlier were unavailable. The Assessing Officer had brought nothing to show that no construction or improvement was ever carried out. [Paras 10 and 11 of the order]
6. Estimation at PWD rates, not total disallowance. The Tribunal observed that it is common knowledge that complete bills for construction done several decades earlier may not be preserved. The chronology was established: plot bought in FY 1985-86, house built in FY 1986-87, improvements in FY 1996-97 and FY 2006-07, and sale in December 2016. It therefore directed the Assessing Officer to recompute the cost of construction and improvement on the covered area of 3,300 square feet at the PWD rates prevailing in each of those years, and to allow indexation in accordance with law. [Paras 12 and 13 of the order]
Key Legal Principles
First, where the entire investment in the new residential house comes from the assessee’s own sale proceeds, the Section 54 deduction cannot be reduced because a spouse is named as a joint holder; the source of the funds, not the names on the title, decides the claim.
Second, payments directly connected with and incidental to acquiring the new house, including GST, stamp duty, registration and the developer’s infrastructure and fund charges, form part of its cost, while optional extras such as club membership do not.
Third, where the existence of a constructed house is proved by the sale deed, its cost of construction cannot be disallowed in full for lack of old bills; it must be estimated on a reasonable basis.
Practical Implications for House Sellers
- Pay from your own account and keep the trail: The assessee won the joint-name point because she proved that the whole price was paid from the bank account that received the sale proceeds, and the Revenue showed no contribution from her husband. Keep that statement ready from the first notice.
- Record a non-contributing spouse clearly: If the spouse is added only for convenience, keep evidence that he or she paid nothing. Where a co-owner does contribute, claim only your own payment, as in Neelam Shamsher Kashyap (ITAT Mumbai, 2025).
- Claim the full cost of the new house: Include GST, stamp duty, registration and the developer’s charges that are tied to the purchase, such as infrastructure charges and township or environment funds. Leave out optional items such as club membership, or be ready to see them disallowed.
- Old house, no bills: Use the sale deed’s covered area, the stamp authority’s valuation of the structure, and building permissions or completion certificates to prove construction. Ask in writing for an estimate at PWD rates or a reference to the Valuation Officer under Section 55A.
- Check the rules for your year of sale: This case concerns a sale in December 2016 (AY 2017-18), when the base year for indexation was 1981. For sales from AY 2018-19 the base year is 2001, so improvement costs incurred before 1 April 2001 are not counted. Later changes to indexation for property sales from 23 July 2024 must also be considered.
- Mind the Rs.10 crore cap: From AY 2024-25, the cost of a new house above Rs.10 crore is ignored for the Section 54 deduction. It did not arise here, but it matters for high-value purchases.
Related Judgments and Limitations
| Case | Forum | Relevance |
|---|---|---|
| DIT v. Mrs. Jennifer Bhide, (2011) 349 ITR 80 (Kar) | Karnataka High Court | House and Section 54EC bonds bought jointly with a husband who contributed nothing; full deduction allowed. Relied on here |
| CIT v. Ravinder Kumar Arora, 342 ITR 38 (Del) | Delhi High Court | Section 54F allowed where the new house was bought in joint names with the wife. Relied on here |
| CIT v. Kamal Wahal, 351 ITR 4 (Del) | Delhi High Court | Section 54F allowed where the new house was bought in the wife’s sole name out of the assessee’s funds |
| ITO v. Neelam Shamsher Kashyap, ITA No. 2053/Mum/2025 (27 October 2025) | ITAT Mumbai | House bought jointly with son-in-law, who paid Rs.50 lakh; deduction allowed for the assessee’s own investment of Rs.3.68 crore; 50% restriction deleted |
| Vipin Malik (HUF) v. CIT, 330 ITR 309 (Del) | Delhi High Court | Contrary result: HUF funds invested in a house in the names of the karta and his mother; Section 54F denied because the HUF did not acquire the house |
| Prakash v. ITO, 312 ITR 40 (Bom) | Bombay High Court | Contrary result: Section 54F denied where the new house was bought in the son’s name |
1. It is only a partial win. The appeal was “partly allowed for statistical purposes”. The club charges were disallowed, and the cost of improvement has gone back to the Assessing Officer, so the final tax depends on the PWD-rate computation.
2. The husband contributed nothing. The ruling rests on the finding that the entire price came from the assessee. Where a spouse or relative also pays, only the assessee’s own investment qualifies.
3. The High Courts are not unanimous. The Delhi and Bombay High Courts have denied the deduction where the house was bought wholly in another person’s name, or where an HUF’s funds went into a house held by individuals. The view of your jurisdictional High Court matters.
4. Leasehold rights were not in dispute. The Revenue did not question whether acquiring leasehold rights in the Pune flat counted as purchasing a residential house. The Tribunal therefore did not decide that point.
5. A figure in the order does not add up. The order says the payment of Rs.2,12,81,658 “comprised” the premium and GST, but those items total Rs.1,90,64,640. The balance of Rs.22,17,018 appears to relate to the other charges, which the order does not break down.
Frequently Asked Questions
Yes, if you paid the entire price from your own funds. ITAT Chandigarh, following the Karnataka and Delhi High Courts, held that naming the husband as a joint holder does not reduce the deduction where he contributed nothing.
Then you can claim the deduction only for the amount you invested. In Neelam Shamsher Kashyap, ITAT Mumbai allowed the assessee’s own Rs.3.68 crore investment in a house bought jointly with her son-in-law, who paid Rs.50 lakh.
Yes. ITAT Chandigarh held that GST, stamp duty, registration charges and charges tied to the purchase, such as infrastructure charges and the developer’s township and environment funds, are part of the cost of the new house for the Section 54 deduction.
No. The Tribunal held that club membership was optional and not a condition for acquiring the flat, so the club charges and the taxes on them were excluded from the Section 54 deduction.
It cannot be disallowed entirely if the construction is proved by other evidence, such as the covered area in the sale deed. ITAT Chandigarh directed the Assessing Officer to estimate the cost at PWD rates for each year in which the work was done.
Final Verdict
Based on the above facts and reasoning, ITAT Chandigarh partly allowed the appeal of Jugesh Saluja for AY 2017-18. It deleted the restriction of her Section 54 deduction to 50%, holding that her husband’s name on the Agreement to Lease did not matter when she had paid the entire price from her own sale proceeds. It treated GST, stamp duty, registration and compulsory developer charges as part of the cost of the new flat, excluded optional club charges, and directed a fresh computation of the cost of construction and improvement at PWD rates.
In my view, this is one of the most practical Section 54 rulings of 2026, because it answers three questions that house sellers routinely face in a single order, each with clear reasoning. Its strength on the joint-name point comes from the High Court rulings it follows. Its limits are equally clear: the win depends on proving that the spouse paid nothing, and the final tax will turn on the PWD-rate computation still to be made.
Also Read
- Neelam Shamsher Kashyap (ITAT Mumbai, 2025) — Section 54 deduction allowed for the assessee’s own share in a house co-owned with her son-in-law
- Chetana Resorts v. ITO (ITAT Pune, 2026) — Section 50C stamp value applies on the agreement date
- All Section 54 rulings on TaxBizMantra
- All ITAT Chandigarh rulings on TaxBizMantra
Corresponding Provisions Under the Income-tax Act, 2025
This case was decided under the Income-tax Act, 1961, for Assessment Year 2017-18. Under the Income-tax Act, 2025, the exemption in Section 54 for reinvestment in a residential house appears in Section 82, and the stamp duty rule in Section 50C appears in Section 78. Confirm these against the bare Act before relying on them. For other sections, see our Income Tax Act 2025 vs 1961 mapping hub.
Source Judgment: Jugesh Saluja v. DCIT, Circle 4(1), Chandigarh (ITAT Chandigarh, 2026), ITA No. 1217/Chd/2024, order pronounced 20 May 2026. This order can be looked up on the official ITAT judicial search portal using the ITA number above.
Legal Disclaimer: This article is for general informational purposes only and analyses a specific Tribunal order under the Income-tax Act, 1961, as it applied to Assessment Year 2017-18. It is not legal or tax advice, and it does not account for developments after the date of publication or for the specific facts of any reader’s case. Capital gains rules, including indexation and the Section 54 cap, have changed since the year involved. Readers should verify the applicable current position and consult a qualified Chartered Accountant or tax professional before acting on this or any similar matter.